How Much Corpus for ₹2 Lakh/Month Retirement in India?
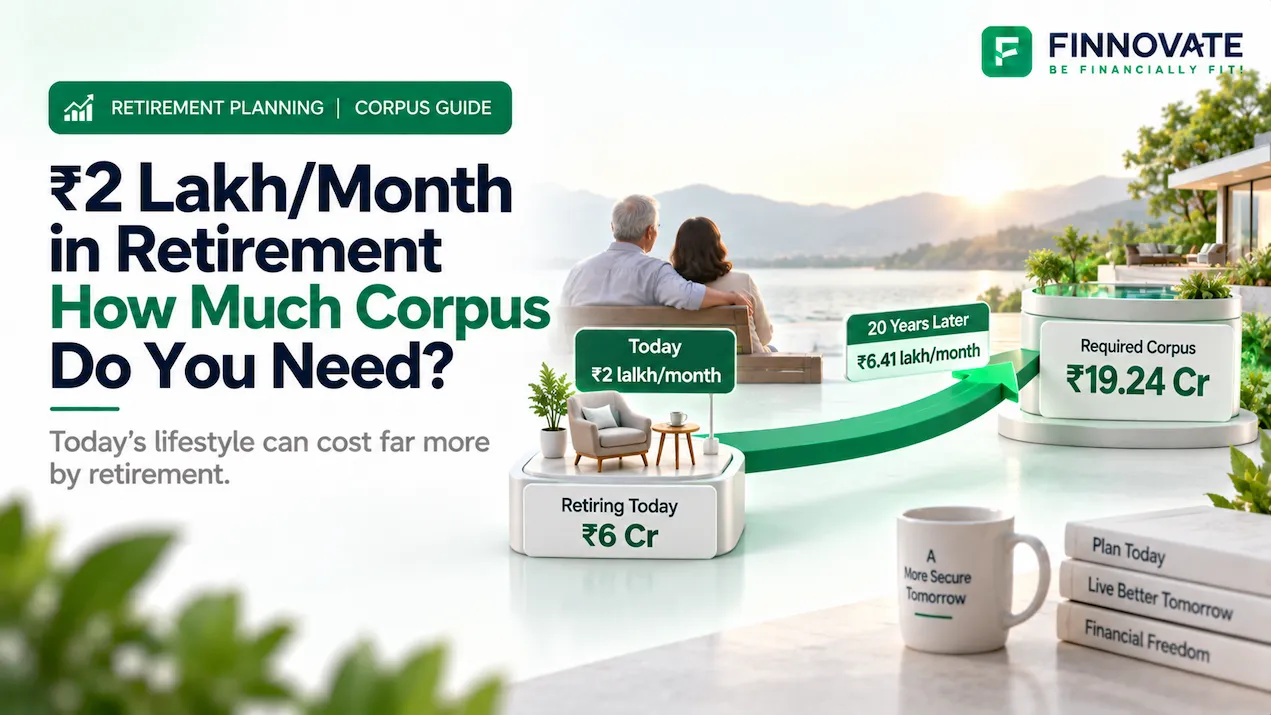
Want ₹2 lakh per month after retirement? See the corpus needed today and after 10, 20 or 30 years, plus inflation, SIP and existing investment impact.
Retirement learning centre
From working out the corpus you need, to building it, preparing for the day you stop working, and drawing a monthly income that lasts.
40 guides across our retirement, FIRE and NRI categories, newest added Oct 9, 2026.
Start here
The clearest introduction we have to retirement maths: what a monthly income of Rs 1 lakh needs in corpus, how inflation moves that number, and what to save each month to get there.
Read the guideFour stages, each with one guide to read first and two to go deeper. Work through them in order, or jump to the stage you are at.
Start with the number. These guides show how a monthly income target turns into a corpus, and why the same crore is enough for one family and not another.
Want ₹2 lakh per month after retirement? See the corpus needed today and after 10, 20 or 30 years, plus inflation, SIP and existing investment impact.
Once you know the target, pick the vehicles. NPS, EPF, PPF and equity funds each have rules on lock-in, tax and withdrawal that matter more than their headline returns.
NPS vs mutual funds for retirement: compare liquidity, tax, lock-in, asset allocation, annuity rules and withdrawals to decide if you need one or both.
The five years before retirement decide how calm the next thirty are. Audit what you own, close the gaps, and set the structure before the salary stops.
Most families at 55 think their retirement plan is on track. A pre-retirement audit almost always finds corpus gaps, wrong insurance, and no income plan.
Turning a corpus into a monthly cheque is its own discipline. How SWP compares with deposits, why the first few years of returns matter most, and what to do when markets fall.
SWP vs FD for retirement: compare income, risk, inflation, tax, liquidity and corpus sustainability to understand where each may fit after retirement.
Three free tools that turn the guides above into your own figures.
Retiring well before 60, returning from abroad, or planning for your parents: the standard playbook needs changes.
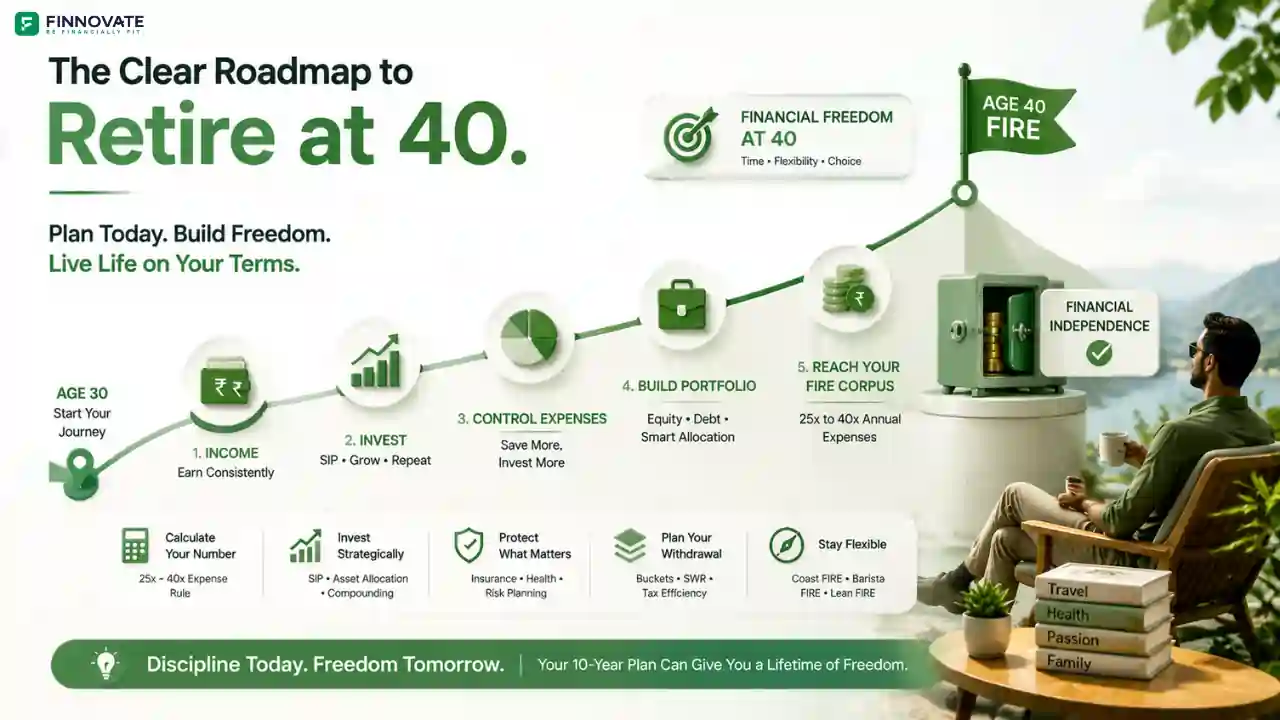
Retiring at 40 or 50 changes the maths: a longer drawdown, fewer compounding years, and no pension to fall back on.
Retiring at 40 in India requires 30 to 40 times inflation-adjusted annual expenses - not just 25x.
Returning NRIs, parents who have not planned, and overseas retirement accounts each need a different playbook.
Planning to retire in India as an NRI? Learn how to plan your retirement corpus, overseas assets, tax residency, NRE/NRO accounts, currency, healthcare and…
The newest guides across our retirement, FIRE and NRI categories.
The guides above give you the method. Finnovate's SEBI-registered advisers apply it to your numbers.
View retirement planning services