Is ₹2 Crore Enough for Retirement? Here's How to Know
Finnovate’s editorial team researches and creates financial content using trusted sources, regulatory references and inputs from subject experts.
You have finally built a ₹2 crore retirement corpus.
For a moment, it feels like the hard part is over. Then another question starts bothering you:
A corpus can look large today and still fall short if it needs to fund 25 or 30 years of expenses, keep pace with inflation and support the lifestyle you want.
So, instead of looking at ₹2 crore as one big number, let us see what it can actually mean in retirement.
So, Is ₹2 Crore Enough for Retirement?
There is no single retirement corpus that works for everyone.
Someone retiring at 60, living in a paid-off home and spending ₹50,000 a month is in a very different position from someone retiring at 45 and spending ₹1.5 lakh a month.
The difference comes down to a few things:
- How much you spend
- When you retire
- How long the money needs to last
- How your portfolio performs
- How much income you have apart from your investments
That is why retirement planning does not begin with a fixed corpus number.
It works backwards from your expenses, retirement age, retirement duration, inflation, other income and expected returns.
It is how much you will actually need to spend in retirement.
How Much Will You Need to Spend in Retirement?
Your retirement expenses are likely to look different from your current expenses.
Some costs may fall after you stop working, while others, especially healthcare, can become more important.
Housing is another major factor. A retiree with a fully paid-off home has a very different expense structure from someone who will continue paying rent or a home loan.
Start with your expected monthly retirement spending and see what it means relative to a ₹2 crore corpus.
| Monthly retirement spending | Annual spending | Annual spending as % of ₹2 crore |
|---|---|---|
| ₹50,000 | ₹6 lakh | 3% |
| ₹75,000 | ₹9 lakh | 4.5% |
| ₹1 lakh | ₹12 lakh | 6% |
| ₹1.5 lakh | ₹18 lakh | 9% |
At ₹50,000 a month, your starting annual spending is 3% of the corpus.
At ₹1.5 lakh a month, it is already 9%.
And that is before accounting for your expenses rising in the years ahead.
Which brings us to one of the biggest variables in retirement planning.
What Will Inflation Do to Your Retirement Expenses?
Probably more than it appears at first.
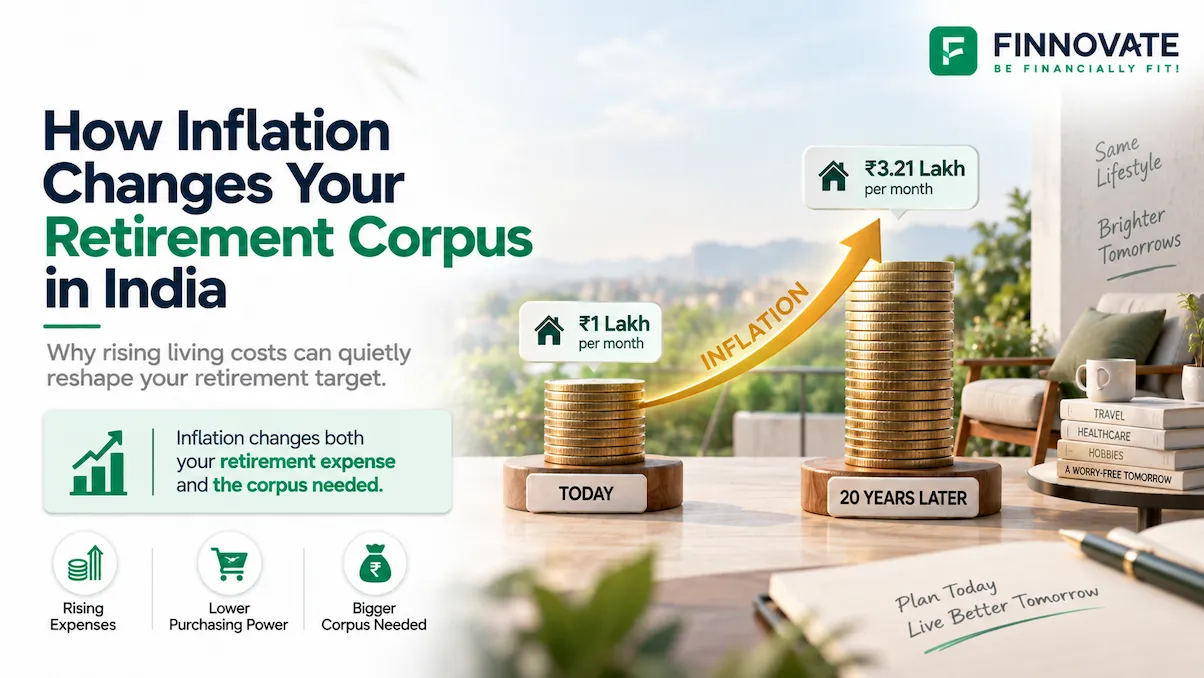
If you spend ₹1 lakh a month today, it does not mean ₹1 lakh will support the same lifestyle 10, 20 or 30 years from now.
Here is what a ₹1 lakh monthly expense becomes under different inflation assumptions:
| Years from now | At 4% inflation | At 5% inflation | At 6% inflation |
|---|---|---|---|
| Today | ₹1.00 lakh | ₹1.00 lakh | ₹1.00 lakh |
| 10 years | ₹1.48 lakh | ₹1.63 lakh | ₹1.79 lakh |
| 20 years | ₹2.19 lakh | ₹2.65 lakh | ₹3.21 lakh |
| 30 years | ₹3.24 lakh | ₹4.32 lakh | ₹5.74 lakh |
These are illustrations, not forecasts.
The purpose of using different inflation rates is to see whether your retirement plan continues to work even when expenses rise faster than expected.
And there is another side to inflation that is easy to miss.
₹2 Crore Today Is Not the Same as ₹2 Crore 20 Years From Now
This matters especially if ₹2 crore is your future retirement target, rather than the amount you already have when you retire.
Suppose you are 40 today and want to retire at 60 with ₹2 crore.
At 6% annual inflation, ₹2 crore received 20 years from now would have purchasing power similar to only about ₹62.4 lakh today.
This is why there is a major difference between saying:
and
“My target is to have ₹2 crore when I retire 20 years from now.”
If retirement is still years away, the corpus target itself needs to account for inflation.
How Long Does ₹2 Crore Need to Last?
Your retirement age can change the answer dramatically.
Someone retiring at 45 may need the corpus to support several decades of expenses. Someone retiring at 60 may be planning for a shorter period.
For illustration:
| Retirement age | Example planning horizon |
|---|---|
| 45 | 40 years |
| 50 | 35 years |
| 55 | 30 years |
| 60 | 25 years |
These are planning horizons, not assumptions about how long a person will actually live.
An amount that may work over 25 years cannot automatically be assumed to work over 40 years.
Which brings us to the question most people ask when they hear “₹2 crore retirement corpus”.
How Much Can You Withdraw From ₹2 Crore?
One way to understand retirement income is through the starting withdrawal rate.
Here is what different first-year withdrawal rates mean for a ₹2 crore corpus:
| Starting withdrawal rate | Annual withdrawal | Initial monthly withdrawal |
|---|---|---|
| 3% | ₹6 lakh | ₹50,000 |
| 3.5% | ₹7 lakh | ₹58,333 |
| 4% | ₹8 lakh | ₹66,667 |
| 5% | ₹10 lakh | ₹83,333 |
| 6% | ₹12 lakh | ₹1 lakh |
But these numbers need to be interpreted carefully.
Your actual outcome depends on:
- Investment returns
- Inflation
- How much you withdraw
- How quickly withdrawals increase
- How long retirement lasts
- The order in which market returns occur
That last point is important.
If markets fall sharply in the early years of retirement while you are also withdrawing money, you may have to sell more investments when portfolio values are already down.
So the better question is not only:
It is:
“How much can ₹2 crore support over the full retirement period?”
How Much Can ₹2 Crore Support Over 20, 30 or 40 Years?
Let us use one simplified retirement scenario.
Assume:
- Starting corpus: ₹2 crore
- Portfolio return: 8% a year
- Inflation: 5% a year
- Withdrawals happen monthly
- Monthly withdrawals increase by 5% every year
- No pension or other income
- Taxes and investment costs are ignored
Under those assumptions, the approximate starting monthly withdrawal that would use up the corpus over each retirement period is:
These are mathematical illustrations, not guaranteed income figures.
They assume the portfolio earns a steady 8% every year. Real-world investment returns do not behave that way.
Some years may deliver strong returns. Others may be negative. Taxes, investment costs and unexpected expenses can reduce the corpus further.
Now let us put that into more relatable situations.
What Does ₹2 Crore Look Like at Different Spending Levels?
What if you retire with ₹50,000 in monthly expenses?
Suppose you retire around 60, own your home and expect to spend about ₹50,000 a month.
Your initial annual spending is ₹6 lakh, which is 3% of a ₹2 crore corpus.
That puts far less pressure on the portfolio than starting retirement with expenses of ₹1 lakh or ₹1.5 lakh a month.
If you also receive a pension or rental income, the amount the portfolio needs to provide can fall further.
Inflation, healthcare and investment performance still matter, but your starting withdrawal requirement is relatively low.
What if you need ₹1 lakh a month?
Now annual spending starts at ₹12 lakh.
That is 6% of the ₹2 crore corpus in the first year.
If retirement lasts several decades, the portfolio has to support not only today's ₹1 lakh requirement but increasingly higher expenses over time.
The margin available for unexpected expenses or weaker investment returns therefore becomes smaller.
What if you need ₹1.5 lakh a month?
Now your initial annual expense is ₹18 lakh.
That is already 9% of the ₹2 crore corpus in the first year.
And if those expenses rise by 5% annually, ₹1.5 lakh a month becomes approximately ₹2.44 lakh after 10 years.
The issue is therefore not whether ₹2 crore can pay ₹1.5 lakh next month.
It clearly can.
The question is whether it can continue supporting that lifestyle as expenses rise for 20, 30 or even 40 years.
Other Income Can Completely Change the Calculation
Your retirement corpus may not have to fund your entire lifestyle.
Suppose your monthly expenses are ₹1 lakh.
The lifestyle expense is ₹1 lakh in all three examples.
But the pressure on the ₹2 crore corpus is very different.
That is why pension, rent and other dependable income sources should be included before deciding whether your corpus is enough.
What Else Can Make ₹2 Crore Feel Like More or Less?
The same ₹2 crore can lead to very different retirement outcomes depending on the life built around it.
A paid-off home can make a big difference
Someone who owns their home outright does not need to fund rent or a home-loan EMI every month.
That can substantially reduce the income required from the retirement corpus.
Major goals may still be competing for the same money
Suppose you have ₹2 crore but ₹30 lakh is meant for your child's higher education.
It is closer to ₹1.7 crore.
The same applies to money earmarked for children's weddings, property purchases, large family commitments or other major goals.
Healthcare needs its own place in the plan
Healthcare expenses can be difficult to predict over a long retirement.
Your plan may need to account for:
- Health insurance premiums
- Regular medical expenses
- Expenses not covered by insurance
- Emergency medical needs
- Potential long-term care
If part of your ₹2 crore needs to remain reserved for healthcare, that amount may not be fully available to fund regular monthly expenses.
Lifestyle matters
Travel, family support, hobbies, dining out and other discretionary expenses can make a large difference to annual spending.
Two households with exactly the same ₹2 crore corpus can therefore require very different retirement plans.
Your investment strategy matters too
Your retirement portfolio may need to perform two jobs at the same time:
Keeping sufficient money available for near-term expenses can reduce the need to sell long-term investments during a weak market.
At the same time, putting the entire corpus into very low-growth assets can create another problem if inflation steadily reduces purchasing power over a long retirement.
The right mix depends on your individual situation and risk profile.
So, How Should You Judge Whether ₹2 Crore Is Enough?
Instead of labelling ₹2 crore as “enough” or “not enough”, look at how much work the corpus needs to do.
Here are four simple examples:
| Monthly lifestyle expense | Other monthly income | Amount needed from ₹2 crore | First-year withdrawal from corpus |
|---|---|---|---|
| ₹50,000 | ₹0 | ₹50,000 | 3% |
| ₹75,000 | ₹0 | ₹75,000 | 4.5% |
| ₹1 lakh | ₹30,000 | ₹70,000 | 4.2% |
| ₹1.5 lakh | ₹0 | ₹1.5 lakh | 9% |
This still does not tell you, by itself, whether a particular withdrawal is sustainable.
You also need to ask:
Once you have these answers, ₹2 crore becomes much easier to evaluate.
The Bigger Mistake Is Choosing a Round Number First
₹1 crore.
₹2 crore.
₹5 crore.
These numbers can become retirement targets simply because they sound substantial.
But your retirement requirement does not know that ₹2 crore is a nice round number.
It depends on the life the money needs to fund.
The better approach is to start with the life you expect to live after retirement, estimate how much it will cost, account for inflation and longevity, add other income and then calculate the corpus you actually need.
Want to Know What Your Number Is?
A ₹2 crore target may be more than you need, less than you need or reasonably close.
Use the Retirement CalculatorThe Retirement Calculator can help estimate your retirement corpus using your expenses, retirement age, income streams, inflation, expected returns, retirement duration, emergency and healthcare reserve and other assumptions.
Your retirement number should fit your life, not the other way around.
For a broader retirement strategy, you can also explore Finnovate's Retirement Planning approach, which looks at both corpus estimation and how retirement income may be planned after you stop working.