How to Manage Retirement Income During a Bear Market
Finnovate’s editorial team researches and creates financial content using trusted sources, regulatory references and inputs from subject experts.
When an equity fund loses 30% of its value, a salaried investor may be able to leave it alone and wait for the market to recover. A retiree who depends on that fund to pay household bills may not have the same choice.
The electricity bill is still due. Groceries still need to be bought. Medical expenses cannot always wait for better market conditions.
And when money is withdrawn from a falling investment, more units must be sold to generate the same income. Those units are no longer available to benefit when markets eventually recover.
This is what makes a bear market particularly difficult during retirement. A retirement corpus must fund today's expenses while preserving enough wealth for another 20 or 30 years.
The challenge isn't simply surviving a market crash. It's making sure that regular withdrawals don't turn a temporary decline in investment value into a lasting problem for retirement income.
How should you manage retirement income during a bear market?
First, calculate the monthly spending that dependable income, such as a pension, does not cover. Then identify accessible money for upcoming withdrawals and review which investments your SWP or other redemptions are drawing from. Consider whether flexible expenses can be reduced, and check that the remaining portfolio still suits your long-term needs. There is no single cash reserve or withdrawal rate that works for every retiree.
What happens to a ₹1.5 crore retirement corpus when markets fall?
Consider a 62-year-old retiree with investments worth ₹1.5 crore.
The household spends ₹70,000 a month. A pension provides ₹20,000, leaving ₹50,000 to come from investments.
That means the retirement corpus needs to provide ₹6 lakh every year.
Suppose the portfolio is invested as follows:
| Investment | Before market fall | After market fall |
|---|---|---|
| Equity mutual funds | ₹90 lakh | ₹63 lakh |
| FDs and other relatively low-risk investments | ₹48 lakh | ₹48 lakh |
| Cash and accessible savings | ₹12 lakh | ₹12 lakh |
| Total retirement corpus | ₹1.50 crore | ₹1.23 crore |
Illustrative scenario: Equity investments fall 30% immediately, while other holdings remain unchanged. Figures exclude investment income, taxes and withdrawals. Actual debt investments may also fluctuate in value.
Only the equity allocation falls in this illustrative scenario. Other assets are held constant.
Although equities have fallen 30%, the overall retirement portfolio has declined 18%, from ₹1.5 crore to ₹1.23 crore.
But here's the problem.
The household still needs ₹50,000 every month.
Before the market decline, annual withdrawals of ₹6 lakh represented 4% of the corpus.
After the decline, the same ₹6 lakh represents approximately 4.88% of the remaining corpus.
Nothing about the retiree's lifestyle has changed. Yet the portfolio must now support the same spending with fewer assets.
Neither percentage automatically tells us whether the corpus will last. These figures are simply the annual withdrawal requirement divided by the portfolio's value at each point, not independently calculated sustainable withdrawal rates.
That distinction is important because the popular 4% retirement withdrawal rule originated from historical US market studies. It is not a guaranteed safe withdrawal rate for an Indian retiree.
The real concern is what happens if market losses occur when withdrawals are already underway.
Financial researchers call this sequence-of-returns risk. Finnovate's separate guide to sequence-of-returns risk in retirement shows how identical returns in a different order can lead to very different outcomes.
Two portfolios can earn similar average long-term returns and still produce very different retirement outcomes if one suffers substantial losses during the early withdrawal years. Retirement research on withdrawal sequencing examines this problem in detail.
A younger investor with regular salary income can often avoid selling investments during a downturn. A retiree may have to keep withdrawing, leaving fewer invested units to participate in the eventual recovery.
And the effect becomes particularly visible when retirement income comes through a Systematic Withdrawal Plan.
Your SWP may still pay ₹50,000. But what happens behind the scenes?
A Systematic Withdrawal Plan (SWP) allows investors to withdraw money from a mutual fund at regular intervals.
It can be convenient during retirement because money is transferred to the investor's bank account without requiring a fresh redemption request every month.
But an SWP is not an income-generating product in itself.
It is a method of withdrawing money by redeeming mutual fund units.
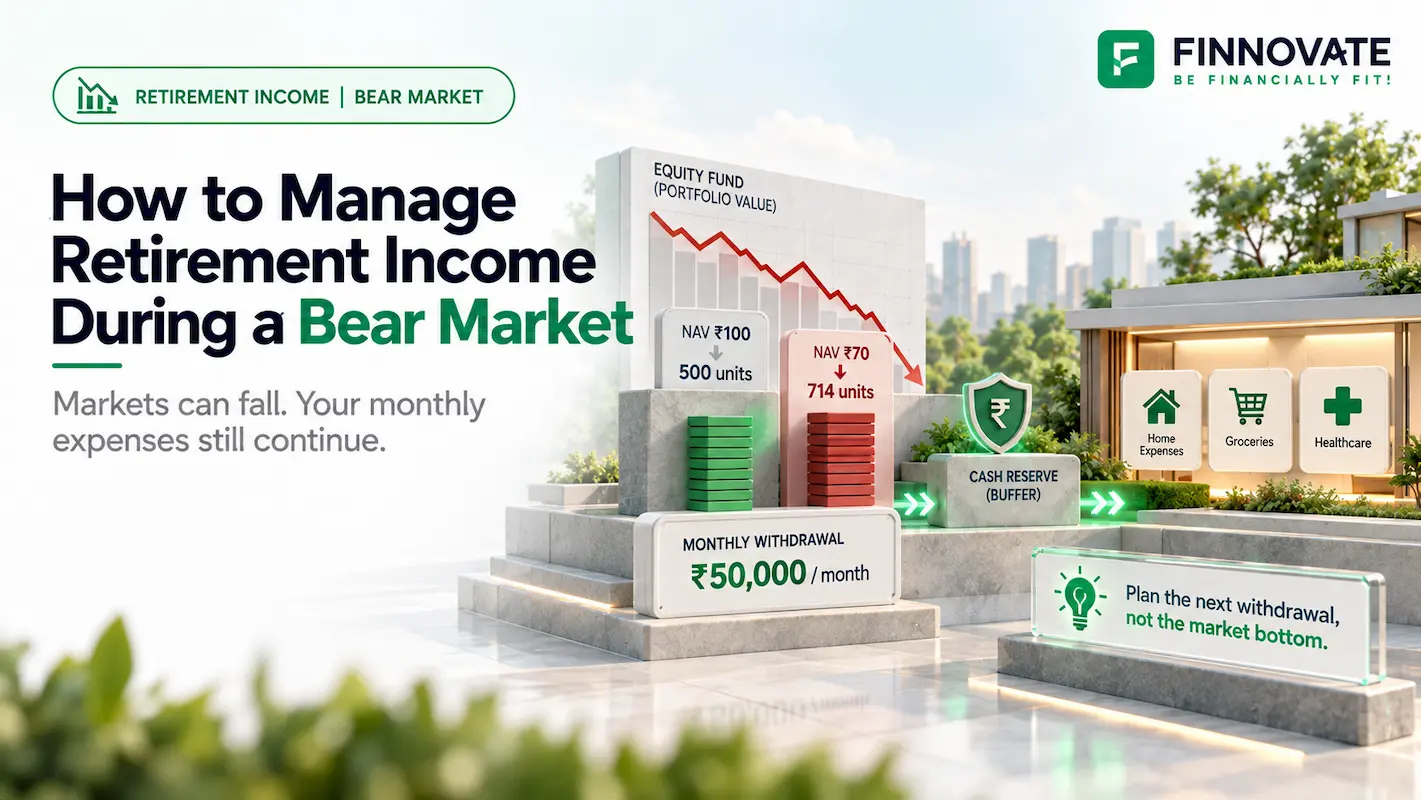
And when the fund's Net Asset Value (NAV) falls, the number of units needed for the same withdrawal increases.
Consider a simplified example.
Suppose an equity mutual fund has an NAV of ₹100.
To withdraw ₹50,000, the investor must redeem 500 units.
Now assume the NAV falls 30% to ₹70.
The same ₹50,000 withdrawal requires approximately 714.29 units.
A lower NAV means a fixed SWP amount uses more mutual fund units.
The bank account still receives ₹50,000. But the number of mutual fund units remaining in the portfolio is falling faster at the lower NAV.
If the market later recovers, units already redeemed cannot benefit from that recovery.
This doesn't mean every SWP becomes unsuitable during a bear market. The long-term impact depends on the fund, withdrawal amount, remaining assets and future returns. A suitably structured withdrawal from a lower-volatility investment can still serve a retirement income plan.
But a regular monthly credit should never be mistaken for proof that an investment is generating enough returns to support it.
A retiree should look beyond the SWP amount and examine the underlying fund, units redeemed and remaining portfolio value. AMFI explains how NAV and redemption pricing work.
Finnovate's SWP Calculator with Inflation can help you compare withdrawals and corpus duration under different assumptions. It uses a constant assumed return, however, so it cannot show every possible sequence of real market gains and losses.
Which brings us to the more immediate problem.
If markets have already fallen, where should next month's ₹50,000 come from?
What should you do if the bear market has already started?
Building a retirement income plan before a market crash gives investors more options.
But someone who has already retired may not have that luxury. Their investments may already be down, and the next month's expenses are approaching.
At this stage, moving everything into safer investments can be as problematic as continuing withdrawals without reviewing the portfolio.
The starting point should be the household's actual cash requirements.
Take our retiree who spends ₹70,000 each month.
The pension covers ₹20,000. Another ₹50,000 must come from investments.
Before deciding what to sell, the retiree needs to examine the money available over the next 12 months.
Does an FD mature in three months? Is there sufficient money in the savings account? Are there interest payments or other dependable receipts due? Is the existing SWP withdrawing from equities or a relatively lower-volatility fund?
These details matter more than a prediction about when the market might recover.
The same household example, expressed as a funding decision rather than a market prediction.
The appropriate first step also depends on the retiree's situation:
| Situation | What to review first |
|---|---|
| An SWP is redeeming equity fund units after a steep fall | Whether accessible cash, scheduled receipts or other suitable assets can meet the next few withdrawals without upsetting the overall allocation |
| The pension covers most essential expenses | The smaller balance that must come from investments before sizing a withdrawal reserve |
| Cash reserves are being used up | Deposit maturity dates, a realistic replenishment plan and whether selling another investment will create new risks |
| The withdrawal requirement is rising relative to the corpus | Discretionary spending, the planned withdrawal amount and a fresh sustainability test |
There is no automatic order in which everyone should sell assets. A more detailed SWP versus FD comparison for retirement income can help when choosing between these sources.
For instance, if an accessible deposit is due to mature shortly, it may be possible to use those proceeds for expenses instead of immediately selling depressed equity investments.
If there are no accessible reserves or dependable income sources, some sale of market-linked assets may be unavoidable. That is not automatically a poor financial decision. Essential household spending still needs to be funded.
The question is which available source best fits the retiree's immediate needs and longer-term portfolio.
Taxes also matter.
A mutual fund may be down from its recent market peak while the units being redeemed still carry taxable capital gains relative to their original purchase cost.
For withdrawals made in Tax Year 2026–27, Section 198 of the Income-tax Act, 2025 provides for 12.5% tax on aggregate qualifying long-term capital gains exceeding ₹1.25 lakh, subject to the applicable conditions, surcharge and cess. Other rules apply to short-term gains and different fund categories.
Importantly, the entire SWP withdrawal is not automatically taxable as capital gains. The tax calculation depends on the gain or loss associated with the units redeemed and the applicable provisions. For a more detailed explanation of redemptions and taxable gains, see how SWP taxation works in India.
Exit loads, liquidity restrictions and the time needed to receive redemption proceeds can also affect the decision.
Rather than immediately stopping every SWP or selling investments simply because markets have fallen, the retiree needs a funding plan for upcoming expenses.
One useful part of that plan is a reserve that doesn't depend on equity market recovery.
Can a cash reserve protect retirement income during a crash?
Return to the ₹1.5 crore portfolio.
It included ₹12 lakh in cash and accessible savings before the market decline.
Since the pension covers ₹20,000 of household spending, the investments need to provide ₹50,000 per month.
That ₹12 lakh reserve could theoretically fund 24 months of the investment-funded shortfall, assuming no interest, inflation, taxes or competing use of the money.
Now suppose equity investments have already fallen from ₹90 lakh to ₹63 lakh.
The retiree has two possible ways to fund the next 12 months of withdrawals.
One option is to sell ₹6 lakh worth of equity fund units.
The other is to withdraw ₹6 lakh from the cash reserve and leave the equity investments untouched.
If equity prices remain unchanged throughout that year, the outcomes would look like this:
| After 12 months | Withdraw from equity | Withdraw from cash |
|---|---|---|
| Equity investments | ₹57 lakh | ₹63 lakh |
| Other lower-risk investments | ₹48 lakh | ₹48 lakh |
| Cash reserves | ₹12 lakh | ₹6 lakh |
| Remaining corpus | ₹1.17 crore | ₹1.17 crore |
Simplified illustration assuming no investment returns, further price changes, inflation, taxes or other portfolio transactions during the period.
Notice something interesting.
Both approaches leave the retiree with the same ₹1.17 crore corpus.
Using cash hasn't created any additional wealth.
What has changed is the amount held in equities versus cash.
If equity markets subsequently recover, the retiree who retained more equity units can benefit more from that recovery.
But if equities decline further, that same investor also has more money exposed to additional losses.
This is why a cash reserve should not be viewed as a guaranteed way to increase retirement returns.
Its main purpose is to give the retiree a planned source of spending money without being forced to sell a particular investment at a difficult time.
There is an important limit, though.
A cash reserve eventually runs out. The money used for withdrawals must be replenished from somewhere, and keeping excessive amounts in cash can reduce long-term growth potential.
Research on retirement bucket strategies has also shown that dividing investments into separate accounts does not automatically improve results. Under certain withdrawal and rebalancing assumptions, bucket strategies can produce the same portfolio outcomes as a conventional diversified portfolio. Michael Kitces' analysis examines these trade-offs.
The real value comes from the allocation, withdrawal and replenishment rules, not simply naming one part of the portfolio a cash bucket.
So how should an Indian retiree decide how much money to keep accessible?
How to structure retirement income without relying on market predictions
The first step is to separate total household spending from the amount that investments actually need to provide.
Someone spending ₹80,000 monthly with a dependable pension of ₹60,000 needs only ₹20,000 from their investments.
Another retiree with the same expenses but no pension needs the entire ₹80,000.
Even if both have identical investment portfolios, their dependence on market performance is very different.
That difference should shape how they structure retirement income.
Cover essential expenses with dependable cash flows where possible
Food, housing, utilities, insurance premiums, routine medical needs and other unavoidable commitments must be funded regardless of what happens in the stock market.
Depending on the person's circumstances, pension income, bank deposits, annuities or suitable government-backed savings schemes may help meet these costs.
The Senior Citizens' Savings Scheme (SCSS), for instance, provides interest payments quarterly rather than monthly. Its principal is subject to scheme rules, including conditions for premature closure.
An FD may pay interest periodically or on maturity. An annuity's payment structure depends on the terms selected. Rental income may be interrupted by vacancies, repairs or delayed payments.
This means a retiree cannot simply add up expected annual income and assume every month's bills are covered.
The timing of income matters almost as much as its amount.
A household spending ₹70,000 every month cannot pay an April bill with interest that will only become available in June unless it has sufficient cash in between.
A practical retirement income plan must account for these mismatches.
Keep accessible money for the shortfall that investments must cover
Once dependable income has been considered, calculate the amount that must be withdrawn from the portfolio.
For our example, that is ₹50,000 per month.
| Reserve period | Amount required |
|---|---|
| 12 months | ₹6 lakh |
| 18 months | ₹9 lakh |
| 24 months | ₹12 lakh |
These are planning scenarios, not a rule that everyone must hold two years of expenses in cash.
The appropriate reserve depends on how much spending is covered by dependable income, the retiree's other accessible investments, health needs, withdrawal flexibility and capacity to tolerate market losses.
The choice of investments for near-term expenses also matters.
Cash, accessible bank deposits and staggered FD maturities may serve different purposes. A debt mutual fund is not equivalent to a guaranteed bank deposit because its NAV can fluctuate with interest rates, credit conditions and liquidity. SEBI's mutual fund Riskometer guidance highlights risks across different categories of funds.
The reserve should be built around money that can actually be accessed when required.
And it is worth distinguishing planned monthly withdrawals from unexpected expenses.
A sudden hospitalisation or major family emergency can create a large cash requirement that has nothing to do with normal retirement spending. An emergency reserve may therefore need to be considered separately. The emergency fund guide for India explains how to think about this separate safety net.
Don't forget the money needed 15 or 20 years later
Holding enough accessible money for the next year is only part of the challenge.
A retiree aged 60 may need investments to last for 25 or 30 years, perhaps longer.
During that period, inflation can substantially increase the cost of living.
A household spending ₹70,000 today will almost certainly need a larger nominal amount in the future if prices continue rising.
A retirement portfolio invested entirely in cash and fixed deposits may limit short-term market fluctuations but still struggle to preserve purchasing power after taxes and inflation.
That is why suitable exposure to growth assets, including equities, can remain relevant after retirement.
The appropriate proportion depends on how much money can genuinely remain invested for the long term without being needed for routine expenses.
The aim is not to avoid every market decline. It is to prevent a decline from disrupting essential household cash flow while retaining a reasonable chance of supporting future spending.
For a broader view of retirement needs over time, Finnovate's Retirement Calculator can help estimate the required corpus using your expenses and planning assumptions. As with any calculator, the output is only an illustration, not a forecast of market returns.
When should retirees rebalance investments or reduce withdrawals?
Market losses change more than portfolio values. They also change the proportion held in different assets.
In our example, equity investments initially represented 60% of the ₹1.5 crore corpus.
After the 30% equity decline, they represented approximately 51% of the remaining ₹1.23 crore.
If the original allocation was suitable for the retiree's needs, the portfolio may need rebalancing.
But rebalancing should follow a predefined plan rather than an attempt to predict the market bottom.
It may involve using maturing deposits, adjusting the assets used for withdrawals or gradually restoring the intended allocation.
However, rebuilding equity exposure should not leave the retiree without enough accessible money for upcoming expenses.
There is another adjustment that often receives less attention: retirement spending itself.
Imagine a household spending ₹80,000 per month, of which ₹60,000 covers essential expenses and ₹20,000 is discretionary.
If the retiree temporarily reduces flexible spending by ₹10,000 a month, annual expenses fall by ₹1.2 lakh.
If this reduction comes entirely from portfolio-funded withdrawals, it directly reduces the amount that must be taken from investments.
That can matter when the portfolio has already suffered losses.
Another option is to postpone an increase in withdrawals when spending is flexible. Suppose a retiree withdraws ₹50,000 a month and planned a 6% annual step-up to ₹53,000. Keeping the withdrawal at ₹50,000 for one more year would leave ₹36,000 invested compared with the planned increase. This is only reasonable if essential expenses can still be met, and it is not a substitute for addressing persistent inflation.
This approach has a basis in retirement research. Financial planners Jonathan Guyton and William Klinger studied withdrawal rules that adjust spending when portfolio conditions change rather than increasing withdrawals automatically every year. Their decision-rules research discusses this approach.
Such strategies can improve resilience in some circumstances, but they also involve accepting lower spending during difficult periods. They are not guarantees against running out of money.
And not every household has room to cut spending.
A retiree whose expenses are dominated by medicines, insurance, housing and basic necessities may have very little flexibility.
In such cases, the investment allocation, available income sources and required withdrawal rate need closer examination.
Spending adjustments and portfolio rebalancing should be treated as parts of the same retirement income plan.
Five checks to make before your next retirement withdrawal
A bear market is an especially important time to review these questions, but they are useful even when equity markets are performing well.
- How much money do investments actually need to provide? Start with monthly household expenses and subtract dependable pension and other reliable cash flows. The remaining amount is the income gap the portfolio must fund.
- Where will that money come from over the next 12–24 months? Check accessible savings, deposit maturities and scheduled payments. This is a liquidity planning exercise, not a requirement to hold a fixed amount in cash.
- Which investments are currently being redeemed? If an SWP is running, identify the underlying fund, number of units redeemed, current balance and how the withdrawals affect the portfolio's allocation.
- How much pressure are withdrawals placing on the remaining corpus? Compare annual withdrawals with the current portfolio value. Test whether the plan remains workable if equities fall further, expenses rise or retirement lasts longer than expected.
- What would trigger a change? Decide in advance when spending increases should be deferred, discretionary expenses reconsidered, cash reserves replenished or the investment allocation reviewed.
These checks can reveal problems that a portfolio statement alone may not show.
A retiree may still have a substantial corpus but face difficulty if almost all accessible money is invested in volatile assets.
Another may have a smaller portfolio but far less dependence on market withdrawals because a reliable pension covers most essential costs.
The size of the corpus matters. So does the way it is used.
The real test of a retirement income plan
A portfolio statement tells a retiree how much their investments are worth on a particular day.
It doesn't tell them which investment should fund next month's electricity bill, whether an SWP is redeeming too many units, or how long accessible reserves might last during a prolonged downturn.
Those questions become much more important when markets fall.
Cash reserves can help avoid unwanted sales. A suitable mix of investments can provide both near-term income and long-term growth. Rebalancing and flexible spending can help the plan respond when conditions change.
None of these steps eliminates investment risk or guarantees that the retirement corpus will last.
But they make the income plan less dependent on a favourable market at precisely the time money is needed.
For someone already retired, perhaps the most useful question is a simple one:
If my equity investments remain down for the next two years, where will the money for my monthly expenses come from?
If the answer is already built into the retirement income plan, the retiree has more choices.
If the answer is to sell whichever investments are available every month, regardless of market conditions, the plan deserves another look.
FAQs
1. Should I stop my SWP during a bear market?
Not automatically. An SWP simply redeems mutual fund units on a schedule. Before changing it, check the underlying fund, monthly amount, remaining corpus and other money available for expenses. If withdrawals are coming from an equity fund that has fallen sharply, consider whether accessible cash or a suitable alternative can cover near-term needs. The decision should also account for exit loads, taxes and your asset allocation.
2. How much cash should a retiree keep during a market crash?
Start with the spending that a pension or other dependable income does not already cover. For example, if investments must provide ₹50,000 a month, ₹6 lakh covers 12 months of that shortfall and ₹12 lakh covers 24 months, before inflation and other demands. These are illustrations, not required cash levels. Medical emergencies, investment liquidity and plans for replenishing the reserve must also be considered.
3. Should I withdraw from FDs or equity mutual funds when markets fall?
There is no universal rule. A maturing FD may be a practical source of near-term income, while selling equities after a fall changes your exposure to any recovery. But breaking an FD early, depleting cash reserves or allowing the equity allocation to drift too far can create other problems. Compare maturity dates, penalties, taxes, liquidity needs and the overall asset allocation before choosing what to redeem.
4. What if the stock market does not recover for two or three years?
A plan that depends on a quick recovery is vulnerable to an extended downturn. Work out which cash flows and accessible assets can cover essential expenses without assuming the market rebounds by a particular date. Review how reserves will be replenished, whether discretionary withdrawals can be reduced and how long the remaining corpus could support spending under weaker returns. A reserve buys time, not a guaranteed recovery.
5. Is the 4% withdrawal rule safe for Indian retirees during a bear market?
The 4% rule comes from historical US retirement research and is not a guaranteed safe rate in India. A suitable withdrawal amount depends on the retiree's age, spending, pension income, investment mix, inflation, taxes and the years the money may need to last. After a market fall, the same rupee withdrawal represents a greater share of a reduced corpus. Test different scenarios rather than relying on 4% alone.
Research and official references
- Kitces: Managing sequence risk with bucket strategies and rebalancing
- AMFI: NAV and redemption price explained
- Income Tax Department: Section 198, Income-tax Act, 2025
- National Savings Institute: Senior Citizens' Savings Scheme rules
- SEBI Investor: Mutual fund Riskometer
- Guyton and Klinger: Retirement spending decision rules