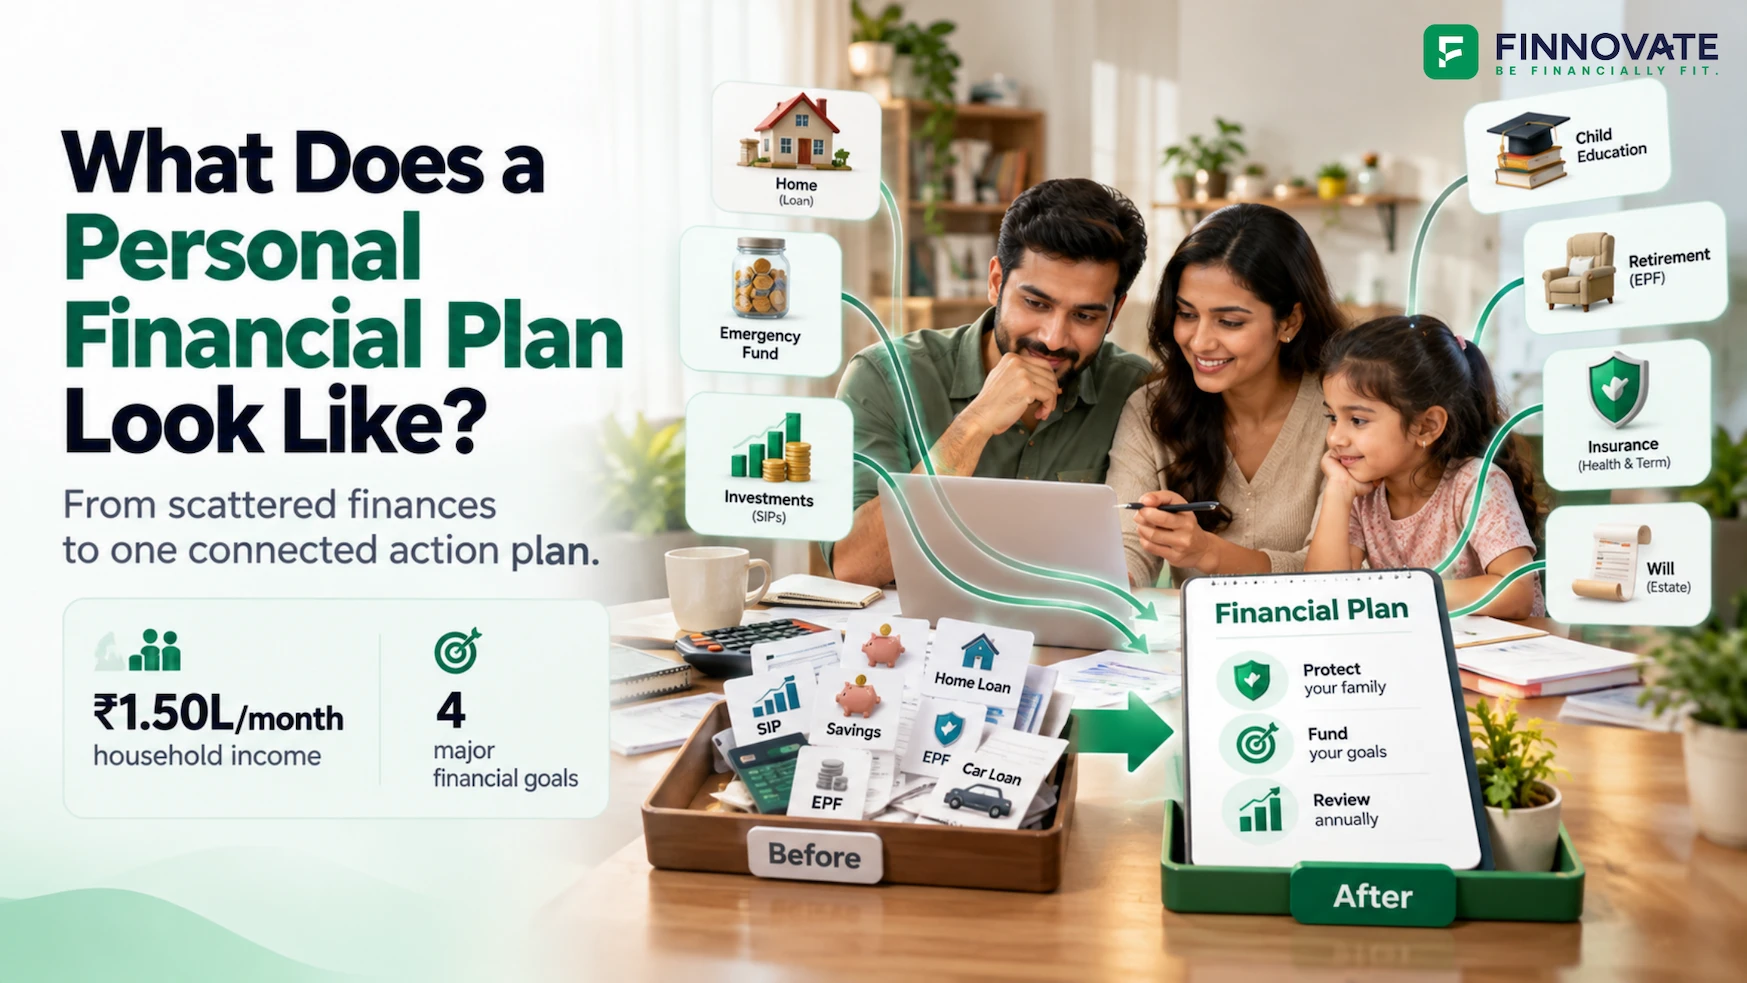
What Does a Personal Financial Plan Look Like? A Complete Example for an Indian Family
Finnovate’s editorial team researches and creates financial content using trusted sources, regulatory references and inputs from subject experts.
A personal financial plan is a written view of your entire financial life. It connects your income, expenses, assets, loans, insurance, investments and future goals, and then tells you what needs to happen first.
It should show what you own and owe, how much of your income is available for future goals, which financial gaps need attention, how much each goal may require and what actions should be taken now, later and during annual reviews.
If you want the broader framework before the worked example, our guide to financial planning in India explains how goals, cash flow, debt, insurance, investments, tax and estate planning fit together.
To see what this looks like in practice, consider a hypothetical Indian family earning ₹1.5 lakh per month.
They already own a home. They have EPF, mutual funds, savings and insurance. They are also paying loans and investing every month.
At first glance, their finances appear reasonably organised.
Once everything is put together, however, several gaps emerge.
Personal Financial Plan Example: Meet the Family
Arjun is 35. His wife Meera is 33. They have a four-year-old daughter.
Their combined monthly take-home income is ₹1,50,000.
Approximately ₹18,000 per month is also being contributed to their EPF accounts through employer and employee contributions. Since their ₹1.5 lakh take-home income is after applicable payroll deductions, we will track this retirement contribution separately rather than treating it as money available for household spending.
| Household detail | Current position |
|---|---|
| Arjun's monthly take-home | ₹95,000 |
| Meera's monthly take-home | ₹55,000 |
| Combined take-home | ₹1,50,000 |
| Combined ongoing EPF contribution | ₹18,000/month |
| Home loan outstanding | ₹29.00 lakh |
| Personal loan outstanding | ₹1.40 lakh |
| Existing mutual fund SIP | ₹12,000/month |
| Employer family health cover | ₹5 lakh |
| Arjun's term cover | ₹50 lakh |
| Meera's term cover | None |
Their major goals are building an emergency reserve, funding their daughter's education, preparing for retirement, reviewing insurance and replacing their car in about five years.
The financial plan now needs to determine which of these goals can be funded, in what order and at what cost.
1. Build the Household Balance Sheet
Before deciding where to invest more money, first establish what the family already owns and owes.
Assets
Liabilities
A ₹43.10 lakh net worth sounds reassuring.
But a financial plan asks a more useful question:
₹55 lakh is tied up in the home they live in.
Unless they intend to sell, downsize or otherwise monetise it, the same home cannot simultaneously fund retirement, education and emergencies.
This is why a household can have a healthy net worth and still have financial-planning gaps.
2. Understand Where the ₹1.5 Lakh Goes Every Month
| Current monthly cash flow | Amount |
|---|---|
| Essential household spending | ₹53,000 |
| Lifestyle and poorly tracked discretionary spending | ₹27,000 |
| Home-loan EMI | ₹29,000 |
| Personal-loan EMI | ₹9,000 |
| Insurance premiums, monthly equivalent | ₹3,000 |
| Mutual fund SIP | ₹12,000 |
| Unallocated surplus | ₹17,000 |
| Total | ₹1,50,000 |
This household is already saving and investing.
The problem is not that nothing is being done. The problem is that the pieces are not connected.
The ₹12,000 SIP is running without a complete retirement calculation. ₹17,000 remains unassigned. ₹9,000 goes towards a personal loan every month. And part of the household's discretionary spending can potentially be reduced without affecting essential expenses.
A financial plan needs to decide what each of these rupees should do.
3. Identify the Gaps Before Selecting Investments
4. Review the Personal Loan Before Investing More
The household currently has ₹4.60 lakh across savings and fixed deposits.
Suppose the ₹1.40 lakh personal loan carries a relatively high interest cost and can be closed without a material prepayment penalty.
Because Arjun and Meera have two incomes and would still retain more than three months of essential outgo after repayment, the plan considers using ₹1.40 lakh of liquid savings to close it.
Their net worth has not increased by even ₹1.
But their financial position has improved because a liability has disappeared and monthly cash flow has improved.
5. Define the Emergency Reserve
After the assumed personal-loan closure, the household has ₹3.20 lakh of liquid savings remaining.
| Essential outgo | Amount |
|---|---|
| Essential household spending | ₹53,000 |
| Home-loan EMI | ₹29,000 |
| Essential insurance provision | ₹3,000 |
| Essential monthly outgo | ₹85,000 |
For this example, Arjun and Meera decide to work towards six months of essential expenses.
This is a scenario chosen for this household, not a universal emergency-fund rule. You can test different coverage periods against your own essential expenses and EMIs using Finnovate's Emergency Fund Calculator.
The plan has converted “we should probably keep more emergency savings” into a measurable action:
6. Calculate the Child's Education Requirement
Their daughter is four years old. Suppose they expect the higher-education expense when she turns 18, giving them 14 years.
They estimate that the education they want to fund would cost ₹20 lakh today.
For illustration, assume the cost increases by 8% per year.
The family also has ₹1.20 lakh in PPF.
For this example, assume the PPF account's maturity and withdrawal timing are compatible with the education goal. This must be checked in a real plan because PPF has its own tenure and withdrawal conditions.
At an illustrative 7% annual accumulation assumption, the ₹1.20 lakh could grow to approximately ₹3.09 lakh in 14 years.
What if the education-cost assumption changes?
| Education-cost increase | Estimated future cost | Approx. monthly investment |
|---|---|---|
| 6% | ₹45.22 lakh | ₹11,600 |
| 8% | ₹58.74 lakh | ₹15,300 |
| 10% | ₹75.95 lakh | ₹20,000 |
The difference between 6% and 10% education-cost inflation changes the required monthly contribution by more than ₹8,000.
This is why a useful financial plan states its assumptions rather than presenting one future number as certain.
7. Check Whether Retirement Is Actually on Track
Arjun and Meera already have EPF and mutual funds.
But having retirement investments is different from knowing whether those investments are enough.
| Illustrative retirement assumption | Value |
|---|---|
| Retirement lifestyle cost today | ₹50,000/month |
| Years until retirement | 25 |
| Inflation before retirement | 6% |
| Retirement period | 30 years |
| Inflation during retirement | 6% |
| Post-retirement return | 7.5% |
| Existing EPF | ₹7.50 lakh |
| Ongoing EPF contribution | ₹18,000/month |
| EPF accumulation assumption | 8% |
| Existing mutual funds | ₹5.20 lakh |
| Current retirement SIP | ₹12,000/month |
| Mutual fund accumulation assumption | 10% |
At 6% inflation, today's ₹50,000 monthly lifestyle becomes approximately ₹2.15 lakh per month after 25 years.
Using a simplified annual growing-withdrawal model across 30 years of retirement, the estimated retirement requirement is approximately:
Under the same assumptions, the total monthly mutual fund investment required towards retirement works out to approximately ₹23,500 per month.
The household is already investing ₹12,000 per month.
So the eventual increase required is approximately ₹11,500 per month. If you want to run the same exercise using your own retirement age, expenses, existing assets and income assumptions, use Finnovate's Retirement Calculator.
8. Rebuild the Monthly Cash Flow
Closing the personal loan releases ₹9,000 per month.
The household also reduces its lifestyle and poorly tracked discretionary spending from ₹27,000 to ₹18,000.
That releases another ₹9,000.
| Revised monthly use of take-home income | Amount |
|---|---|
| Essential household spending | ₹53,000 |
| Lifestyle and discretionary spending | ₹18,000 |
| Home-loan EMI | ₹29,000 |
| Existing insurance provision | ₹3,000 |
| Available for goals and financial priorities | ₹47,000 |
| Total | ₹1,50,000 |
The separate ₹18,000 monthly EPF contribution continues outside this take-home calculation.
9. What If Every Goal Cannot Be Funded at Once?
During the first year, the household needs to close the emergency-fund gap while continuing progress towards long-term goals.
This does not mean ₹23,500 and ₹15,300 should remain unchanged forever.
Salary, expenses, investment values and goal assumptions will change.
The important lesson is:
10. Test the Car Goal Against the Same Cash Flow
The family would also like to replace its car after five years.
Suppose the desired car costs ₹10 lakh today.
At an illustrative 5% annual increase in cost, the future price is about ₹12.76 lakh. At an illustrative 7% return, funding the entire amount through monthly investments would require about ₹17,800 per month.
The gap is roughly ₹9,600 per month.
A realistic plan should therefore say:
The family can postpone the purchase, reduce the budget, use future bonuses, allocate part of future salary increases or partially fund the goal and reassess later.
Sometimes the most useful financial-planning answer is not “invest more”.
It is:
11. Assign Existing Investments to Specific Goals
Before planning, the household had several financial assets.
After planning, each one has a job.
This prevents a common planning mistake.
The same investment cannot be counted towards three different goals at the same time.
The family is also not counting its primary residence towards retirement because there is currently no plan to sell, downsize or monetise it.
12. Insurance Has to Be Reviewed Before the Plan Is Complete
Arjun has ₹50 lakh of term insurance.
Meera currently has none.
The family also relies primarily on ₹5 lakh of employer-provided health insurance.
A complete financial plan should not automatically prescribe a generic insurance multiple.
13. Tax and Estate Planning Belong in the Same Plan
Tax planning should be reviewed each financial year based on the income of both spouses, applicable tax regime, employer benefits and investments actually required for their goals.
The objective should not be to buy an unnecessary product merely because it provides a tax deduction.
Estate planning also becomes important because the household has a home, investments, insurance, outstanding liabilities and a young child.
The family should review nominations across bank accounts, investments, EPF and insurance, and consider whether appropriate Will and estate documentation is required. Families with property, investments, minor children or outdated nominations can go deeper into estate planning for investors and families in India.
Goals → cash flow → loans → emergency reserve → insurance → investments → taxation → estate planning
What Would Their Written Financial Plan Actually Say?
After all the calculations, Arjun and Meera do not need another list of financial concepts.
They need an action plan.
That is what a personal financial plan looks like in practice.
It establishes an order.
Before and After the Financial Plan
| Area | Before the plan | After the plan |
|---|---|---|
| Personal loan | ₹1.40L outstanding | Closure considered after checking terms and liquidity |
| Liquid money | ₹4.60L with no clear assignment | ₹3.20L emergency-ready after assumed debt closure, with ₹5.10L target |
| Monthly financial capacity | ₹12K SIP + ₹17K unassigned surplus | ₹47K organised after debt and spending changes |
| Mutual funds | Existing but not fully goal-mapped | Assigned to retirement |
| PPF | Existing asset | Education allocation only if timing matches |
| Child education | No quantified requirement | ₹58.74L illustrative future requirement |
| Education contribution | No defined number | ~₹15.3K/month under assumptions |
| Retirement | EPF + SIP assumed to be sufficient | ₹5.91Cr required vs ~₹4.38Cr projected |
| Retirement SIP | ₹12K/month | Eventually ~₹23.5K/month under assumptions |
| Car | Desired in five years | Current plan cannot fully fund desired amount and timeline |
| Insurance | Existing policies | Formal adequacy review |
| Estate planning | Not coordinated | Nominee and Will review |
| Review process | Ad hoc | Annual plus event-triggered |
The household's income has not changed.
Its net worth has not suddenly doubled.
But the organisation of its finances has changed significantly.
The example above shows why the useful part of financial planning is not a generic allocation. It is connecting your actual goals, loans, cash flow, insurance, investments, tax and estate considerations into one written action plan. Finnovate's financial planning advisory is built around that complete household picture.
Check Your Own Starting Point
If you are not ready for a full plan yet, use these guides and tools to quantify the individual parts of your financial life first. The links above are also placed contextually through the case study where each decision becomes relevant.
Assumptions Used in This Personal Financial Plan Example
| Assumption | Illustrative value |
|---|---|
| General inflation | 6% p.a. |
| Education-cost increase | 8% p.a. |
| Education investment return | 10% p.a. |
| PPF planning assumption | 7% p.a. |
| EPF planning assumption | 8% p.a. |
| Retirement mutual fund return | 10% p.a. |
| Inflation during retirement | 6% p.a. |
| Post-retirement return | 7.5% p.a. |
| Retirement period | 30 years |
| Car-cost increase | 5% p.a. |
| Car-goal investment return | 7% p.a. |
The PPF illustration assumes the account can be accessed when the education goal falls due. Actual PPF maturity and withdrawal conditions should be checked before assigning it to a goal.
The retirement requirement uses a simplified annual growing-withdrawal calculation. Actual retirement planning may need to account separately for cash-flow timing, taxation, healthcare, changes in expenses, retirement income and longevity.
All return and inflation figures are assumptions for illustration. Actual investment returns, inflation, EPF/PPF rates, taxes, insurance costs and household expenses can differ. Investment returns are not guaranteed.
FAQs
1. What should a personal financial plan include?
A personal financial plan should normally include your assets, liabilities, monthly cash flow, emergency reserve, insurance needs, future goals, existing investments, goal shortfalls, required monthly contributions, tax considerations and estate-planning actions.
2. Is a financial plan the same as an investment plan?
No. An investment plan mainly deals with how money is invested. A personal financial plan is broader and also considers cash flow, debt, insurance, emergency savings, taxes, estate planning and the order in which competing goals should be funded.
3. Do you need a high income to make a financial plan?
No. Financial planning is fundamentally about allocating limited resources between competing priorities. Higher income can make funding goals easier, but the need to prioritise and make trade-offs exists at different income levels.
4. How often should a financial plan be reviewed?
An annual review is a useful checkpoint. The plan should also be revisited after major changes such as marriage, childbirth, a significant salary change, career move, new loan, home purchase, inheritance or material change in an important financial goal.
5. Can you make a personal financial plan yourself?
You can begin by preparing your household balance sheet, tracking cash flow, listing goals and calculating the gaps. Individual calculators can also help quantify emergency savings and retirement needs. The challenge increases when decisions interact, because paying off debt, changing insurance, increasing investments or adding a new goal can affect the entire plan.
6. Why are assumptions important in a financial plan?
Goal calculations depend heavily on assumptions such as inflation, investment returns, time horizon and retirement duration. A useful plan should disclose these assumptions and review them periodically instead of treating one future number as guaranteed.