Home, Child Education and Retirement: How Do You Plan All Three With One Income?
Finnovate’s editorial team researches and creates financial content using trusted sources, regulatory references and inputs from subject experts.
A home, your child's education and retirement can all feel equally important.
The problem is that all three may arrive at very different times, require very different amounts of money and depend on the same monthly salary.
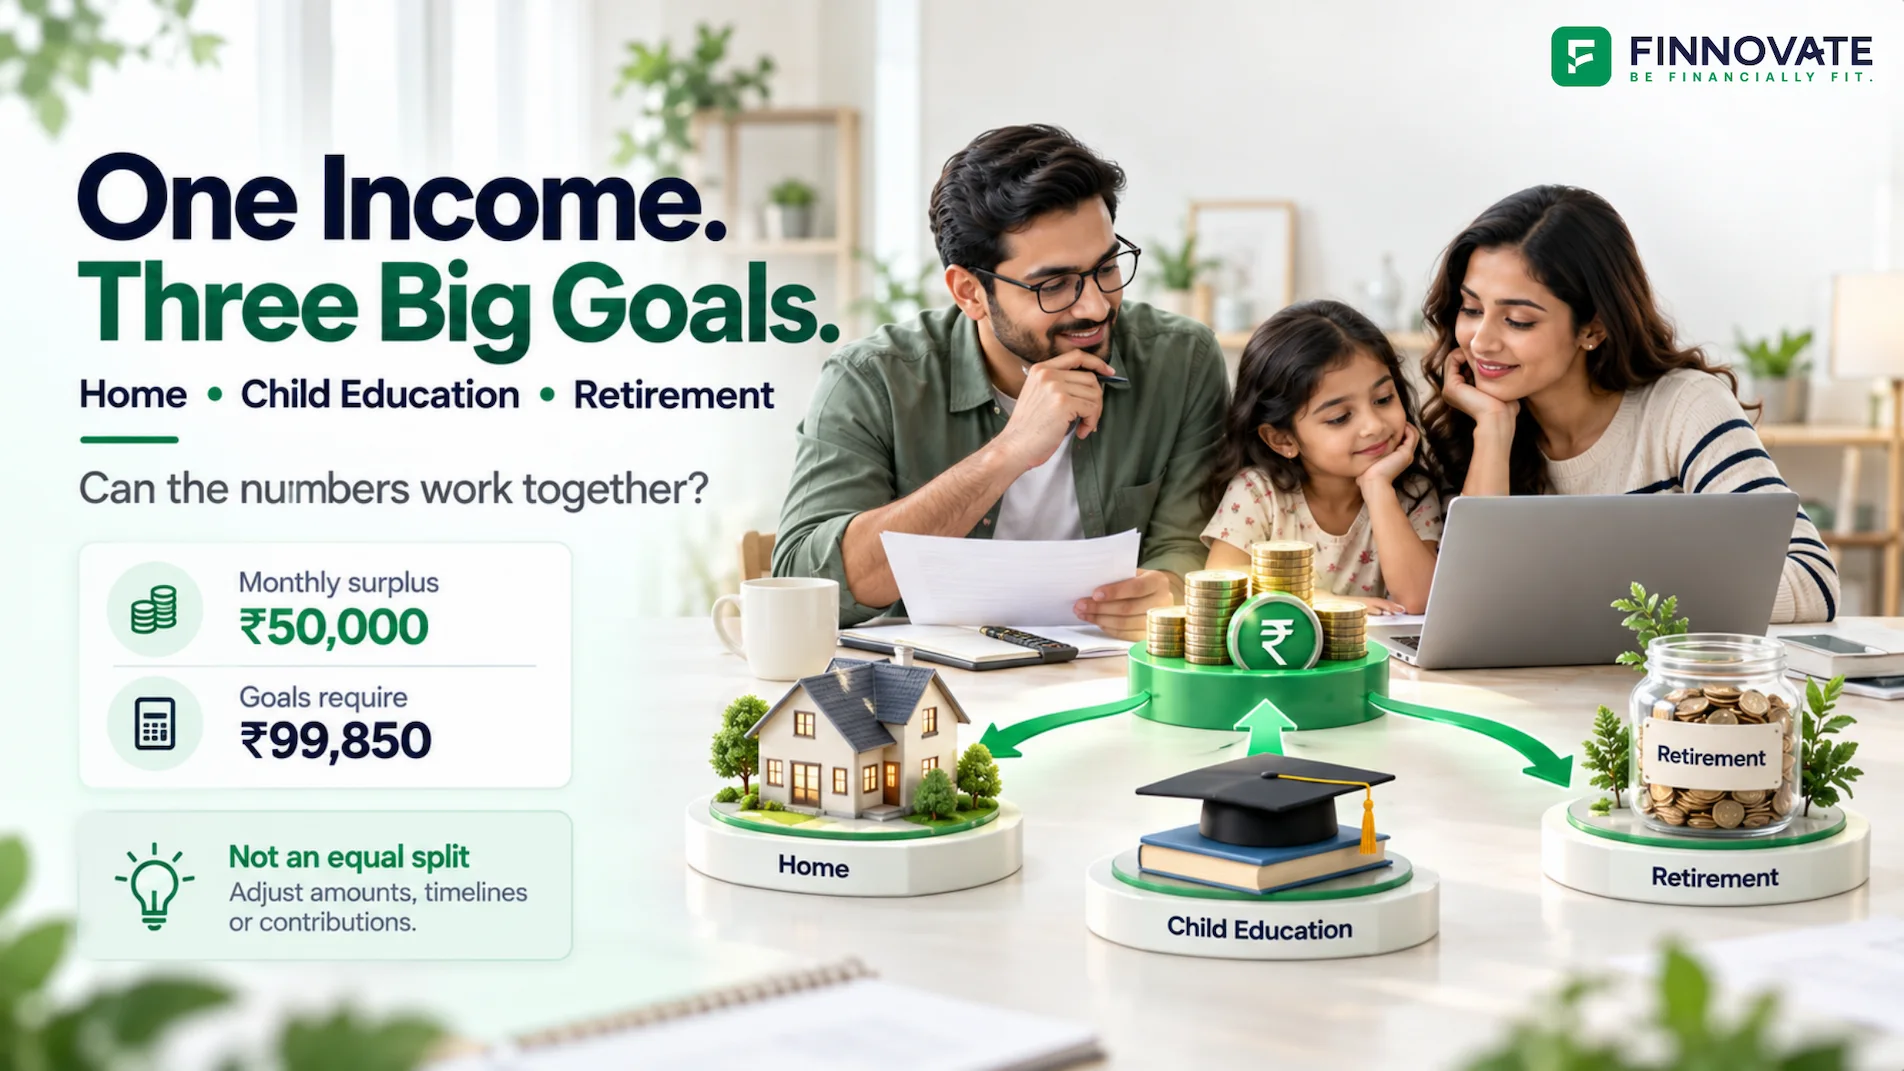
So what happens when the maths says your family needs to invest almost ₹1 lakh every month, but the household can save only ₹50,000?
Calculate what the home, education and retirement goals each require first. Add those monthly requirements together and compare the result with the amount your household can actually save.
If the numbers do not fit, test the variables that can realistically move, such as the home-purchase date, annual contribution increases, the amount you plan to fund for education or your retirement age.
There is no universal rule that says retirement must always come first, education second and the home third.
The useful question is:
Start With the Household's Actual Monthly Surplus
Consider a family with one income.
For this example, assume the household has already addressed its essential insurance needs and emergency reserve.
If that foundation is still incomplete, see Finnovate's Emergency Fund guide before committing the entire surplus to long-term goals.
Now let us put an amount and a date against each of the three goals.
Goal 1: How Much Will the Home Down Payment Require?
Suppose the family wants to build a down payment worth ₹20 lakh in today's money and buy the house five years from now.
Under these assumptions, the family is not really saving towards a ₹20 lakh target.
Five years from now, the required amount is approximately ₹25.53 lakh.
To build that amount over five years, the required monthly contribution is approximately:
That one goal alone uses more than 70% of the family's ₹50,000 monthly surplus.
You can model a different target, timeline, inflation assumption, existing savings and annual contribution increase using Finnovate's Goal SIP Calculator .
But building the down payment is only one part of the home decision. The EMI that begins after the purchase can alter the funding capacity for the other two goals.
Goal 2: What Could the Child's Higher Education Cost?
The child is five years old. Suppose the parents want to provide ₹25 lakh in today's money for higher education at around age 18.
The ₹25 lakh education goal has therefore become an approximately ₹68 lakh future requirement.
The monthly contribution required under these assumptions is approximately:
The 8% education-cost increase used here is an illustrative planning assumption, not a prediction of what every college or course will cost.
Actual costs can vary widely depending on the course, institution, location, country, living expenses and currency.
Parents can model their own numbers using Finnovate's Child Education Planning Calculator .
Goal 3: How Much Does the Family Need for Retirement?
Retirement requires a different calculation because the corpus has to support years of future expenses rather than one payment on one date.
Suppose that out of the family's current ₹1 lakh monthly household outgo, ₹60,000 represents lifestyle expenses expected to continue in retirement.
That is approximately ₹30.9 lakh of spending in the first retirement year.
If retirement expenses then grow by 6% annually and the retirement corpus earns an illustrative 7% annually, a 30-year growing-withdrawal calculation gives an estimated required corpus of approximately:
The family already has ₹15 lakh earmarked for retirement.
Assuming the existing retirement investment and future monthly contributions earn an illustrative 10% annually during the accumulation period, the additional monthly contribution required is approximately:
These figures are model outputs based on the assumptions above, not guaranteed future returns or expenses.
Finnovate's Retirement Calculator can model household expenses, retirement age, planning age, existing assets, pension or other income, inflation and post-retirement returns together.
What Happens When You Add All Three Goals?
Now bring the three calculations together.
| Goal | Future requirement | Approx. monthly contribution |
|---|---|---|
| Home down payment | ₹25.53 lakh in 5 years | ₹35,450 |
| Child's education | ₹67.99 lakh in 13 years | ₹21,200 |
| Retirement | ₹7.59 crore at age 60 | ₹43,200 |
| Total monthly requirement | ₹99,850 | |
| Actual monthly surplus | ₹50,000 | |
| Monthly funding gap | ₹49,850 | |
Changing mutual funds or choosing a higher expected return does not automatically solve this problem.
Nor does splitting the ₹50,000 equally.
Why an equal split can still leave all three goals underfunded
If the family divides ₹50,000 equally, each goal receives roughly ₹16,667 per month.
But the calculations require approximately:
- ₹35,450 for the home
- ₹21,200 for education
- ₹43,200 for retirement
Everything receives money, but nothing is fully funded.
For the wider framework behind this approach, read Finnovate's Goal-Based Financial Planning guide .
Trade-Off 1: What If the Family Delays the House Purchase?
The first home target is five years away.
Suppose the family is willing to buy after eight years instead.
The target does not remain ₹25.53 lakh because the assumed down-payment requirement continues to rise at 5% annually.
Delaying the home frees approximately:
But that saving has a cost: the family waits another three years to buy the house and faces a higher future down-payment target.
This is why the decision should be treated as a trade-off, not a universal instruction to postpone the home.
Trade-Off 2: What If Contributions Increase as Income Grows?
The earlier calculations assume the same monthly investment for the entire goal period.
Some salaried households may instead be able to increase contributions over time.
Suppose this family increases each goal contribution by 10% every year.
| Goal | Flat monthly contribution | Starting monthly contribution with 10% annual step-up |
|---|---|---|
| Home in 5 years | ₹35,450 | ₹29,400 |
| Education in 13 years | ₹21,200 | ₹12,800 |
| Retirement in 25 years | ₹43,200 | ₹17,600 |
| Total | ₹99,850 | ₹59,800 |
The starting requirement falls substantially.
But a step-up does not make the goals cheaper.
A 10% annual increase works only if future salary growth and household cash flow can support the larger contributions.
The Goal SIP Calculator can model annual contribution step-ups rather than assuming a flat SIP.
What if the family combines both changes?
Now suppose the family:
- delays the home from 5 years to 8 years, and
- uses a 10% annual contribution step-up.
The approximate starting contributions become:
| Goal | Starting monthly contribution |
|---|---|
| Home in 8 years | ₹16,600 |
| Child education | ₹12,800 |
| Retirement | ₹17,600 |
| Total in Year 1 | ₹47,000 |
For the first time, the plan fits within the family's existing ₹50,000 monthly surplus.
There is approximately ₹3,000 of initial headroom.
The plan therefore works only if the family's investible surplus rises enough over time.
At the end of the home accumulation period, that contribution stops. But if the house is financed, a home-loan EMI may begin in its place.
Trade-Off 3: What If the Family Adjusts the Education Goal?
Some goals have flexibility in how much the family promises to fund.
Suppose the parents reduce their own education-funding target from ₹25 lakh in today's money to ₹20 lakh.
That frees approximately:
But again, the money has not appeared for free.
The family is committing to fund a smaller portion of the eventual education cost.
The remaining amount may eventually need to come from a scholarship, education loan, the child's own contribution, another family resource or a lower-cost course or institution.
Trade-Off 4: What If Retirement Moves From 60 to 62?
Retirement is often described as completely non-negotiable.
In practice, some households may be willing to test a later retirement age.
Suppose this family considers retirement at 62 instead of 60.
The retirement corpus is actually larger at age 62 because the same lifestyle experiences two more years of inflation.
But the monthly contribution required today falls because the family gets:
- two additional earning years,
- two more years for existing retirement assets to compound,
- two more years of contributions, and
- two fewer retirement years to fund if the planning age remains 90.
The current monthly requirement falls by approximately:
The financial burden today is lower. The lifestyle trade-off is working two years longer.
Which Financial Goals Can Actually Be Adjusted?
Instead of ranking goals through one universal priority list, test three kinds of flexibility.
Don't Forget What Happens After You Buy the House
The down payment is only the first half of the home decision.
So the family has to test two separate questions:
- Can we build the down payment?
- Can we still fund education and retirement after the EMI begins?
These are not the same affordability test.
Finnovate's guide to how much home-loan EMI you can actually afford explains why a bank's loan eligibility and a household's financial-plan affordability can be very different numbers.
You can also use the Home Affordability Calculator to test income, property value, tenure, existing EMIs and home-loan affordability.
If the down payment may come from an existing portfolio, see Should I Redeem My Mutual Funds for a Home Down Payment? before using investments already assigned to another goal.
Should All Three Goals Use the Same Investment Strategy?
No.
The three goals have very different timelines.
The investment approach should therefore follow:
rather than putting every goal into one portfolio simply because all the investments come from the same salary.
This article does not prescribe one equity-debt allocation for each goal. The appropriate mix depends on the family's risk profile, existing assets, tax position and the time remaining.
What If the Required Amount Still Does Not Fit?
If the plan still needs more money than the family can save, work through the variables rather than forcing the calculation.
Check whether:
- the goal amounts are realistic,
- one or more timelines can move,
- contributions can increase as income grows,
- existing investments are genuinely available for a specific goal,
- part of a flexible goal can use another funding source,
- retirement age or retirement lifestyle assumptions can reasonably change, and
- the future home EMI still leaves enough room for the other goals.
A higher return assumption reduces the required SIP mathematically. It does not make that return more likely to occur.
A Simple Framework for Planning Multiple Goals on One Income
So, Can One Income Fund a Home, Child Education and Retirement?
Yes, it can.
But not simply because the family starts three SIPs.
In our example, the household had a ₹50,000 monthly surplus.
Under the original assumptions, the three goals required approximately ₹99,850 per month.
The plan did not fit.
Delaying only the house reduced the pressure but did not eliminate the full gap.
Using only a 10% annual contribution step-up reduced the starting requirement to around ₹59,800, but that was still above the family's current capacity.
Combining a later home purchase with annual contribution increases brought the first-year requirement down to approximately ₹47,000.
That made the plan mathematically possible in Year 1, but only if future income and investible surplus can support the higher contributions that follow.
Tools to model your own numbers
FAQs
1. How should I divide my monthly savings between a home, child's education and retirement?
There is no universal percentage split. Calculate the future amount and monthly contribution required for each goal first, then compare the combined requirement with your available monthly surplus. The allocation should follow those numbers and the flexibility of each goal rather than an arbitrary ratio.
2. Should retirement always come before buying a house?
Not automatically. Retirement requires long-term funding, but that does not mean every household should postpone a home regardless of circumstances. Compare how changing the home's cost or purchase date affects education and retirement funding before deciding.
3. Should I prioritise my child's education over retirement?
Both should be planned together. Education may eventually have alternative funding sources such as scholarships or an education loan, while retirement generally depends more heavily on your own accumulated assets. The appropriate decision depends on the amounts, timelines, existing savings and family preferences.
4. What if I cannot afford the monthly investment required for all my goals?
Test the variables that can reasonably change. This may include the goal amount, deadline, annual contribution increase, retirement age, existing savings or an alternative funding source. Do not simply increase the expected investment return until the required SIP appears affordable.
5. Is a step-up SIP useful when I have multiple goals?
It can be. A step-up contribution starts lower and increases over time, which may suit a household whose income is also expected to rise. But future contributions can become substantially larger, so the step-up should match a realistic salary and cash-flow path.
6. How should I plan for my child's education if I do not know the course yet?
Start with a reasonable current-cost estimate and review it periodically. Update the target as the child's interests, likely institution, country and course become clearer. Starting with an imperfect estimate is generally more useful than waiting until the exact course is known.
7. Should I buy a house if the EMI will force me to stop my retirement contributions?
That deserves a closer affordability review before the purchase. Home affordability should be assessed after allowing for other important goals, emergency reserves and ongoing household expenses, not only against the EMI a lender is willing to approve.
8. How often should a multiple-goal financial plan be reviewed?
Review it at least annually and whenever a major financial event occurs, such as a salary change, home purchase, new loan, another child, material change in education plans or change in retirement age.