Where Does India Keep Its Money?
Finnovate’s editorial team researches and creates financial content using trusted sources, regulatory references and inputs from subject experts.
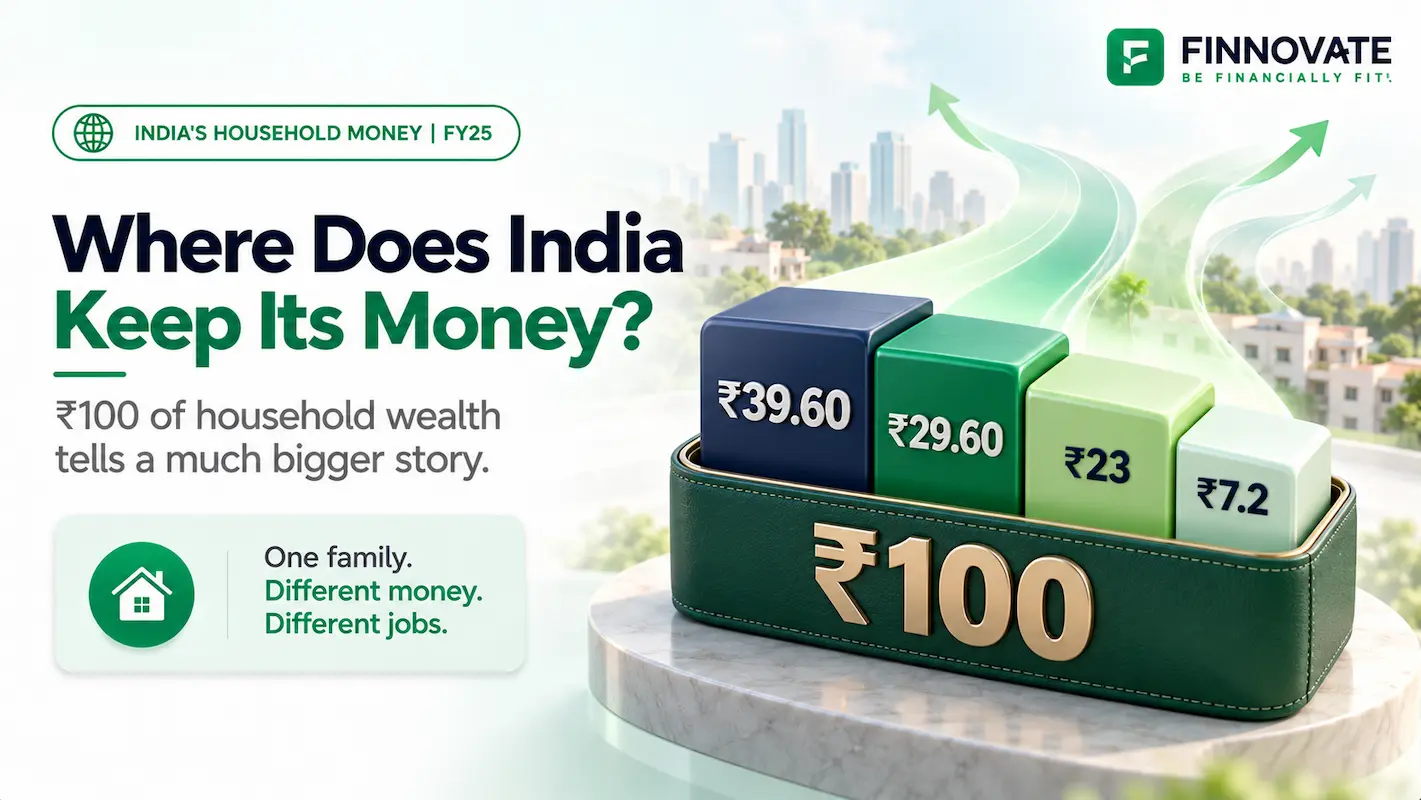
Forget the usual FD-versus-mutual-fund debate for a moment. If all the financial assets owned by Indian households were compressed into just ₹100, where would that money actually sit?
Start with ₹100.
Not ₹100 in your wallet. Imagine ₹100 representing the entire financial asset pool of Indian households.
About ₹39.60 of it would be in deposits.
Another ₹29.60 would sit in insurance and pension funds.
Around ₹23 would be in equity and investment funds. Roughly ₹7.20 would be held as currency. Debt securities would make up only a very small remainder.
That is a very different picture from the one we often see in headlines about SIPs, stocks and demat accounts.
But This Is the Money India Has Already Accumulated
That distinction matters.
The ₹100 above is a snapshot of financial assets already sitting on household balance sheets.
It tells us where the stock of household money is today.
It does not tell us where fresh savings are going.
And that second picture is changing much faster.
Fresh Money Is Behaving Differently
Back in FY12, deposits accounted for 57.9% of annual household financial savings among the selected products tracked in the Economic Survey.
By FY25, that share had fallen to 35.2%.
Shares and mutual funds moved in the opposite direction.
Their share rose from just 1.8% in FY12 to 15.2% in FY25.
Source: Economic Survey 2025-26, Chart III.17 . The chart compares selected products and should not be read as a complete 100% allocation of annual household savings.
This is where the usual story of “Indians are moving from FDs to equities” starts to fall apart.
Something is clearly changing. But households are not simply emptying one bucket and filling another.
In fact, the Economic Survey describes what is happening as portfolio diversification rather than displacement.
The household portfolio increasingly looks less like:
One product replacing another would be the easy story. The data points to something more layered.
And more like:
Different assets can continue to coexist because different parts of household money may have different jobs.
A Big Asset Share Does Not Mean Everybody Owns It
There is another trap hidden inside the numbers.
We just saw that equity and investment funds account for about 23% of aggregate household financial assets.
It would be easy to assume that market participation must therefore be widespread.
It isn't.
SEBI's Investor Survey 2025 estimates that only 9.5% of Indian households participate in securities-market products, even though 63% are aware of at least one such product.
Sources: Economic Survey 2025-26 and SEBI Investor Survey 2025 .
These three questions are related, but they are not interchangeable.
A smaller group of households can hold a meaningful amount of market-linked financial wealth. That is why rising mutual fund assets or equity ownership can coexist with relatively low household participation.
The Real Driver Is Not Return. It Is Responsibility.
So why does such a large part of household money still lean towards products associated with stability?
One SEBI finding gives us a clue.
Read that number on its own and it is tempting to label Indian families “too conservative”.
Now ask what the money is being saved for.
The picture changes.
When households were asked to name their single most important financial goal, children's education came first. Supporting family members came next. Buying a house, growing wealth and building an emergency fund were also among the leading answers.
Source: SEBI Investor Survey 2025, Table 13.1 .
These are not abstract investment goals.
They are school and college fees. Parents who may need support. A house the family hopes to buy. A buffer for the month when something goes wrong.
Once money has a responsibility attached to it, chasing the highest possible return stops being the only consideration.
One Family Can Have Four Completely Different Kinds of Money
Imagine a household setting aside money for four things.
It is one family.
But it has four different deadlines, four different consequences if the money is not available, and four different levels of tolerance for uncertainty.
That is why the same household can reasonably hold both stable and market-linked assets.
Emergency money needs access.
Money required soon may need greater stability.
Money needed decades later faces a different problem: inflation has a long time to increase the cost of the goal.
Insurance solves another problem altogether. Its main role is to protect the household against financial events it may not be able to absorb on its own.
That is the basic idea behind goal-based financial planning .
There Is Another Reason Markets Can Still Feel Far Away
For many households that have not entered securities markets, the hurdle is not simply unwillingness to invest.
SEBI asked non-investor households what holds them back.
Think about what a familiar deposit asks of a saver.
There is an amount, a rate and a maturity date.
Enter the investment market and the menu suddenly becomes much larger: equity funds, debt funds, hybrid funds, index funds, ETFs, direct stocks, bonds, portfolio strategies, tax rules and different levels of market risk.
More choice can be useful.
It can also make it easier to accumulate products without ever building a plan around them.
The Problem Starts When Products Arrive Before Purpose
Consider someone who owns five mutual funds, twenty stocks, two FDs, EPF, NPS, gold and three insurance policies.
That sounds like a fairly developed financial life.
But the number of products tells us almost nothing about whether the household is financially prepared.
A product list cannot answer these questions.
A financial plan asks what that money is supposed to do, when it needs to do it, and whether there will be enough.
That distinction matters more as the number of products available to households keeps increasing.
So Is India Moving Away From FDs?
Not in the simple way the question suggests.
Deposits still account for the largest share of Indian household financial assets.
Insurance and pension assets remain substantial.
At the same time, equity and investment funds have become much more important. Their share of household financial assets increased from 15.7% in FY19 to 23% in FY25.
Fresh financial savings are also being directed towards shares and mutual funds at a much higher rate than they were a decade ago.
All of these things can be true at once.
That is why the better description of India's household money story is not:
It is:
More types of assets are beginning to coexist inside the same financial life.
And when the shelf gets wider, deciding what belongs where becomes more important.
Now Forget India's ₹100. Look at Your Own.
World Financial Planning Day and World Investor Week give us a reason to look at how Indian households save and invest.
But a national average cannot tell you what your ₹100 should look like.
A household planning to buy a home in two years should not copy the portfolio of someone whose next large goal is 20 years away.
A family with dependants may have different protection needs from a retired couple.
Someone with irregular income may need more accessible money than someone with predictable cash flows.
So take your own ₹100 and ask:
What part of it might I need soon?
What part protects my family if something goes wrong?
What part is meant for goals with a fixed date?
What part needs to grow for many years?
And what part is sitting somewhere simply because nobody has asked what job it is doing?
India's investment story is changing.
Good financial planning does not begin by copying where India's money is moving.
It begins by deciding where your money needs to go, and why.
- Household financial-asset composition and annual financial-savings data are from the Economic Survey 2025-26 .
- Household participation, capital-preservation preference, financial goals and non-investor barriers are from the SEBI Investor Survey 2025 .
- Asset shares, savings-flow shares and household participation rates measure different things. They have been deliberately kept separate throughout the article.