Received ₹10 Lakh as a Bonus. How Should You Invest This Amount?
Finnovate’s editorial team researches and creates financial content using trusted sources, regulatory references and inputs from subject experts.
You have ₹10 lakh available. Your salary already takes care of regular expenses, your EMIs are running and your SIPs may already be going through every month.
So what should you actually do with this money?
A part of the bonus may be better used for an emergency-fund gap, expensive debt, planned spending or a near-term goal. The remaining long-term surplus can then be invested according to your goals and existing portfolio.
First, Does Your Financial Plan Need Anything From This Bonus?
A large bonus can help fix something that your regular salary might otherwise take months to address.
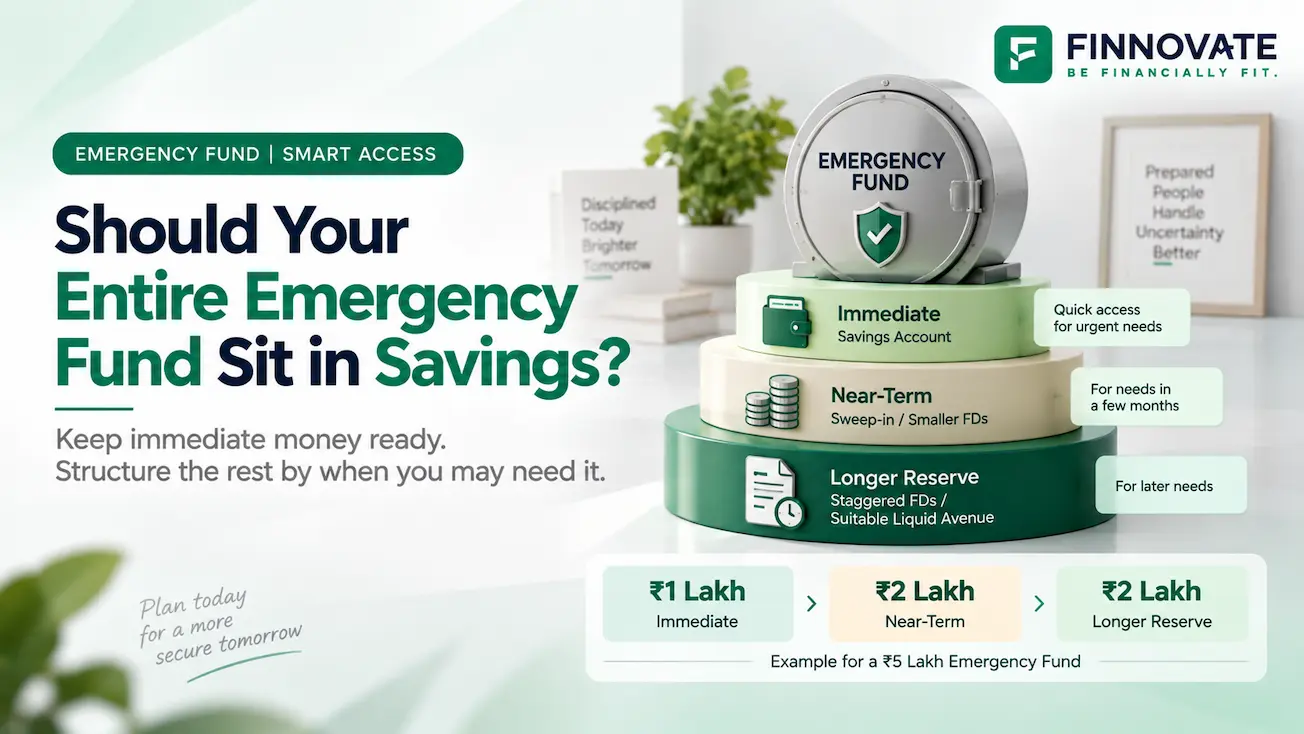
Suppose you currently have ₹2 lakh in your emergency fund but have calculated that you need ₹4 lakh.
Using ₹2 lakh from the bonus closes that gap immediately without requiring you to redirect your regular monthly savings for several months.
If your emergency fund is already adequate, your protection needs are addressed and there is no immediate cash requirement, move to the next decision rather than creating a financial gap that does not exist.
If you are still deciding how large your reserve should be, use Finnovate's Emergency Fund Calculator.
Should You Use the Bonus to Pay Off a Loan?
Having a loan does not automatically mean the bonus should go towards repayment.
High-cost debt deserves attention first
Suppose you have ₹3 lakh outstanding on a personal loan at 15%.
If the full ₹3 lakh remained outstanding for a year, 15% represents roughly ₹45,000 of annual interest before allowing for the reducing balance.
Clearing expensive debt removes a known borrowing cost. The same logic becomes even more important with revolving credit-card debt, where carrying a balance can be particularly costly.
A manageable home loan is a different decision
Now suppose your home loan costs 8.5%, the EMI is comfortably covered by salary and you are considering a ₹5 lakh prepayment.
The decision can also depend on remaining tenure, liquidity needs, tax treatment and the loan's prepayment conditions.
The important point is that “I have a loan” is not enough information to decide what the bonus should do.
See Finnovate's Loan Prepayment vs Investing guide for a deeper comparison.
Can You Spend Part of the Bonus?
Yes. A bonus does not need to become an investment portfolio overnight.
You may want to use part of it for a holiday, a planned purchase or something else you have deliberately postponed.
Decide deliberately how much you want to spend, set it aside and let the rest continue through the financial-planning process.
What Financial Goal Could the Bonus Help You Reach Faster?
A lump sum can accelerate a goal that would otherwise take years of monthly contributions.
Suppose you need ₹15 lakh for a house down payment in three years and have already accumulated ₹9 lakh.
The remaining gap is:
Using ₹6 lakh from the bonus could close that gap immediately.
The investment decision for that ₹6 lakh should then be very different from money intended for retirement 15 or 20 years away.
SEBI's investor guidance similarly emphasises investment horizon, risk appetite, safety, liquidity, diversification and asset allocation when selecting investments.
Source: SEBI Investor: Factors to Consider Before Investing
For a deeper framework, see Finnovate's Goal-Based Financial Planning guide.
How Much of the ₹10 Lakh Is Left for Long-Term Investing?
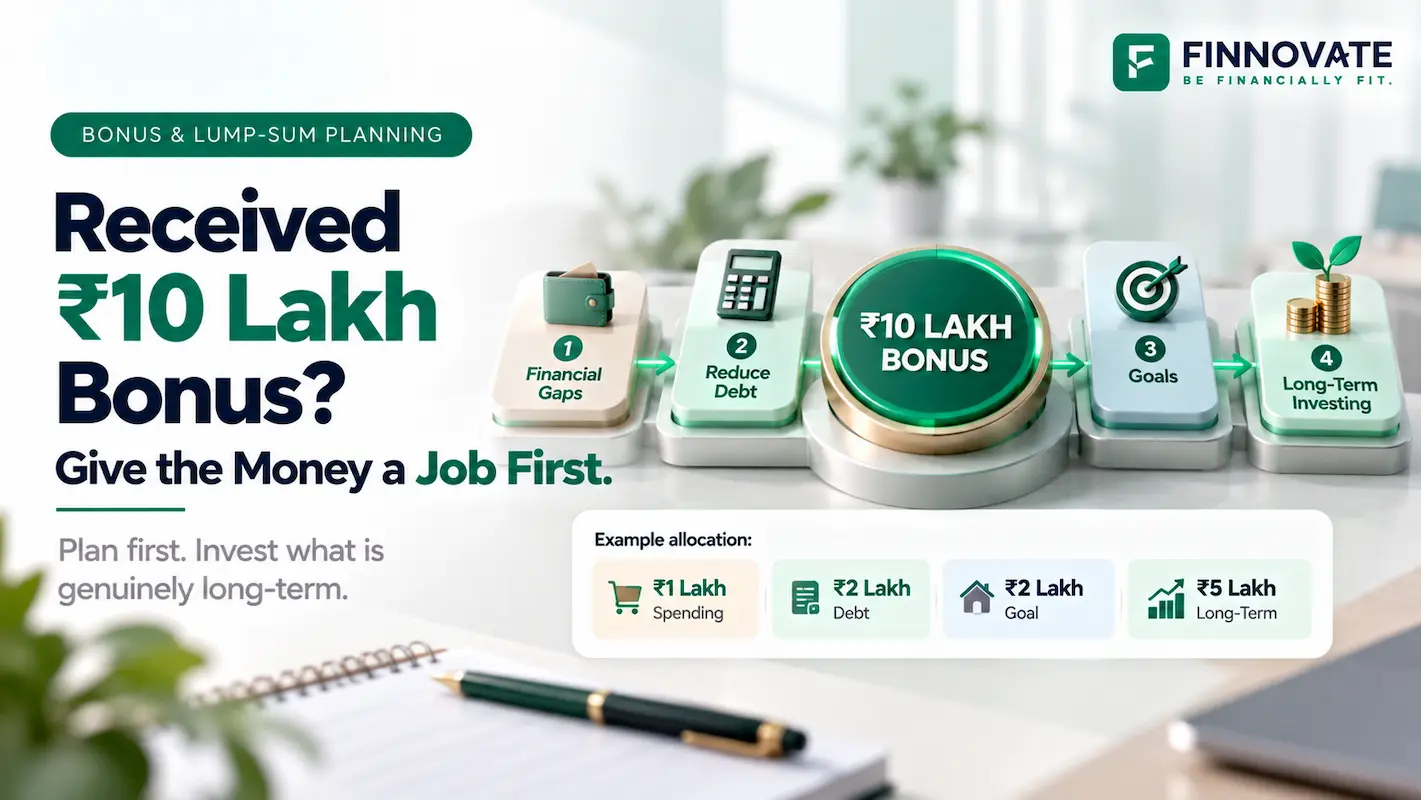
By now, different parts of the bonus may already have different jobs.
For example:
The ₹2 lakh reserved for the near-term goal may still be invested, but it has a different time horizon and therefore needs a different risk approach from the ₹5 lakh long-term surplus.
Your own split may look completely different.
Someone with no debt, no financial gaps and no near-term requirement may have almost the full ₹10 lakh available for long-term investment.
Before Choosing an Investment, What Do You Already Own?
Suppose ₹5 lakh is available for long-term investment.
The next question should not immediately be:
“Which fund should I buy?”
First look at your existing portfolio.
The same ₹5 lakh changes these portfolios very differently.
That does not tell us that either investor should necessarily add ₹5 lakh to equity. It shows why a new investment should be evaluated in the context of everything you already own.
SEBI describes asset allocation as distributing money across asset classes based on factors such as financial goals, risk tolerance and investment horizon.
See Finnovate's Portfolio Review Checklist for a broader portfolio-level review.
Where Could the Investable Amount Go?
Once the goal, time horizon and existing portfolio are clear, investment selection becomes much easier.
| Role of the money | What matters most | Options that may be evaluated |
|---|---|---|
| Near-term stability | Liquidity and lower volatility | Bank FDs and suitable debt-oriented avenues |
| Long-term growth | Ability to remain invested through market volatility | Diversified equity-oriented investments, subject to risk capacity and portfolio allocation |
| Blended exposure | Combination of growth and stability | Appropriate hybrid strategies |
| Diversification | Reducing dependence on one asset class | Gold or other suitable diversifiers where they improve the overall portfolio |
SEBI's investor education material notes that money needed in the near future should generally avoid volatile or illiquid investments, while longer horizons allow more time to absorb market fluctuations.
Source: SEBI Investor: Managing Investment Risk
You Have ₹10 Lakh. Does That Mean You Should Consider an SIF?
The amount is relevant because the current SEBI framework requires an investor's aggregate investment across strategies offered by a Specialized Investment Fund, or SIF, at the PAN level to be at least ₹10 lakh, subject to the applicable exceptions.
But the minimum threshold answers:
It does not answer “Should this investment be part of my portfolio?”
The decision still needs to make sense for your goal, risk capacity, understanding of the strategy and existing investments.
The fact that your bonus happens to match a product's minimum investment threshold is not, by itself, an investment reason.
Should You Invest the Money All at Once or Gradually?
Suppose you have decided that ₹5 lakh belongs in a long-term equity allocation.
You still need to decide how quickly to deploy it.
A Systematic Transfer Plan, or STP, is another mechanism that can transfer a specified amount periodically from one mutual-fund scheme to another, subject to the schemes' terms, applicable NAV, exit load and tax treatment.
The choice therefore depends not only on what markets may do next, but also on whether you can invest the amount at once and remain comfortable with the plan if markets fall shortly afterwards.
Same ₹10 Lakh Bonus. Three Completely Different Decisions.
The clearest way to see why there is no universal ₹10 lakh allocation is to give the same amount to three people with different financial lives.
This person has a ₹2 lakh emergency-fund gap and ₹2 lakh of expensive debt.
Emergency
Debt
Remaining
Emergency savings and debt are already under control, but a known near-term goal exists.
3-year goal
Long-term surplus
The emergency fund is adequate, there is no expensive debt, no near-term requirement exists and the portfolio is already diversified.
What Mistakes Should You Avoid With a ₹10 Lakh Bonus?
Your ₹10 Lakh Bonus: A Decision Framework
Emergency reserve, protection or a known cash requirement may deserve attention first.
Look at the borrowing cost, remaining tenure, liquidity and loan terms rather than simply asking whether a loan exists.
Keep planned one-time spending separate from permanent lifestyle commitments.
Give each portion an amount and a deadline.
Separate money already assigned to near-term uses from money that can remain invested for years.
Decide where new money is actually needed rather than automatically buying more of the same asset.
Horizon, liquidity and risk should determine the role of each asset.
Decide whether the selected allocation should be invested immediately or staggered over time.
Start With the Goal, Not the Product
If part of the bonus is meant for a future goal, first define the amount required and when you will need it.
Understand Goal-Based PlanningOnce the goal and timeline are clear, the investment decision becomes much easier to evaluate.
So, How Should You Invest a ₹10 Lakh Bonus?
A ₹10 lakh bonus does not need one investment. It may need several jobs.
Use it first where it can strengthen your financial position. Address genuine financial gaps and expensive debt where appropriate. Keep money required for near-term goals aligned with those deadlines.
Then look at the long-term surplus in the context of your existing portfolio before deciding where it should be invested.
For one person, that may mean investing almost the entire bonus.
For another, the better use may be a combination of debt repayment, a near-term goal, planned spending and long-term investing.
The amount is the same. The right decision depends on what the money needs to do.
FAQs
1. Should I invest my entire ₹10 lakh bonus?
Not necessarily. First check whether part of the money has a better immediate job, such as filling an emergency-fund gap, repaying expensive debt, funding planned spending or covering a near-term goal. The remaining long-term surplus can then be invested according to your goals and portfolio.
2. Should I repay my home loan with the bonus?
Not automatically. Consider the loan rate, remaining tenure, liquidity requirements, applicable tax treatment and prepayment terms. Also remember that interest saved through prepayment is based on known loan terms, while future investment returns are uncertain.
3. Where should I invest ₹10 lakh if I need the money in three years?
When a goal is only about three years away, capital stability and liquidity generally deserve greater weight than maximising return. A plan that depends heavily on equity markets being favourable exactly when the goal arrives can create unnecessary timing risk. FDs and suitable debt-oriented options can be evaluated depending on the goal, liquidity requirement and tax position.
4. Should I invest the bonus as a lump sum or through STP?
Both approaches are possible. A lump-sum investment gives the entire amount market exposure immediately. Staggering or using an STP spreads entry over time. Staggering does not remove market risk or guarantee better returns.
5. What if I already invest every month through SIPs?
Your bonus does not automatically need to go into the same funds. Review the entire portfolio and decide which asset class or goal actually needs additional money before deploying the lump sum.
6. Can I spend part of my bonus instead of investing all of it?
Yes. Planned one-time spending can be part of the decision. The more important distinction is between spending part of a one-time bonus once and using it to create a recurring commitment that continues after the bonus is gone.
7. Should I put the full ₹10 lakh into mutual funds?
Not simply because the money is available. Whether mutual funds have a role, and what type of exposure is suitable, depends on the goal, time horizon, risk capacity and the investments you already hold.
8. Should I invest ₹10 lakh in an SIF because I meet the minimum amount?
Meeting the minimum investment threshold only establishes eligibility. It does not establish suitability. The strategy, risk, liquidity, portfolio role and your ability to understand the product should be evaluated separately.