How to Consolidate Your Mutual Fund Portfolio: What to Keep, Stop or Redeem
Finnovate’s editorial team researches and creates financial content using trusted sources, regulatory references and inputs from subject experts.
A mutual fund portfolio can grow one SIP at a time. You start a large-cap fund, add a mid-cap fund later, pick another scheme after seeing its returns, continue an ELSS investment for tax saving, and eventually end up with several funds without a clear idea of what each one contributes.
The answer is not to sell everything except your best-performing funds.
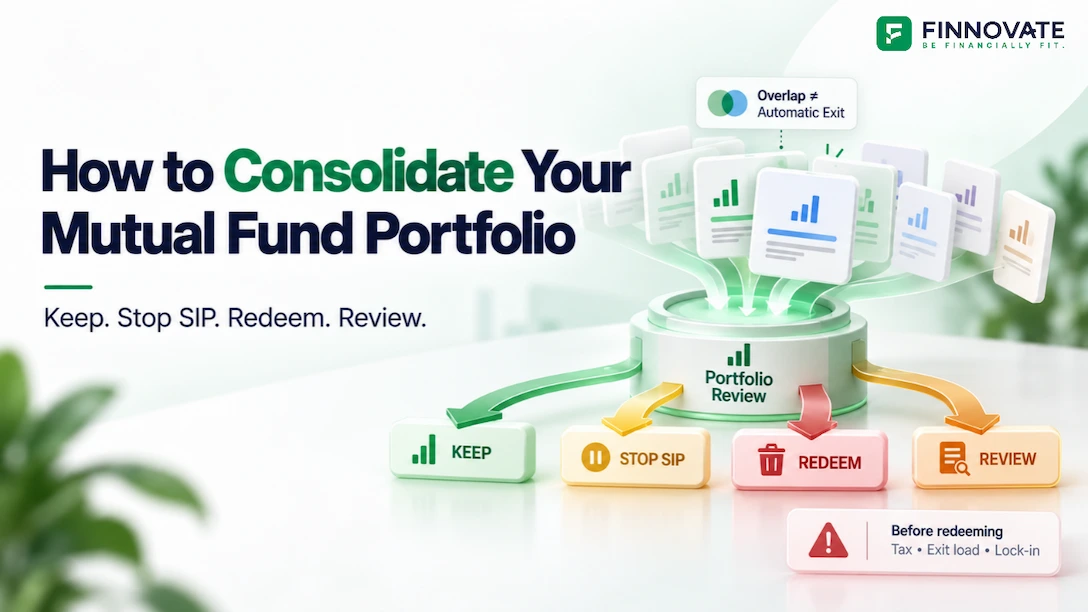
Build a complete list of your holdings, connect each investment to a goal and portfolio role, identify unnecessary duplication, and assign every fund one of four actions: keep, stop or redirect the SIP, redeem or consolidate, or review later.
Before selling anything, check the tax impact, exit-load terms and any applicable lock-in.
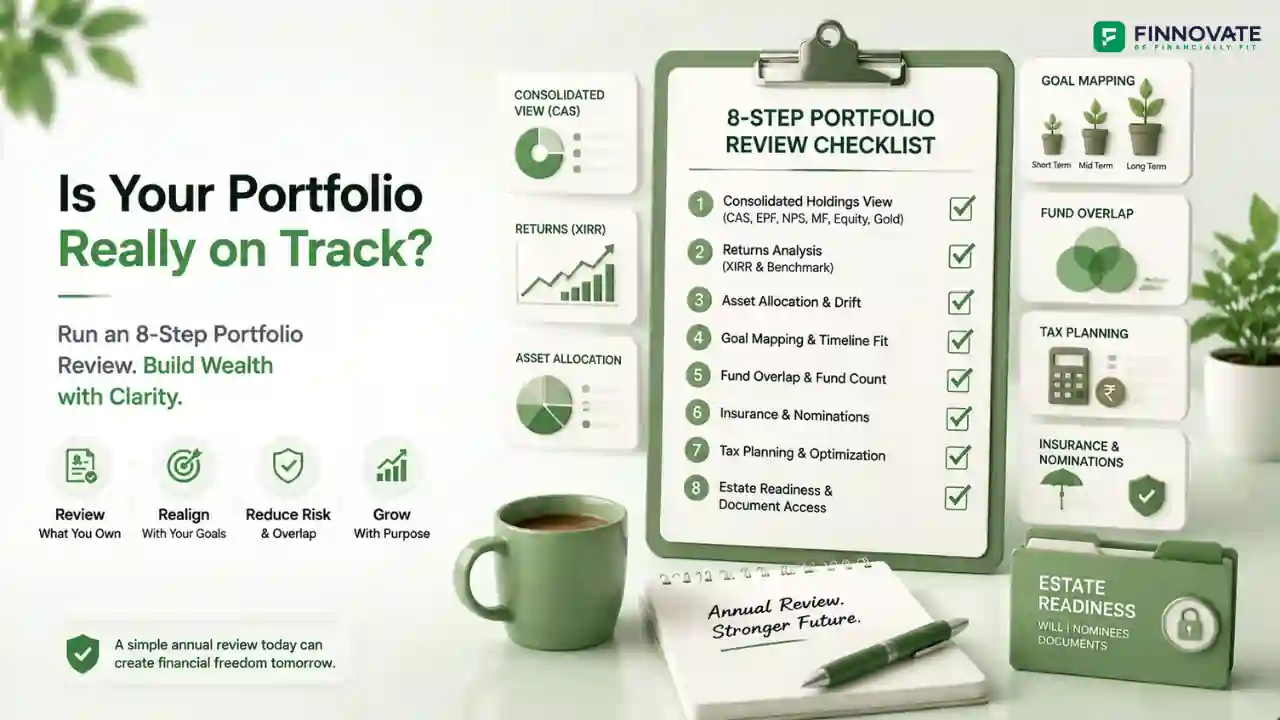
1. List Every Mutual Fund You Own
Before deciding what to remove, build a complete picture of your holdings.
Investments spread across different apps, fund houses and folios can make the portfolio look simpler than it actually is.
You can obtain a consolidated account statement through AMFI's CAS page , which links to CAMS and KFintech. Portfolio and consolidated statement facilities are also available through MFCentral .
Check older or inactive folios too. A consolidation decision based on an incomplete portfolio can simply create a different form of duplication.
Also look for Direct and Regular versions of the same scheme
Investors who used different platforms or intermediaries over time can sometimes hold both Direct and Regular plans of the same underlying scheme.
Flag these for review, but do not assume that moving from one plan to another is cost-free. A switch-out can be treated as a redemption, which can have tax and exit-load consequences.
2. Decide What Your Portfolio Needs to Do
A fund should be assessed against your financial plan, not only against the other schemes visible in your app.
Start with your major goals and when you expect to need the money.
Next, assess how much of the overall portfolio should be in equity, debt and other assets based on your goals, horizon and ability to take risk.
Do not look at mutual funds in isolation. Relevant holdings such as EPF, PPF, NPS and fixed deposits can materially change your overall asset allocation.
Now compare that plan with the mutual funds you own.
One scheme may be unnecessary because another fund already performs the same role. Another may look similar but provide an exposure that you deliberately want to retain.
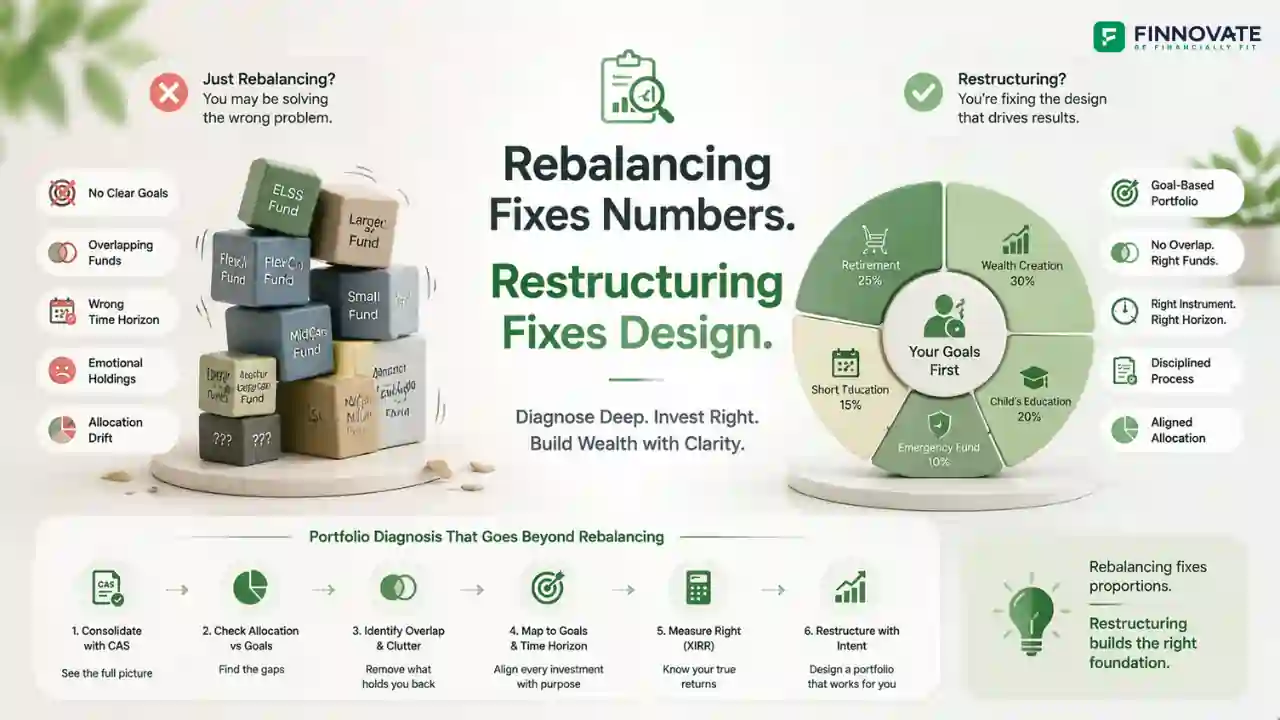
If your investments no longer fit your wider financial situation, see Finnovate's guide to signs your portfolio needs restructuring, not just rebalancing .
3. Compare Similar Funds Before Deciding What to Remove
Start with schemes that appear to perform the same job.
You may have two large-cap funds, several flexi-cap funds, multiple mid-cap funds or sectoral schemes purchased at different points in the market cycle.
Finnovate's Mutual Fund Overlap Calculator can help you compare the underlying holdings of funds that appear similar.
Two funds can own some of the same stocks but hold them in different weights, follow different investment styles or serve different roles.
The reverse can also happen. Two schemes may not have extremely high stock-level overlap but may still give you broadly the same type of exposure.
For each pair you review, ask:
- Do both funds provide substantially the same exposure?
- Does either fund have a distinct role that justifies keeping it?
- If you stopped investing in one, would your intended asset allocation change?
4. Decide What to Do With Each Fund
Not every fund that needs attention should be redeemed.
Assign each scheme one of four actions.
Do not choose funds only by recent returns
A scheme that underperformed over the last year is not automatically a poor investment.
Compare it with an appropriate benchmark and relevant category peers over more than one short period. Also check whether its investment process, management, portfolio or role in your plan has changed materially.
The opposite is also true. A fund does not deserve a permanent place in the portfolio simply because its historical return looks strong.
Give extra attention to sectoral and thematic funds
A sectoral or thematic scheme may have been added when a particular industry or theme was performing strongly.
Check whether the exposure still has a deliberate role and whether the resulting concentration fits the risk you want to take.
That does not mean every sectoral or thematic fund needs to be sold.
The objective is to remove unnecessary exposure without accidentally removing something your financial plan deliberately requires.
5. Check the Cost Before Redeeming or Switching
Once you identify a fund that may be removed, check what happens if you actually exit it.
A redemption or switch can create tax or other costs even when your objective is simply to simplify the portfolio.
Exit-load changes do not automatically rewrite the terms for old units
Mutual funds can modify their load structures, but changes in load structure apply prospectively. When reviewing existing units, check the load terms applicable to those purchases rather than looking only at the latest headline exit-load schedule.
Source: AMFI: NAV, Redemption Price and Exit Load
Each ELSS SIP instalment has its own lock-in
ELSS units have a three-year lock-in from the date of allotment.
If you invested through an SIP, each instalment therefore completes its three-year lock-in separately. Stopping future ELSS contributions does not make recently purchased units immediately redeemable.
A switch is not just an administrative transfer
A switch-out from one mutual-fund scheme is treated as a redemption and the switch-in as a purchase into the destination scheme.
Tax consequences and any applicable exit load can therefore arise even though the money remains invested in mutual funds.
You do not have to redeem every redundant fund on the same day.
But spreading redemptions across financial years should be based on your actual capital gains, tax position, exit costs and investment plan, not on an assumption that delaying an exit will always reduce tax.
6. Consolidate the Portfolio in the Right Order
Once the decisions are clear, make the changes in an order that does not disrupt the rest of your financial plan.
How quickly does an SIP cancellation take?
Current mutual-fund documentation reflecting SEBI's SIP-cancellation framework provides for registered SIP cancellation requests to become effective within two working days from receipt of the request.
An instalment whose debit instruction has already been triggered may still be processed before cancellation is fully reflected, depending on the stage of the payment cycle. Follow the AMC or platform's cancellation status rather than assuming the next debit has stopped immediately after submitting the request.
For a broader framework around financial goals and asset allocation, see Finnovate's Portfolio Management guide .
What Could Consolidation Look Like in Practice?
Consider an investor who has accumulated seven mutual-fund holdings over several years.
This is not a recommended seven-fund portfolio. It simply shows how different funds can result in different actions after the review.
| Holding | What the review finds | Possible action |
|---|---|---|
| Large-cap Fund A | Has a clear core-equity role and remains aligned with the plan. | KEEP |
| Large-cap Fund B | Provides substantially the same portfolio role as Fund A. | STOP SIP |
| Flexi-cap Fund | Has a distinct role in the intended equity allocation. | KEEP |
| Mid-cap Fund | Still fits the investor's long-term allocation and risk capacity. | KEEP |
| Sectoral Fund | The original tactical reason for owning it no longer exists and the exposure is no longer required. | ASSESS REDEMPTION |
| Older ELSS Fund | No longer needed for future contributions, but some SIP units remain within their lock-in. | REVIEW LATER |
| Duplicate Direct / Regular holding | Similar underlying exposure is held through two plans, but moving units may create tax or exit-load consequences. | CHECK COST FIRST |
Notice that only one fund in this example immediately reaches the “assess redemption” stage.
Consolidation can often begin by redirecting future money before forcing every existing holding out of the portfolio.
Common Mutual Fund Consolidation Mistakes
The Final Consolidation Check
Once the changes are complete, you should be able to explain why every remaining fund is there.
ALL FUNDS
THE ROLE
DUPLICATION
AN ACTION
EXIT COST
CHANGES
ALLOCATION
Keep a record of why you retained each fund and why you removed or stopped investing in the others.
Review that reasoning when your goals, time horizon or financial circumstances change.
For a dedicated discussion on portfolio size, see Finnovate's guide to how many mutual funds you should have in your portfolio .
FAQs
1. How many mutual funds should I keep in my portfolio?
There is no fixed number that suits every investor. The appropriate number depends on your financial goals, asset allocation, risk capacity and whether each scheme contributes a distinct role rather than merely adding another fund name.
2. Should I stop an SIP or redeem the existing mutual fund investment?
These are separate decisions. Stopping an SIP prevents future instalments but leaves your existing units invested. You can stop adding new money while retaining the existing holding, or redeem it after assessing suitability, tax, exit load and any applicable lock-in.
3. Does switching from one mutual fund to another attract tax?
A switch-out is treated as a redemption from the original scheme and the switch-in as a purchase in the destination scheme. Capital-gains tax and any applicable exit load can therefore arise even though the money remains within mutual funds.
4. Should I sell a mutual fund that has underperformed?
Not solely because of a weak recent return. Compare its performance with an appropriate benchmark and relevant peers over more than one short period, and review whether its investment process, management, portfolio or suitability for your goals has changed.
5. Can I consolidate ELSS investments before the lock-in ends?
ELSS units are subject to a three-year lock-in from their respective allotment dates. For an SIP, each instalment therefore has its own lock-in period. You can stop or redirect future contributions, but units that remain locked cannot be redeemed simply because you want to consolidate the portfolio.
6. Does mutual fund overlap mean I should sell one of the funds?
Not automatically. Overlap tells you how much underlying exposure two funds share, but the decision should also consider portfolio weights, investment style, category, financial goal and the role each fund serves within your overall allocation.
7. Should I consolidate all redundant mutual funds immediately?
Not necessarily. Some funds may justify an immediate change in future SIPs while the existing units are retained temporarily because of tax, exit-load or lock-in considerations. Consolidation can therefore happen in stages.