Top-Up vs Super Top-Up Health Insurance: Which One Should You Choose?
Finnovate’s editorial team researches and creates financial content using trusted sources, regulatory references and inputs from subject experts.
Imagine you have a health insurance policy with a ₹5 lakh sum insured.
During the same policy year, you are hospitalised twice.
The first eligible hospital bill is ₹2 lakh. A few months later, the second is ₹2.5 lakh.
Your total eligible medical expenses come to ₹4.5 lakh.
Now suppose you also have additional health insurance with a ₹3 lakh deductible.
Will it pay?
That depends on how the "deductible" works.
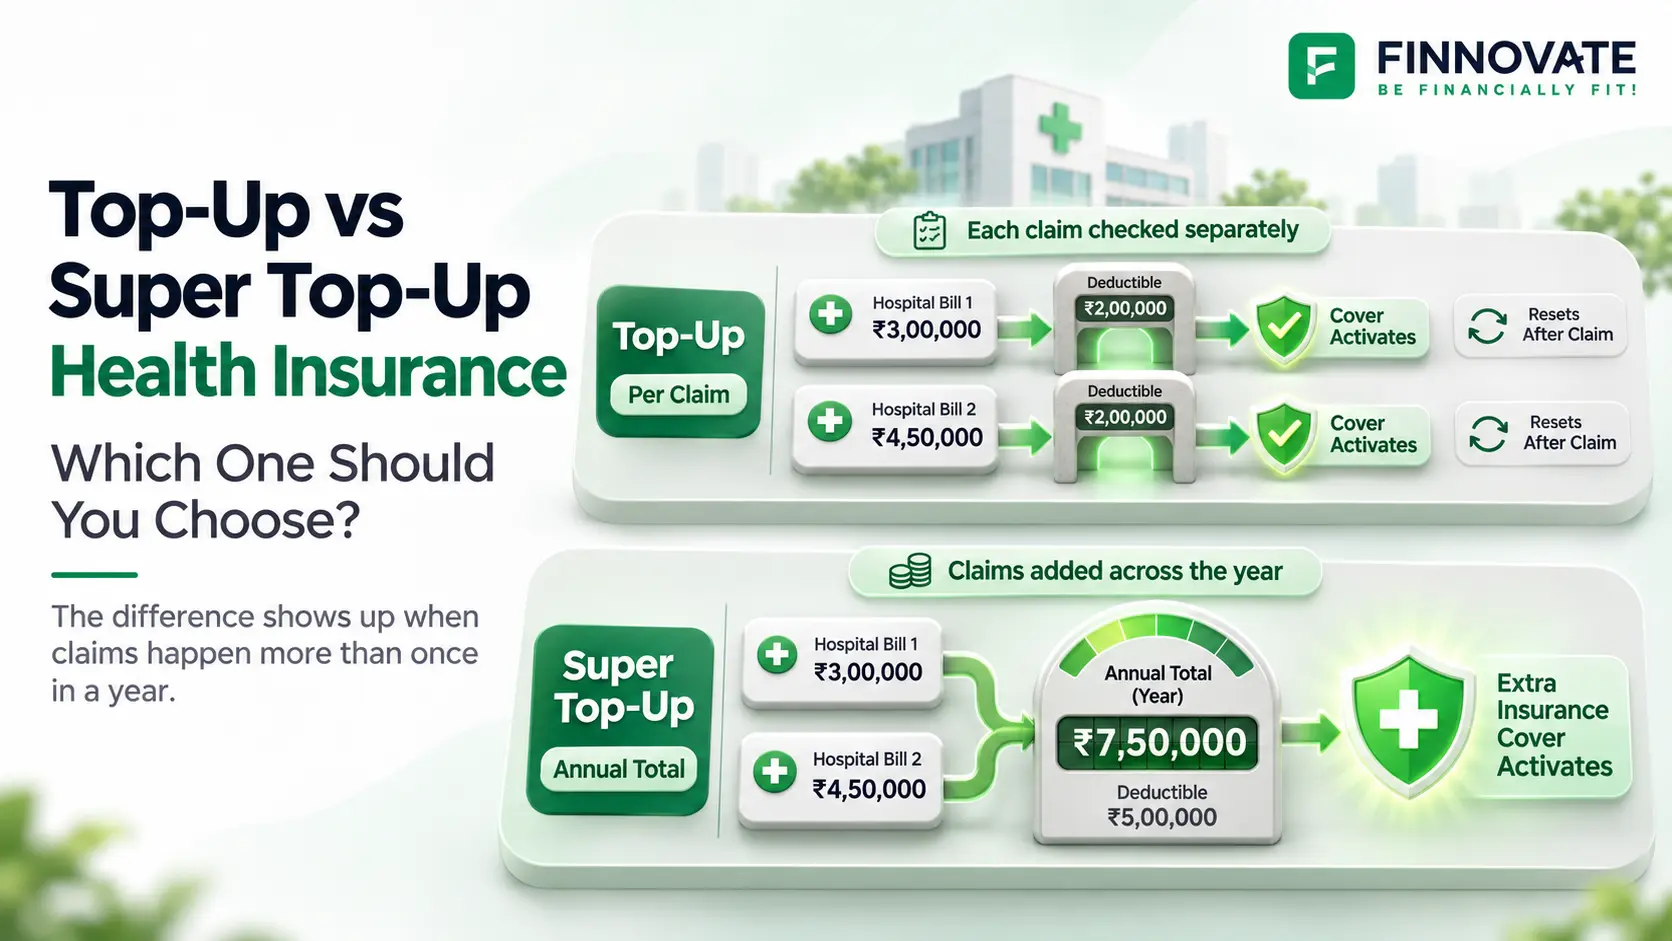
In a traditional per-claim top-up, neither ₹2 lakh nor ₹2.5 lakh crosses the ₹3 lakh deductible individually.
In an annual-aggregate super top-up, the two eligible claims add up to ₹4.5 lakh. That leaves ₹1.5 lakh above the ₹3 lakh deductible.
A super top-up is generally the more useful structure when you want multiple eligible hospitalisations during the policy year to count towards one deductible.
This can be particularly useful for families, older parents and anyone who wants additional protection against repeated hospitalisations.
A traditional top-up can fit when your main concern is one unusually large hospitalisation that crosses the deductible by itself.
First, What Exactly Is a Deductible?
A deductible is the threshold that eligible medical expenses need to cross before the additional health insurance starts paying according to its terms.
Suppose you buy a super top-up with:
The ₹3 lakh deductible is not taken away from the ₹7 lakh sum insured.
The deductible tells you when the additional policy starts responding. The sum insured tells you how much additional cover is available, subject to the policy terms.
Does the Base Policy Have to Match the Deductible?
No fixed rule says that a ₹5 lakh base policy must always be paired with a ₹5 lakh deductible.
Matching the two can make the structure easier to manage because the base policy may cover much of the expense below the deductible.
But the better test is whether you can reliably handle that deductible using your base policy, employer cover, your own funds or a combination.
Top-Up vs Super Top-Up Health Insurance: Key Differences
| Feature | Traditional Top-Up | Annual-Aggregate Super Top-Up |
|---|---|---|
| Deductible trigger | Generally tested against an individual claim or hospitalisation | Aggregate eligible expenses during the policy year |
| Multiple hospitalisations | Each claim usually needs to cross the deductible on its own | Eligible claims can accumulate towards the deductible |
| One large hospitalisation | Can pay when the individual claim crosses the deductible | Can also pay when eligible expenses cross the annual deductible |
| Main use | Additional protection against one large claim | Additional protection against large or repeated claims during the year |
| Family aggregation | Depends on the policy structure | Can apply across covered family members in some floater structures |
| Expenses below deductible | May be handled through base cover, employer cover or own funds | May be handled through base cover, employer cover or own funds |
The market commonly uses “top-up” for a per-claim structure and “super top-up” for an annual aggregate structure, but product naming is not perfectly uniform.
Scenario 1: One Large Hospitalisation
Suppose your additional policy has:
- Deductible: ₹3 lakh
- Additional sum insured: ₹7 lakh
You have one eligible hospitalisation costing ₹5 lakh.
One hospitalisation itself has crossed the ₹3 lakh deductible.
In this situation, a traditional per-claim top-up and an annual-aggregate super top-up can produce a similar result.
The difference becomes much more important when the medical expenses are spread across several hospitalisations.
Scenario 2: Two Hospitalisations in the Same Year
Now assume the traditional top-up applies a ₹3 lakh deductible to each hospitalisation, while the super top-up has a ₹3 lakh annual aggregate deductible.
- First eligible claim: ₹2 lakh
- Second eligible claim: ₹2.5 lakh
| Particulars | Traditional Top-Up | Super Top-Up |
|---|---|---|
| First claim | ₹2 lakh | ₹2 lakh |
| Second claim | ₹2.5 lakh | ₹2.5 lakh |
| Deductible | ₹3 lakh per hospitalisation in this example | ₹3 lakh annual aggregate |
| Total eligible expenses | ₹4.5 lakh | ₹4.5 lakh |
| Amount above deductible | Nil | ₹1.5 lakh |
| Potential payout | Nil | ₹1.5 lakh |
For the traditional top-up in this example, neither individual claim crosses ₹3 lakh.
The super top-up adds the two eligible claims together.
₹4.5L − ₹3L Deductible = ₹1.5L
This annual aggregation is the reason a super top-up can be more useful when several hospitalisations happen during the same policy year.
A Smaller Claim Can Still Matter Later
Suppose your super top-up has a ₹3 lakh annual deductible.
Your first eligible hospitalisation is ₹1.5 lakh.
No super top-up payment may arise at that stage because the annual threshold has not been crossed.
Six months later, another eligible hospitalisation costs ₹2 lakh.
Your aggregate eligible expenses have now reached ₹3.5 lakh.
Keep records for hospitalisations that may count towards the annual deductible:
- hospital bills and receipts
- discharge summaries
- diagnostic reports
- claim settlement records
- insurer or TPA communication
How Do Your Base Policy and Super Top-Up Work Together?
Consider this structure:
- Base health insurance: ₹2 lakh
- Super top-up deductible: ₹3 lakh
- Super top-up sum insured: ₹7 lakh
- Eligible hospitalisation expenses: ₹9 lakh
Your base policy may pay ₹2 lakh towards the hospitalisation.
The super top-up separately calculates its liability according to its ₹3 lakh deductible and policy wording.
The base policy and super top-up remain separate insurance contracts. Each insurer assesses the claim according to its own policy terms.
Since both are indemnity-based covers, the same admissible medical expense cannot be recovered twice.
How Should You Choose the Super Top-Up Deductible?
The deductible decides how much medical expense has to be handled before the additional cover starts paying.
So choosing it only on the basis of a lower premium can create a problem later.
What If You Depend on Employer Health Insurance?
Suppose your employer provides ₹5 lakh of health insurance and you choose a ₹5 lakh super top-up deductible.
Later, you change jobs and the new employer provides only ₹2 lakh.
Your super top-up deductible is still ₹5 lakh, but the insurance available below it has reduced.
That is why the deductible should remain manageable even if your employer cover changes or disappears.
Can Claims of Two Family Members Cross the Super Top-Up Deductible?
In some family floater super top-up policies, yes.
Eligible expenses across covered family members can be aggregated during the policy year where the policy uses a family-level aggregate deductible.
For example:
- Spouse A eligible expenses: ₹1.8 lakh
- Spouse B eligible expenses: ₹1.7 lakh
- Family floater deductible: ₹3 lakh
₹3.5L − ₹3L = ₹50,000
Check whether the deductible applies separately to each insured person or across the insured family.
You can also read our guide on Family Floater vs Individual Health Insurance to understand how shared health cover works.
What Should You Check Before Buying?
| What to Check | Why It Matters |
|---|---|
| Deductible definition | Check whether it applies per hospitalisation, per claim or to aggregate eligible expenses during the policy year. |
| Individual vs family deductible | This determines whether expenses across family members can combine. |
| Existing base cover | Know how much insurance already exists below the additional layer. |
| Employer-cover dependence | Check whether the deductible remains manageable if employment benefits change. |
| Waiting periods | The additional policy can have its own waiting periods for pre-existing diseases and specified treatments. |
| Co-pay and sub-limits | These can increase your own contribution during a claim. |
| Room eligibility | Check whether room restrictions apply and how they affect claim settlement. |
| Eligible expenses | Only covered medical expenses can count towards the deductible. |
| Claim documentation | Earlier hospitalisations may need to be documented when claims are aggregated. |
| Policy-year reset | An annual aggregate deductible generally starts again in the next policy year. |
Three Common Misunderstandings
Final Takeaway
When comparing a top-up and a super top-up, the additional sum insured is only one part of the decision.
The more important question is how the deductible behaves when hospitalisations actually happen.
1. Is the deductible applied to each claim or to aggregate eligible expenses during the year?
2. How will the expenses below that deductible be funded?
3. If several hospitalisations happen, can those eligible expenses add up?
Those answers tell you how the additional cover will actually work when you need it.
FAQs
1. Is a super top-up better than a top-up health insurance plan?
If you want multiple eligible hospitalisations during the same policy year to count towards one deductible, an annual-aggregate super top-up is generally the more useful structure. A traditional per-claim top-up mainly helps when one hospitalisation itself crosses the deductible.
2. Can I buy a super top-up without a base health insurance policy?
Some super top-up products may be available without a separate base policy. You still need to understand how medical expenses below the deductible will be handled. Check the eligibility and deductible conditions of the specific product.
3. Does my base health policy need to match the super top-up deductible?
No fixed rule requires the two amounts to be identical. Matching them can make the structure easier to manage, but what matters is whether you can reliably fund the expenses below the deductible.
4. Does the super top-up deductible reset every year?
For an annual-aggregate super top-up, the deductible generally applies afresh in each policy year.
5. Does every hospital bill count towards the deductible?
Only eligible medical expenses considered under the additional policy count towards the deductible. Excluded or non-covered expenses may not count.
6. Can employer health insurance help with the deductible?
Employer health insurance can help fund medical expenses below the deductible. Since employer cover can change when you switch jobs or when group benefits change, the deductible should remain manageable even if that cover reduces.
7. Can claims from two family members combine under a super top-up?
They can under some family floater super top-up policies that use a family-level aggregate deductible. Check whether the deductible applies individually or across covered family members.
8. Does the deductible reduce the super top-up sum insured?
No. If a policy has a ₹3 lakh deductible and ₹7 lakh super top-up sum insured, ₹3 lakh is the threshold while ₹7 lakh is the additional cover available after the deductible conditions are met.
9. What happens if my base policy is smaller than the deductible?
The base policy may cover part of the initial medical expenses. The remaining amount below the deductible may need to be handled through another available cover or your own funds. The super top-up calculates its liability according to its own policy terms.
10. What is the most important thing to check before buying a top-up or super top-up?
Check how the deductible is defined. Find out whether it applies to each claim separately or to aggregate eligible expenses during the policy year. That determines how the cover behaves when more than one hospitalisation occurs.