Health Insurance for Parents Above 60 in India: A Complete Guide for 2026
Finnovate’s editorial team researches and creates financial content using trusted sources, regulatory references and inputs from subject experts.
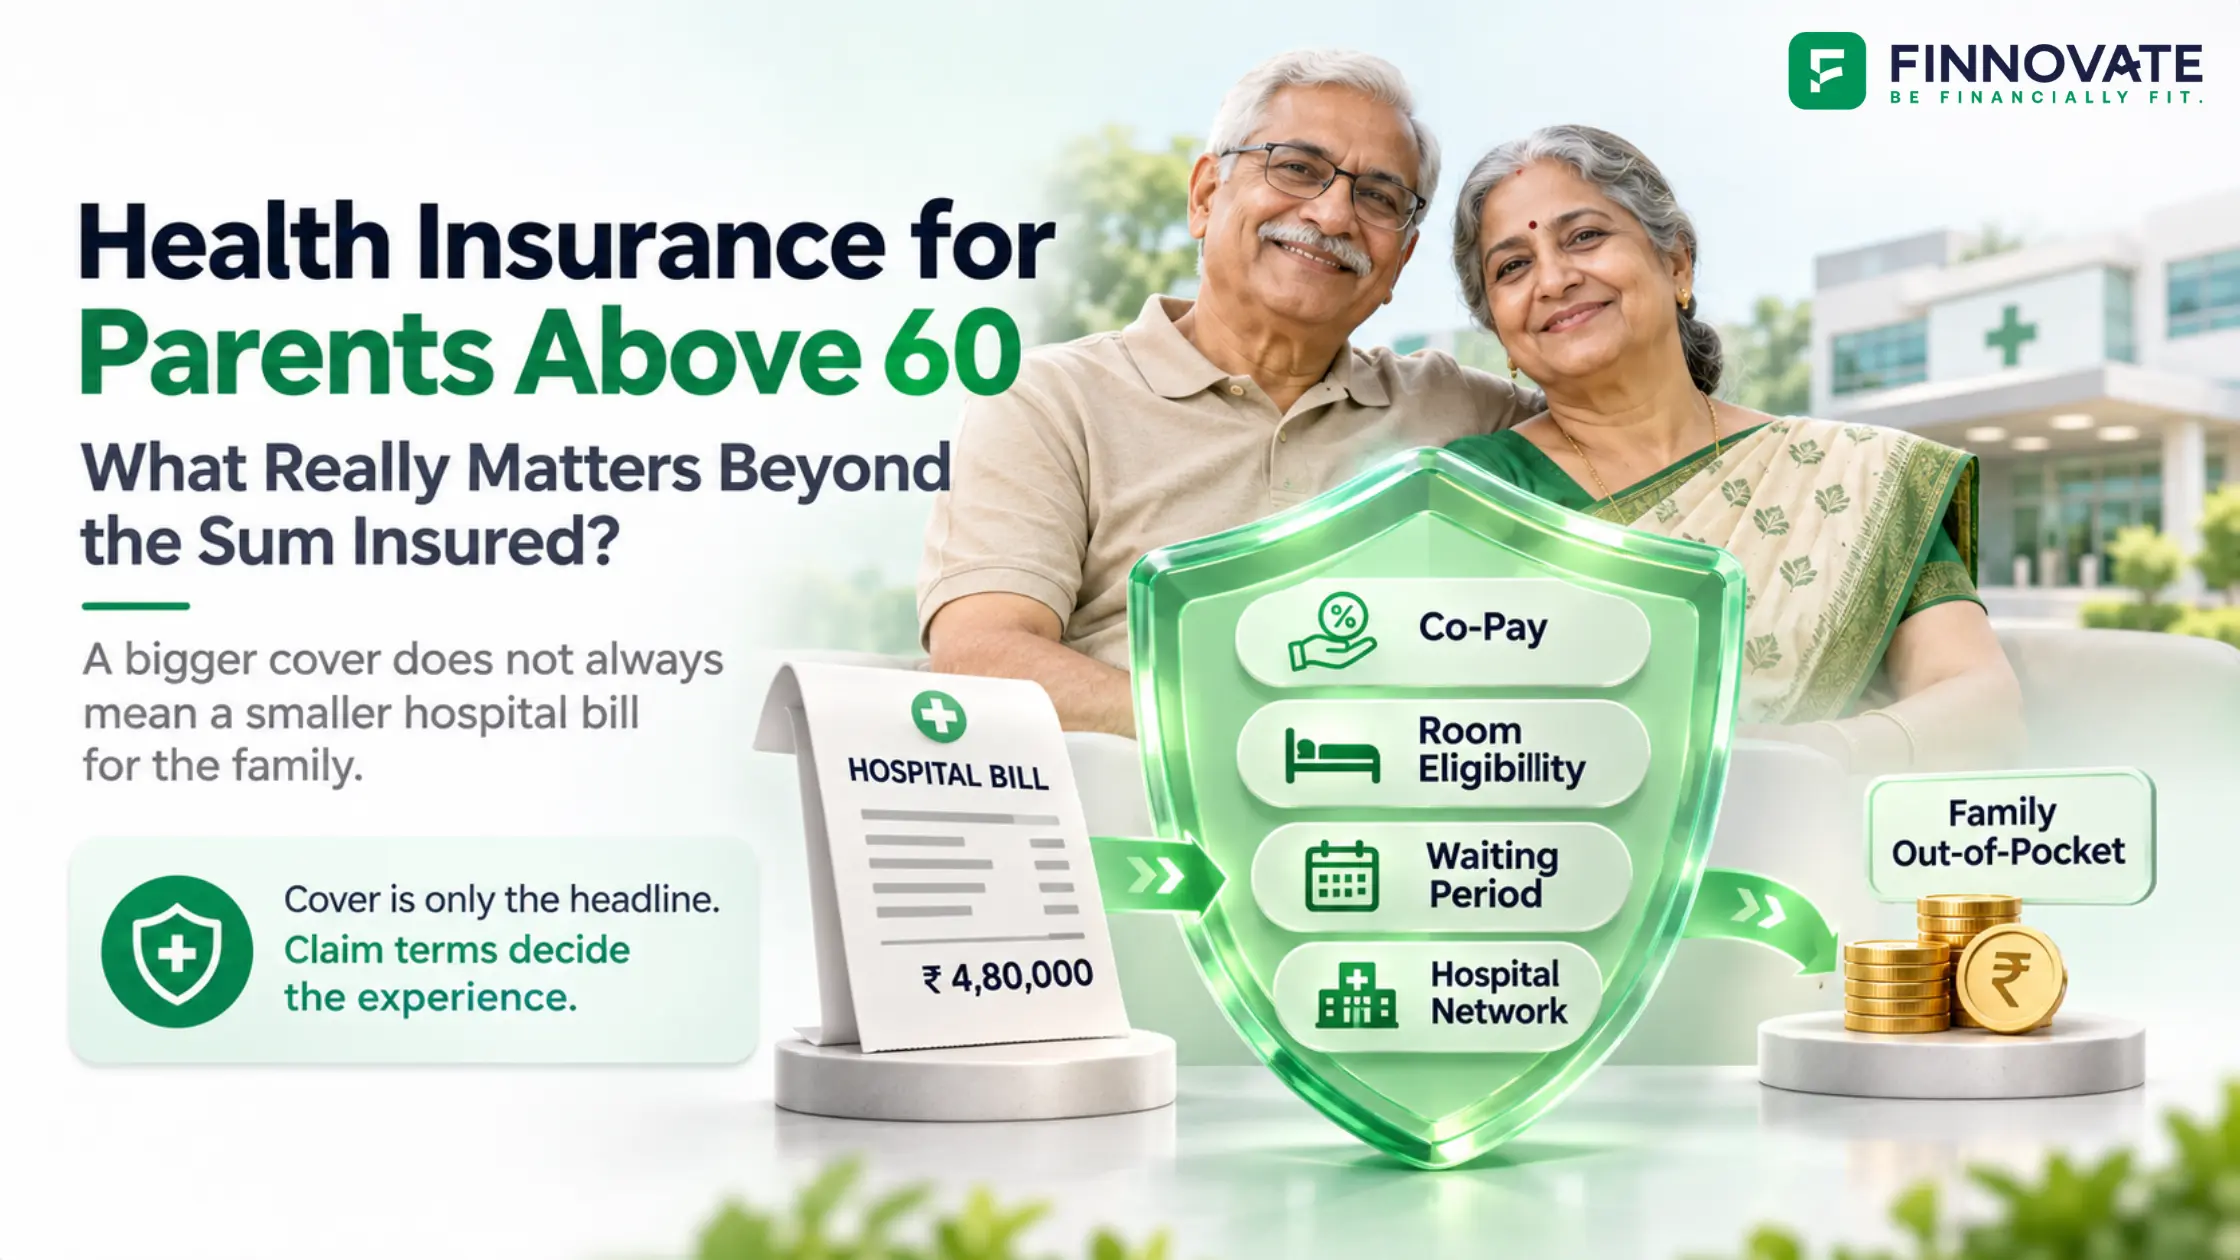
A ₹15 lakh health insurance policy can leave your parents with a larger hospital bill than a ₹10 lakh policy.
The reason is simple. The sum insured tells you the size of the cover. It does not tell you how the claim will actually be settled.
Suppose Policy A offers ₹15 lakh of cover with a 20% co-payment. Policy B offers ₹10 lakh without a compulsory co-pay.
On an admissible hospitalisation claim of ₹8 lakh, Policy A would leave the family paying ₹1.6 lakh as co-pay, while the insurer's share would be ₹6.4 lakh before any other applicable deductions.
Look at co-pay, room eligibility, waiting periods, disease-specific limits, deductibles, hospital network, existing policy continuity and long-term premium affordability.
Can You Buy Health Insurance for Parents After 60 or 65?
Yes.
The current health insurance framework expects insurers to offer products, add-ons and riders across different ages, medical conditions and pre-existing diseases.
The actual proposal is still assessed according to the product's eligibility conditions and medical underwriting.
For an older parent, the insurer may ask for medical tests, previous treatment history, current medication and details of existing illnesses before deciding the terms of cover.
Before Buying a New Policy, Check What Your Parents Already Have
If your parents already have health insurance, start there.
An old policy may have years of continuity behind it. That can matter more than a new policy with a bigger headline cover.
Pull out the policy schedule and policy wording and check:
- current sum insured
- number of continuous years insured
- co-payment requirement
- room-rent eligibility
- disease-specific sub-limits
- deductibles
- waiting periods already completed
- cashless hospitals near your parents
- restoration benefit and its conditions
- current renewal premium
What If Your Parents Are Covered Through Your Employer?
Employer-provided parent cover can be useful, especially when it gives access to a larger group policy or fewer entry restrictions.
But employer cover is tied to the job and the employer's group policy.
A job switch, a change in insurer or a revision in group benefits can change the cover available to your parents.
Parent cover under corporate policies can also carry separate co-pay, room limits or procedure caps.
Regular Health Plan or Senior-Citizen-Specific Plan?
Crossing age 60 does not mean your parent has to choose a policy carrying the label “senior citizen health insurance”.
Regular retail health plans may also accept older applicants, depending on the product and underwriting.
Parents Aged 70 or Above? Check "Ayushman Vay Vandana" Too
For parents aged 70 years and above, private insurance is only one part of the picture.
Under 'Ayushman Vay Vandana', all senior citizens aged 70 years and above are eligible for health coverage of up to ₹5 lakh per family per year for secondary and tertiary hospitalisation, irrespective of socio-economic status.
If a senior citizen aged 70+ belongs to a family already covered under AB PM-JAY (Ayushman Bharat Pradhan Mantri Jan Arogya Yojana), an additional ₹5 lakh top-up is available for eligible senior members.
Senior citizens with private health insurance can also remain eligible.
Treatment is available through empanelled hospitals under the applicable health benefit packages.
Should Parents Be Added to Your Family Floater?
Families usually end up comparing three broad structures.
The better structure depends on the parents' health, available sum insured, premium and how likely it is that both may need treatment in the same year.
What Should You Actually Compare in a Senior Citizen Health Policy?
| What to Check | Why It Matters |
|---|---|
| Co-payment | A percentage of every admissible claim may have to come from your family's pocket. |
| Room-rent eligibility | A room restriction can affect what room your parent can use and, depending on policy wording, other linked hospital charges. |
| Pre-existing disease waiting period | Expenses linked to declared pre-existing diseases may become payable only after the applicable waiting period is completed. |
| Disease-specific sub-limits | A procedure may have its own payout limit even when the overall sum insured is much higher. |
| Deductible | This determines how much eligible expense must be crossed before certain covers start paying. |
| Cashless hospital network | Check the hospitals your parents would realistically use, especially those close to home. |
| Pre- and post-hospitalisation | Check the number of covered days and which diagnostics, medicines and follow-up expenses are eligible. |
| Restoration benefit | Read when the sum insured is restored and whether the same person or same illness can use it again. |
| Permanent exclusions | Some treatments or conditions may remain outside the scope of cover. |
| Premium structure | A policy needs to remain affordable enough to renew over many years, not just in the first year. |
The ₹8 Lakh Hospital Bill: Why Co-Pay Matters
Let us return to the opening example.
Assume the admissible hospitalisation claim is ₹8 lakh and the policy carries a 20% co-pay.
This is why two policies with similar sum insured can behave very differently when a real hospital bill arrives.
How Much Health Insurance Should Parents Have?
There is no single number that fits every parent above 60.
The required cover depends on:
- city of treatment
- preferred hospitals
- age
- medical history
- existing insurance
- co-pay and sub-limits
- how much of a hospital bill the family can fund itself
A parent using large private hospitals in Mumbai, Delhi or Bengaluru may face a different cost structure from someone mainly using hospitals in a smaller city.
When Does a Super Top-Up Fit In?
A common structure is a base health policy combined with a super top-up.
A super top-up generally starts paying after the aggregate eligible medical expenses considered under the policy cross the specified deductible during the policy year.
A plain top-up can work differently, with the deductible applying to each claim depending on the product wording.
This structure can increase protection for larger hospital bills while keeping the base policy in place.
What If Your Parents Already Have Diabetes, BP or Other Medical Conditions?
Diabetes, hypertension, thyroid disorders and other chronic conditions are common among older applicants.
Their presence affects how the proposal is underwritten, so disclosure becomes important.
Mention existing illnesses, medications, surgeries, hospitalisations and treatment history exactly as asked in the proposal form.
Pre-Existing Disease Waiting Period
A health policy can apply a waiting period before expenses linked to a declared pre-existing disease become payable.
Under the current health insurance framework, this waiting period can be up to 36 months of continuous coverage.
Why an Old Health Insurance Policy Can Be Valuable
An old policy carries something a fresh policy cannot recreate overnight: time.
Your parent may already have completed waiting periods, built continuity and crossed the moratorium period.
That history deserves to be checked before an old policy is replaced.
The 60-Month Moratorium
Once 60 continuous months of health insurance coverage are completed, including eligible portability and migration periods, the policy or claim generally cannot be contested on grounds of non-disclosure or misrepresentation except established fraud.
What Happens When the Sum Insured Is Increased?
Suppose your parent has held ₹5 lakh of cover for eight years and later increases it to ₹15 lakh.
The original ₹5 lakh keeps the continuity already built. The enhanced ₹10 lakh starts its own clock.
What Moratorium Actually Protects
Moratorium relates to contesting the policy or claim on specified disclosure grounds.
The normal policy conditions still apply, including:
- co-pay
- deductibles
- sub-limits
- permanent exclusions
- sum insured limits
- other contractual coverage conditions
What Changed for Health Insurance by 2026?
What About Premium Increases for Senior Citizens?
IRDAI introduced additional controls on premium revisions for indemnity-based individual health insurance products offered to senior citizens from 30 January 2025.
Insurers have been directed to keep annual premium revisions within 10% unless they first consult IRDAI under the prescribed process.
Prior consultation is also required before withdrawing an individual health insurance product offered to senior citizens.
Five Red Flags to Check Before Buying
Many problems are visible in the policy wording before a claim ever happens.
Six Questions to Ask Before Choosing Health Insurance for Parents
Final Takeaway
Health insurance for parents above 60 is really a claim-quality decision.
Start with the cover your parents already have and the continuity they have built.
Then compare the terms that decide what happens when they are hospitalised: co-pay, room eligibility, waiting periods, sub-limits, deductibles and hospital access.
If they are 70 years or older, also check Ayushman Vay Vandana.
If a large hospital bill arrives, how much of it is likely to be paid by the policy, and how much could still come from the family's pocket?
FAQs
1. Can I buy health insurance for my parents after age 60 or 65?
Yes. Health insurance products can be available beyond these ages. The proposal is assessed according to the product's eligibility rules, underwriting and the parent's medical history.
2. Do parents above 60 need a senior-citizen-specific health policy?
Not always. Regular retail plans may also accept older applicants. Compare the actual co-pay, room eligibility, waiting periods, sub-limits, hospital network and premium offered to your parent.
3. Should parents be included in my family floater?
It depends on the available sum insured, parents' health and how much shared cover the family is comfortable with. A separate parents' floater or individual policies may make more sense where the expected claim exposure is higher.
4. What is co-pay in senior citizen health insurance?
Co-pay is the percentage of an admissible claim that the insured has to bear. A 20% co-pay on an admissible ₹8 lakh claim means ₹1.6 lakh comes from the insured before considering other non-payable expenses.
5. Can parents with diabetes or high blood pressure get health insurance?
They may be able to, subject to underwriting and product terms. The medical condition, medication and treatment history should be disclosed accurately during the proposal process.
6. What is the maximum waiting period for pre-existing diseases?
Under the current health insurance framework, the waiting period for disclosed pre-existing diseases can be up to 36 months of continuous coverage.
7. What is the health insurance moratorium period in 2026?
The moratorium period is 60 continuous months. After this period, the policy or claim generally cannot be contested for non-disclosure or misrepresentation except established fraud. An enhanced sum insured starts its own moratorium period for the enhanced portion.
8. Are all senior citizens eligible for Ayushman Vay Vandana?
Senior citizens aged 70 years and above are eligible under the age-based expansion of AB PM-JAY irrespective of socio-economic status. Eligible hospitalisation cover is available up to ₹5 lakh per family per year.
9. Can someone with private health insurance also use Ayushman Vay Vandana?
Yes. An eligible senior citizen aged 70 years and above can still qualify even if they already hold private health insurance.
10. How quickly should a cashless health insurance request be processed?
Under the current IRDAI framework, cashless pre-authorisation should be decided within one hour of receiving the request. Final authorisation at discharge should be completed within three hours of receiving the hospital's request.