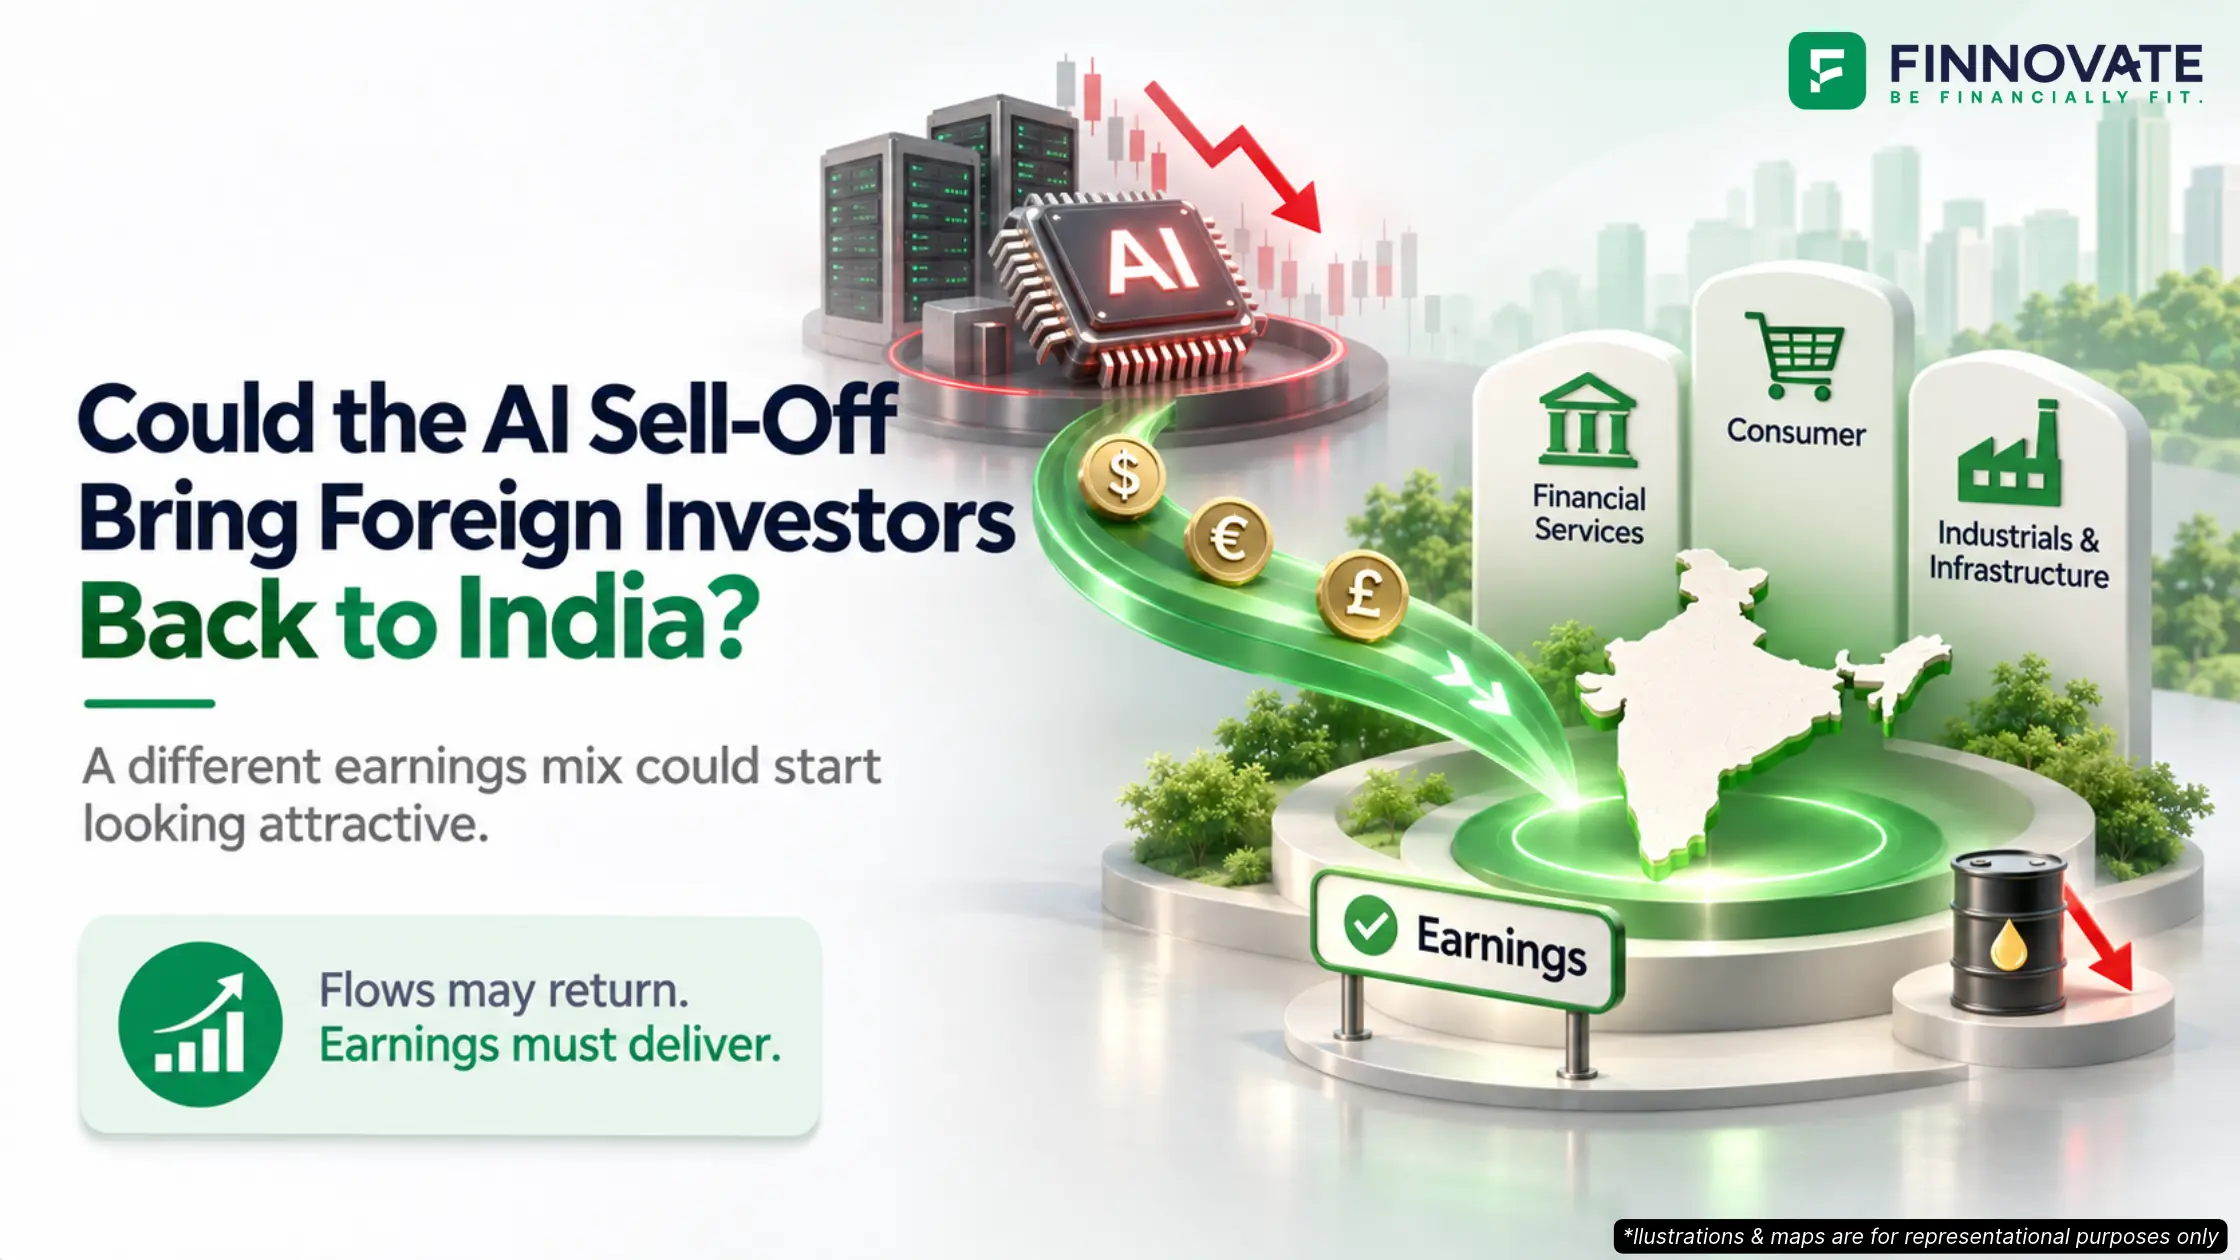
Could the AI Sell-Off Bring Foreign Investors Back to India?
Finnovate’s editorial team researches and creates financial content using trusted sources, regulatory references and inputs from subject experts.
For much of the AI boom, India had a problem: its stock market offered relatively few direct ways to own the companies building the hardware behind it.
Investors looking for advanced chips, memory and semiconductor manufacturing had more obvious destinations. India’s banks, consumer businesses and industrial companies were competing for attention with a global technology spending boom.
Now, that difference is getting another look.
Foreign investors bought a net $9.53 billion of Indian equities in November, according to figures reported on 16 November. That followed $31.41 billion of net selling between January and October.
Meanwhile, on 16 November, the Nasdaq Composite fell 2.49%, and the Philadelphia Semiconductor Index dropped 5.3%. Investors were reassessing risks across the AI industry ahead of Nvidia’s results.
The timing raises an interesting question. Is India becoming more attractive because its own prospects are improving, or because investors are becoming less comfortable with the alternatives?
The answer involves three forces coming together: exposure to AI, the price of oil and the profits Indian companies can deliver.
Why India Missed Part of the AI Rally
Investing in a technology often means buying the businesses that supply it.
An investor interested in AI infrastructure can buy companies that design processors, manufacture chips, supply memory or build servers. Their revenues have a relatively direct link to spending on computing capacity.
That opportunity is spread across several markets. A portfolio can hold companies in different countries while still depending heavily on one outcome: continued growth in AI investment.
India’s benchmark has a different mix.
At the end of October, financial services accounted for 37.13% of the Nifty 50, while information technology accounted for 8.80%. Its largest holdings included banks, alongside businesses in energy, telecom and construction.
Those companies earn money from different activities: lending, household spending, infrastructure, communication and other parts of the economy.
India’s IT services companies also operate differently from semiconductor manufacturers. They help clients build, maintain and change technology systems. Their business depends on client budgets, contracts, staffing and delivery costs, rather than simply the number of AI chips sold.
For a fund seeking direct exposure to the hardware boom, India offered fewer obvious choices. For a fund seeking to reduce its dependence on that boom, the same business mix can become useful.
A Fund Can Believe in AI and Still Reduce Its Exposure
Consider a global fund that owns a chip designer, a semiconductor manufacturer, a memory supplier and a data-centre business.
Four companies. Several countries. Yet much of the investment case rests on the same spending cycle.
If large technology companies slow their expansion, the consequences could travel across the portfolio. Orders, capacity use and expected profits may all come under pressure together.
Our article on what Nvidia’s troubles could mean for the AI industry explores those connections across the supply chain.
A fund manager may therefore decide to reduce exposure even while expecting AI use to keep growing. The question is whether the portfolio depends too heavily on that growth, and whether share prices already assume too much success.
Some of the money could move into businesses whose earnings depend more on domestic lending or consumption. Some could move into bonds or cash.
India becomes one possible destination because it offers a different set of businesses, rather than a different version of the same AI investment.
The November inflows fit that explanation. However, aggregate flow figures cannot trace a particular investor’s sale of an AI stock to a purchase in India. The case for a rotation rests on the combination of market behaviour, investor commentary and changes in relative appeal.
Cheaper Oil Gives Investors a Second Reason to Look
A market needs its own attractions to draw lasting investment. India’s oil bill is an important part of that case.
Brent crude settled at $92.44 a barrel on 16 November, down 3.6% that day. The International Energy Agency’s November outlook also projected a return to an oil-market surplus in the fourth quarter as supply recovered.
For an oil-importing economy, lower prices can help through several channels.
First, buying the same quantity of crude costs fewer dollars. That can ease pressure on the import bill and the demand for foreign currency.
Second, businesses may get relief on fuel and some petroleum-linked inputs. Airlines, transport businesses and certain manufacturers can benefit, although contracts, hedging and competition affect how quickly the savings reach profits.
Third, lower energy costs can ease some price pressures across the economy.
The scale of the import bill makes this relevant. As our October trade-deficit analysis explains, stronger exports can still leave a substantial shortfall when imports start from a much larger base.
Cheaper oil changes part of that equation. It gives investors a domestic economic reason to consider India alongside any desire to reduce exposure to AI stocks.
Foreign Investors Also Have to Think About the Rupee
An overseas investor measures returns in a home currency, often dollars.
Suppose an investment in Indian shares rises 10% in rupee terms. If the number of rupees needed to buy a dollar also rises 5%, the investor’s dollar return is about 4.8%, before costs and taxes.
The shares performed well, but the currency reduced the gain.
That is why foreign investors assess the rupee alongside earnings and valuations. A smaller oil bill can help India’s external position, while returning investment can bring additional foreign currency into the market.
These forces can support each other. Their strength still depends on other flows, global interest rates and demand for the dollar.
For a global fund, the investment decision is therefore broader than whether Indian shares might rise. It also involves what those returns could be worth after conversion.
Where Could the Interest Show Up?
India’s different sector mix offers several ways to invest beyond the AI hardware cycle. Each comes with its own business conditions.
| Area | Why it may attract attention | What still needs to deliver |
|---|---|---|
| Banks and financial services | Exposure to domestic lending and business activity | Loan growth, lending margins and credit quality |
| Consumer businesses and autos | Exposure to household spending | Sales volumes, pricing and profitability |
| Fuel-intensive businesses | Potential relief from lower operating costs | Savings reaching profits after hedging and competition |
| IT services | A business model different from chip manufacturing | Client spending, new contracts and adaptation to AI |
Scroll horizontally to view the full table.
Large, actively traded companies can be practical entry points for sizeable global funds. They allow managers to build or reduce positions more easily than many smaller stocks.
That can make a rally uneven. Strong interest in banks or other index heavyweights may lift the benchmark without producing the same result across the market.
For investors holding individual shares or mutual funds, the underlying businesses and portfolio mix remain more useful than the headline index alone.
India Still Has to Justify Its Price
A shift in global preferences can bring buyers back quickly. Earnings take longer to prove themselves.
The Nifty was trading at roughly 19 times expected earnings over the next 12 months in the 16 November market report, retaining a premium to Asian and emerging-market peers.
Investors paying that premium are making a judgement about future profits.
For banks, that may involve stronger lending without a deterioration in credit quality. For consumer businesses, it may require volume growth and better margins. For industrial companies, orders need to turn into revenue and cash.
Lower share prices earlier in the year may have improved some opportunities. Renewed buying can quickly change the price investors must pay for them.
A business can become more attractive relative to an AI stock and still be expensive in its own right. The comparison with other markets is only one part of the decision.
What Could Interrupt the Return?
The first risk is a broader retreat from equities.
A controlled reduction in AI exposure could benefit other markets. A severe sell-off could instead push investors towards cash and government bonds, leaving less money available for emerging markets generally.
The second is a reversal in oil or currency conditions. Renewed supply disruption could lift energy costs. A stronger dollar could reduce the appeal of rupee assets even when domestic companies perform reasonably well.
The third is disappointing earnings. If buying lifts share prices faster than profits, India’s valuation premium becomes harder to defend.
These are the tests that will reveal whether the current interest becomes a durable allocation or a shorter market move.
Flows Can Start a Rally. Earnings Must Carry It.
India’s limited direct exposure to the AI hardware boom may now offer something global investors want: a different source of earnings.
Cheaper oil adds to that appeal. Domestic businesses have an opportunity to support it through stronger profits and cash generation.
For Indian investors, the useful development is that the market is being assessed against a changing set of global alternatives. The quality and price of individual investments still matter.
A change in global preferences can bring investors back to India. What Indian companies earn will help decide how long they stay.
Sources
Disclaimer: This article is for information and education only and is not a recommendation to buy or sell any security. Market conditions can change, and investments are subject to market and currency risks.