Buying US Stocks? Your ETF Could Cost More Than the Shares Inside It
Finnovate’s editorial team researches and creates financial content using trusted sources, regulatory references and inputs from subject experts.
You buy an ETF to invest in US stocks. Over the next few months, the investments inside it rise by 10%.
Yet, when you sell, you lose money.
The explanation could lie in something you barely noticed while placing the order: the gap between what the ETF owns and what you paid for it.
An ETF listed on an Indian exchange can offer convenient access to US markets. You buy units through your existing demat account, pay in rupees and get exposure to an overseas portfolio.
But that convenience can come at a price. When demand for ETF units runs ahead of their available supply, the units can trade above the value of the investments backing them.
Buy at a sufficiently large premium, and a rising US market may still leave you with a loss.
One ETF, two different prices
An exchange-traded fund, or ETF, holds a portfolio of investments. Each unit represents a share of that portfolio.
Its net asset value, or NAV, per unit is calculated by subtracting the fund’s liabilities from its assets and dividing the balance by the number of outstanding units.
Suppose that works out to ₹100 per unit.
The price on your trading app is determined separately. Buyers and sellers place orders on the exchange, and their transactions establish the market price.
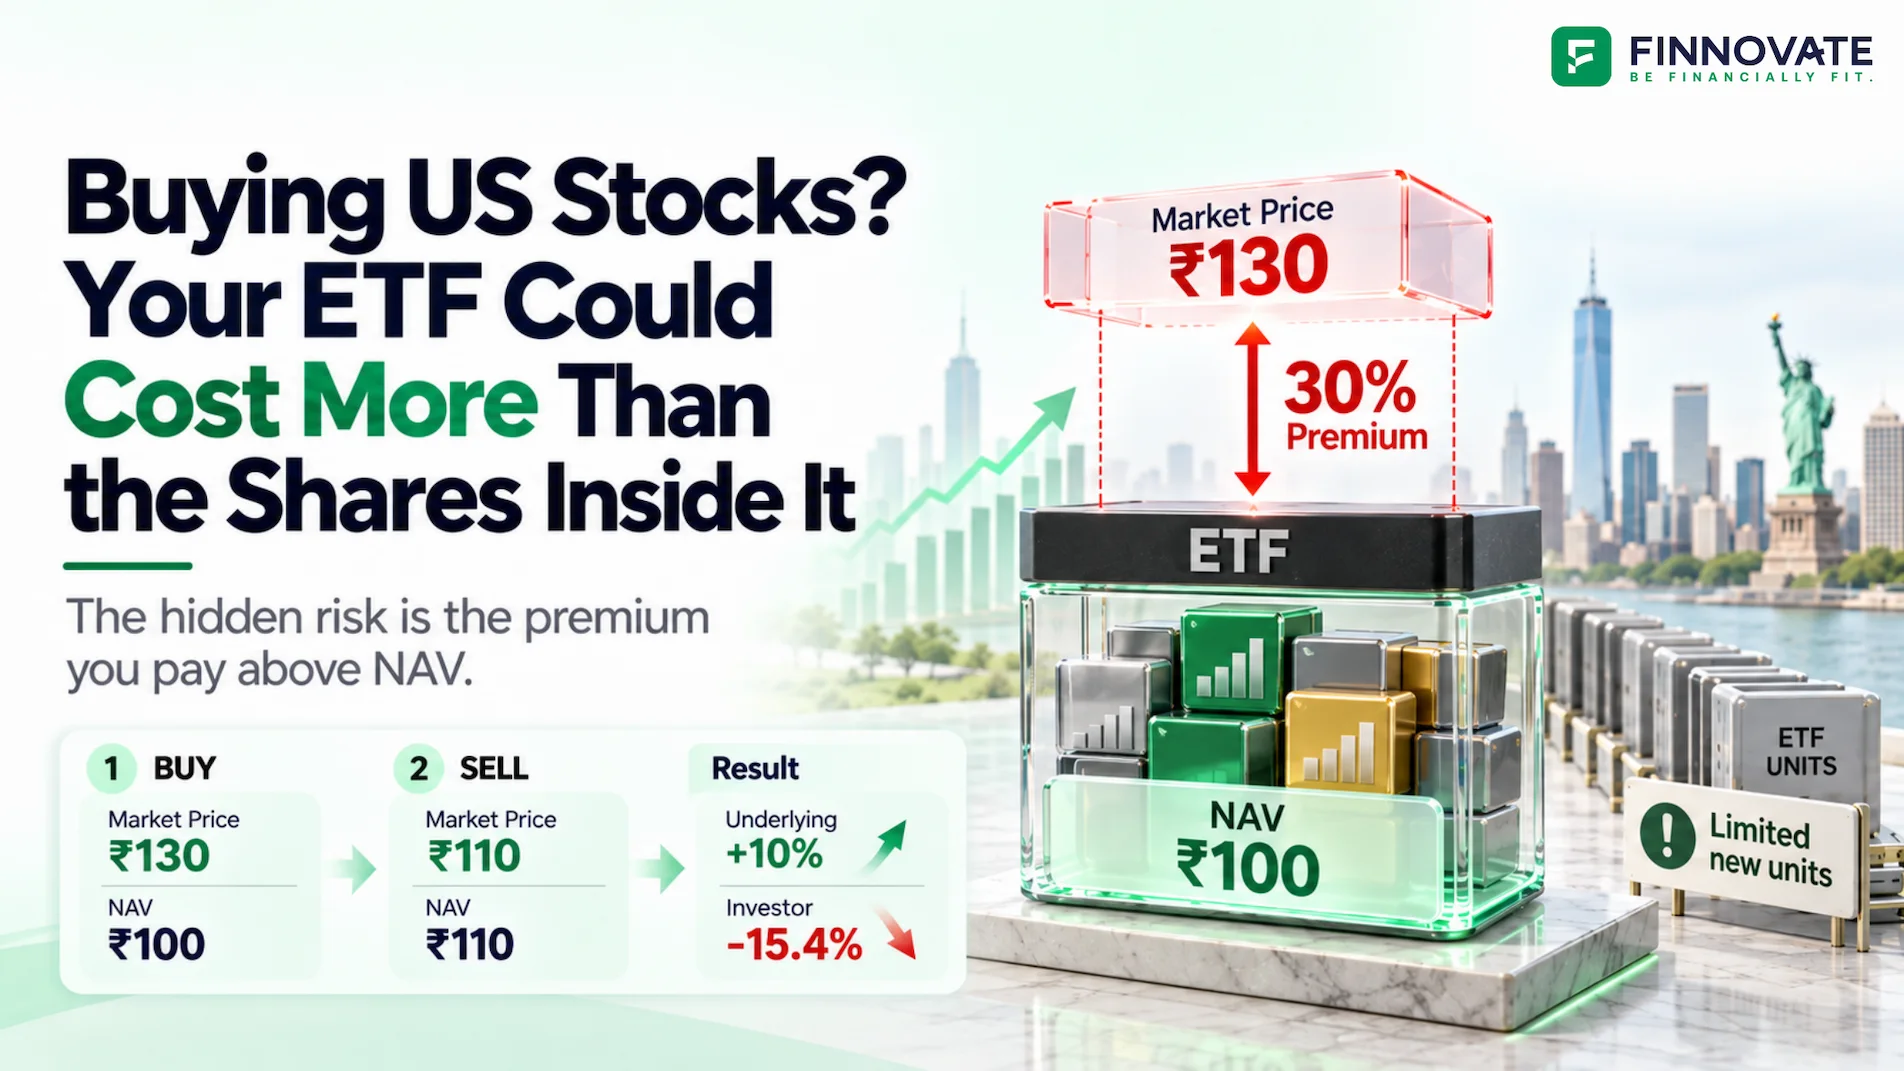
If buyers are willing to pay ₹130 for a unit with a NAV of ₹100, the ETF trades at a 30% premium to NAV.
You have paid ₹130 for a share of net assets valued at ₹100. The extra ₹30 buys you the same unit, with the same entitlement to the portfolio.
That difference matters when you eventually sell.
How a 10% gain can become a 15.4% loss
Consider this hypothetical example:
| Particulars | When you buy | When you sell |
|---|---|---|
| NAV per unit | ₹100 | ₹110 |
| Exchange price per unit | ₹130 | ₹110 |
| Premium to NAV | 30% | 0% |
↔ Scroll horizontally to view the full table.
The fund’s NAV increases from ₹100 to ₹110, delivering a 10% gain.
However, the premium disappears. Buyers are now paying ₹110 for the unit, matching its NAV.
Your investment falls from ₹130 to ₹110. You lose approximately 15.4%, before transaction costs and taxes, even though the NAV rises by 10%.
These are assumed rupee NAV values, so any currency effects are already included in the illustrated NAV movement.
The outcome depends on both the fund’s performance and the premium at which you enter and exit. If the premium stays unchanged, your price return can follow the NAV more closely. If it shrinks, it reduces your return. If it widens, it can temporarily boost your return.
This adds another moving part to an investment you might have bought simply to track US stocks.
Why doesn’t someone close the gap?
Usually, there is a mechanism that helps.
ETFs work with institutions called authorised participants and market makers. Subject to the scheme’s arrangements, authorised participants can obtain large blocks of fresh units from the fund against the required securities or cash.
When an ETF trades sufficiently above its underlying value, creating fresh units and selling them on the exchange can become profitable.
Those additional units increase supply. That selling pressure helps narrow the premium, after allowing for trading costs and other practical constraints.
But this process depends on the fund being able to create fresh units and make the necessary investments.
If fresh creation is restricted, buyers may have to compete for units already circulating on the exchange.
That is where India’s overseas-investment limits enter the story.
The overseas-investment bottleneck
Indian mutual funds operate within limits on how much they can invest overseas.
The framework includes an industry-wide ceiling of US$7 billion for overseas securities, with a US$1 billion limit per mutual fund. Investments in overseas ETFs have a separate industry-wide ceiling of US$1 billion, with a US$300 million limit per mutual fund.
The distinction matters. An Indian fund investing in a foreign-listed ETF uses a different category from one buying overseas shares directly.
When the applicable investment limit leaves insufficient room for fresh purchases, a scheme may restrict subscriptions or fresh ETF unit creation.
Existing ETF units can nevertheless continue changing hands on Indian exchanges. One investor sells, another buys, and the transaction transfers ownership of an existing unit.
So demand can keep growing even when the usual source of additional units is constrained.
On September 25, 2026, NSE warned that certain international ETFs were trading at substantial premiums despite broadly stable NAVs. It identified fully utilised overseas-investment limits and restricted fresh unit creation as the underlying problem.
An ETF’s rising exchange price can therefore reflect growing demand for scarce units, even when the portfolio itself has barely moved.
The premium can fall before US stocks do
A premium depends on buyers continuing to pay above the underlying value.
Fresh unit creation becoming available could increase supply. Demand could also weaken as investors become less willing to pay the extra amount.
Either development could narrow the gap between price and NAV.
NSE’s warning specifically highlighted the possibility of an abrupt price decline unrelated to movements in the underlying investments.
For someone buying at a large premium, this creates an uncomfortable possibility: US stocks could remain steady, but the ETF’s exchange price could fall.
The timing is uncertain. Premiums can persist or grow further before shrinking. A long holding period also provides no assurance that the premium paid at entry will still be available at exit.
A low expense ratio leaves another cost to check
Investors often compare ETFs by their annual expense ratios. That is useful because recurring expenses affect the fund’s returns.
But an expense ratio and a premium measure different things.
The expense ratio is an ongoing fund cost. The premium is the additional amount you pay above the unit’s underlying net asset value.
There is also the bid–ask spread, the difference between the highest price a buyer is offering and the lowest price a seller is asking.
A fund can have a low annual expense ratio while being expensive to buy on the exchange because of a large premium or a wide spread.
The same distinction applies when reviewing past performance. Check whether the return shown represents the fund’s NAV or its traded price. A strong exchange-price return may partly reflect an expanding premium, which adds no assets to the portfolio.
Before placing the order
A few checks can help you understand what you are paying for.
1. Compare the available purchase price with NAV or iNAV.
Look at the seller’s asking price for the quantity you intend to buy. The last traded price may relate to an earlier transaction and may no longer be available.
Use the AMC’s or exchange’s published NAV and, where available, indicative NAV, or iNAV, as reference points.
2. Check the timestamps.
Indian and US trading hours differ. A published NAV may reflect an earlier US market close, while an Indian exchange price may already incorporate newer expectations.
iNAV is also an estimate. Fund providers flag possible delays and differences caused by market timings, data sources and technical issues. Treat a price comparison in that context.
3. Read the latest fund notices.
Check whether fresh unit creation is operating normally or is restricted. This helps explain why the usual process for narrowing a premium may be weakened.
4. Calculate the apparent premium.
The calculation is:
Premium (%) = [(Market price ÷ NAV per unit) − 1] × 100
Use appropriately timed values. Comparing unrelated timestamps can produce a misleading result.
5. Decide your purchase price before placing the order.
A limit order sets the maximum you are willing to pay, although execution is not guaranteed. The limit still needs to be sensible relative to the fund’s value. Setting a limit at an inflated price preserves the overpayment.
Buying the market also means checking the price
An India-listed ETF can make overseas investing accessible. Its exchange listing gives investors a way to buy and sell units even when fresh subscriptions elsewhere are restricted.
But access and value are separate considerations.
Before buying, there are two questions to answer: Do you want to own these investments, and how much extra are you paying to own them through this ETF?
The first shapes your portfolio. The second can determine how much of the portfolio’s return reaches you.
Even a sound investment idea can become an expensive purchase.
Sources
- National Stock Exchange: Trading in International Exchange Traded Funds, September 25, 2026 - Warning on premiums and restricted creation of international ETF units.
- Scheme information document filed with SEBI - Overseas-investment limits and restrictions when available limits are exhausted.
- US Securities and Exchange Commission, Investor.gov: Updated Investor Bulletin on ETFs - ETF creation and redemption, NAV, market prices, premiums and bid–ask spreads.
- Mirae Asset: Indicative NAV disclosures - Market-timing limitations and exchange execution considerations.
Disclaimer: This article is for general information and education and does not constitute investment advice or a recommendation to buy or sell any security. The numerical example is hypothetical. Mutual fund investments are subject to market risks; read all scheme-related documents carefully.