India Semiconductor Industry 2026: Why the Ecosystem Matters Beyond Fabs
India’s semiconductor push is expanding beyond fabs. See how Applied Materials, Tata, Ne...
18 September 2026
Finnovate’s editorial team researches and creates financial content using trusted sources, regulatory references and inputs from subject experts.
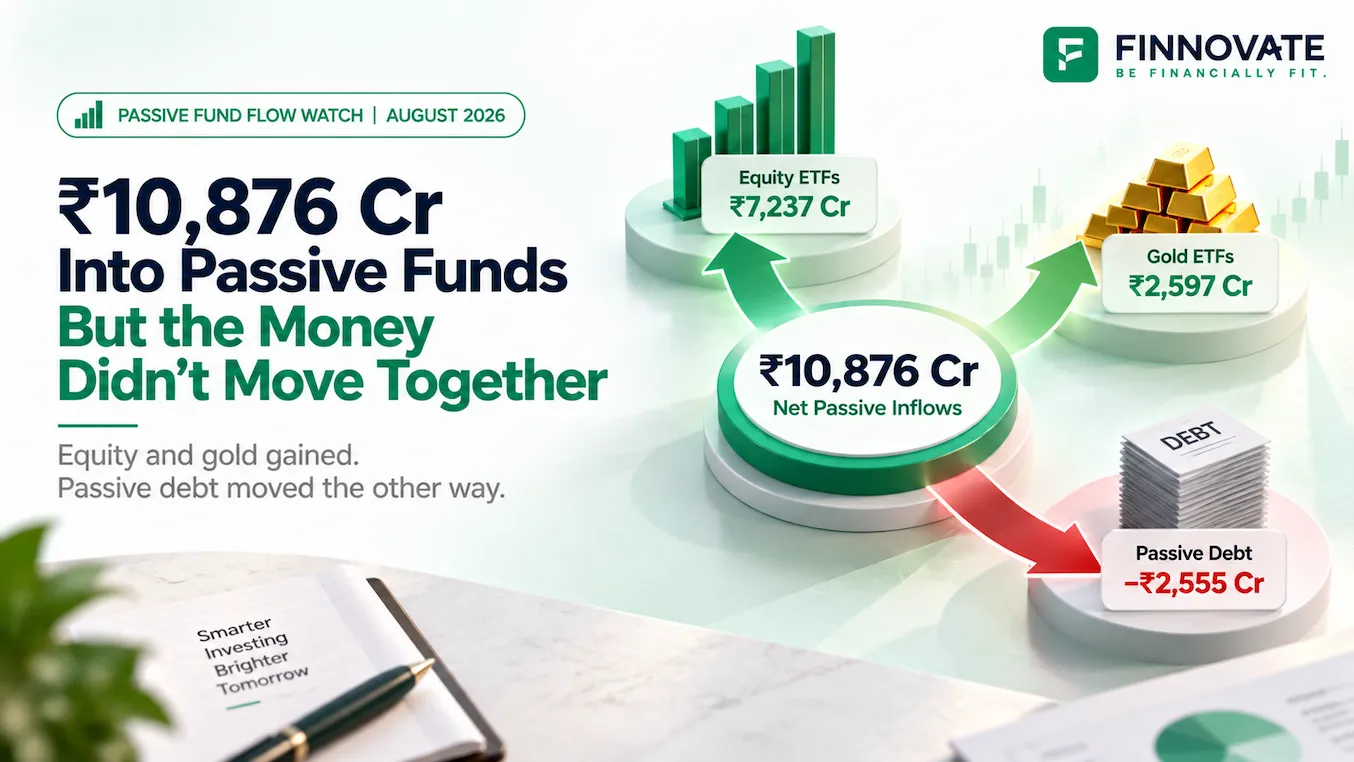
India's passive mutual fund market received ₹10,876 crore of net inflows in August 2026.
At first glance, that sounds like a reasonably strong month. But the headline number hides a much more interesting split.
Equity ETFs, equity index funds, gold ETFs and silver ETFs together received almost ₹13,498 crore. At the same time, passive debt products lost roughly ₹2,555 crore, while overseas Fund of Funds also ended the month in outflow.
So August was not simply a month when money entered passive funds.
It was a month when investors used different passive products in very different ways.
Table of Contents
Total passive-fund net inflows declined from approximately ₹12,517 crore in July to ₹10,876 crore in August, a month-on-month fall of about 13%. Passive AUM, however, increased from about ₹15.61 lakh crore to ₹15.90 lakh crore over the same period.
That distinction is important.
AUM can increase because investors add money, because the securities already held by funds rise in value, or because of both.
August-end passive AUM of around ₹15.90 lakh crore was equivalent to roughly 18% of the Indian mutual fund industry's ₹87.08 lakh crore of total AUM. AMFI reported industry-wide AUM of ₹87.08 lakh crore as of August 31, 2026.
Passive investing is therefore no longer a small corner of India's mutual fund industry. But within that ₹15.9 lakh crore market, August's flows were anything but uniform.
The main August categories show the divergence clearly.
| Passive Category | Gross Flows | Net Flows | August AUM | Flow Conversion | Flow Intensity |
|---|---|---|---|---|---|
| Equity ETF | ₹10,365 cr | ₹7,237 cr | ₹8.18 lakh cr | 69.83% | 0.88% |
| Gold ETF | ₹3,791 cr | ₹2,597 cr | ₹1.91 lakh cr | 68.49% | 1.36% |
| Equity Index Funds | ₹6,885 cr | ₹2,393 cr | ₹2.51 lakh cr | 34.76% | 0.95% |
| Silver ETF | ₹4,029 cr | ₹1,271 cr | ₹85,488 cr | 31.54% | 1.49% |
| Overseas FoF | ₹248 cr | -₹72 cr | ₹48,548 cr | -29.10% | -0.15% |
| Debt ETF | ₹7,716 cr | -₹945 cr | ₹95,324 cr | -12.25% | -0.99% |
| Debt Index Funds | ₹3,243 cr | -₹1,610 cr | ₹93,560 cr | -49.63% | -1.72% |
Source: AMFI data reproduced in the August passive-fund dataset. Smaller Hybrid ETF, Hybrid Index Fund, overseas ETF and Other ETF categories are excluded here because their very small flow or AUM bases can distort percentage comparisons.
Four categories did most of the positive work.
That is higher than the entire passive industry's ₹10,876 crore net inflow because several other categories were simultaneously experiencing withdrawals.
This is the first clue that “passive-fund inflow” is becoming too broad a label to tell investors very much on its own.
Net inflow tells us how much money ultimately entered or left a category during a month.
But ₹2,000 crore can mean something very different for a category managing ₹50,000 crore than for one managing ₹5 lakh crore.
Two additional ratios can help.
Net flow ÷ gross mobilisation
Suppose investors make ₹100 crore of purchases into a category while ₹40 crore is redeemed. The category records ₹60 crore of net inflows, so its Flow Conversion is 60%.
Net flow ÷ category AUM
This compares the month's flow with the existing size of the category and helps show how meaningful the flow was relative to the existing asset base.
Flow Conversion does not mean the category literally “retained” a certain percentage of the money invested that month. Redemptions could have come from investments made several years earlier.
It simply shows how much of gross purchasing activity translated into net accumulation after redemptions.
Gold ETFs, for example, received nearly ₹2,597 crore in August against AUM of around ₹1.91 lakh crore.
That gives a Flow Intensity of about 1.36%.
Used together, these ratios help distinguish between a large absolute inflow and one that is also meaningful relative to existing assets.
The August dataset also demonstrates why ratios should not be ranked mechanically.
Hybrid ETFs recorded:
That produces:
On percentages alone, Hybrid ETFs appear stronger than every major passive category.
But ₹1 crore of net flow is clearly not more consequential to India's passive market than ₹7,237 crore entering equity ETFs.
The same issue appears in Hybrid Index Funds, where ₹4.21 crore of net inflow looks significant primarily because the category's AUM was only about ₹84 crore.
Equity ETFs attracted:
while equity index funds received:
Together, passive equity products brought in approximately:
That is equivalent to about 88.5% of August's final passive-fund net inflow.
The comparison is not a conventional market-share calculation because outflows in other categories reduce the overall denominator. But it still illustrates just how important passive equity was to August's positive total.
Equity ETFs alone manage approximately ₹8.18 lakh crore, making them the largest category in the passive universe and accounting for slightly more than half of total passive AUM.
Demand also strengthened from July.
Domestic equity-oriented ETFs had received about ₹6,824 crore in July, implying roughly a 6% month-on-month increase in August. Equity index fund flows remained relatively steady, easing from about ₹2,469 crore in July to ₹2,393 crore in August.
Passive equity demand therefore remained broadly firm.
Gold ETFs received approximately:
in August, compared with:
in July.
That is a jump of almost 67% in one month.
Gold ETF AUM also climbed to approximately ₹1.91 lakh crore from around ₹1.73 lakh crore in July.
But not all of that AUM increase came from investors adding money.
Gold prices rose about 7.7% during August, meaning existing ETF holdings also increased in value.
AUM reflects both flows and market movements.
Silver ETFs attracted approximately ₹1,271 crore in August.
July's inflow had been approximately ₹1,285 crore, meaning fresh buying was broadly unchanged month-on-month.
Yet Silver ETF AUM increased from around ₹77,676 crore in July to approximately ₹85,488 crore in August.
So August produced two different precious-metal stories.
Fresh investor buying accelerated sharply.
Fresh buying remained broadly stable, while the value of existing assets contributed significantly to higher AUM.
Treating both categories simply as “precious-metal inflows” would miss that difference.
Another way of looking at August is by product structure.
ETFs as a group received approximately:
of net inflows during August.
That represents around 93% of the final ₹10,876 crore passive-fund net inflow.
Index funds, after including positive equity flows and negative debt flows, contributed a much smaller net amount.
But even here, the ETF label should not be confused with one investment strategy.
An equity ETF, gold ETF, silver ETF and debt ETF are all exchange-traded passive products, but their underlying risks and return drivers are completely different.
August's clearest weak spot was debt.
Debt ETFs recorded:
while debt index funds recorded:
Together:
The change in Debt ETFs was particularly notable because they had received approximately ₹1,389 crore of inflows in July.
That means Debt ETF flows swung by more than ₹2,300 crore between the two months.
Debt index funds had already been weaker in July, with Target Maturity Index Funds recording around ₹959 crore of outflows.
So August showed broader weakness across passive debt, but it would be premature to describe this as a permanent investor exit.
There is a reasonable economic explanation for weaker debt demand, but the flow data itself cannot prove investor motivation.
When market interest rates and bond yields rise, prices of existing fixed-rate bonds generally fall.
Longer-duration bonds tend to be more sensitive to these moves.
So if investors expect inflation and interest rates to stay higher, some debt products can face near-term mark-to-market pressure.
August was also a weak month for debt mutual funds more broadly.
Across the mutual fund industry, debt-oriented schemes recorded approximately ₹8,127 crore of net outflows during August.
Passive debt therefore did not weaken in isolation.
That is different from saying the data proves investors sold passive debt specifically because they expect the RBI to raise rates.
Debt ETF flows have changed direction repeatedly.
Approximate net flows were:
| Month | Debt ETF Net Flow |
|---|---|
| June 2026 | +₹375 cr |
| July 2026 | +₹1,389 cr |
| August 2026 | -₹945 cr |
June and July therefore showed positive flows before August's reversal.
Debt index funds have shown more persistent weakness, but even within debt there are different maturity profiles and structures.
So August supports the conclusion that passive debt was weak that month.
It does not yet establish a permanent rotation out of debt.
Fund of Funds investing overseas recorded a relatively modest:
in August.
Indian mutual funds investing abroad continue to operate within industry-wide overseas-investment limits, which can restrict fresh deployment or subscriptions in some international schemes.
Those limits remain an important structural constraint on the category.
But August's ₹72 crore outflow is not large enough to conclude that restrictions alone caused investor withdrawals.
Market performance, product availability, portfolio allocation and existing scheme restrictions can all play a role.
Passive assets increased from approximately:
to:
an increase of roughly 1.9%.
Yet net monthly inflows actually fell around 13%.
That is another reminder that the two data points answer different questions.
Where investor money moved during the month.
How much money the category manages after both investor flows and changes in asset values.
A category can therefore have slower inflows and still finish the month with higher AUM.
For investors studying mutual-fund trends, these should never be treated as interchangeable measures.
August's ₹10,876 crore net inflow was not evenly spread across India's passive-fund market.
Equity ETFs remained the largest source of fresh money. Gold ETF buying accelerated sharply. Silver demand stayed strong. Equity index funds continued receiving meaningful allocations.
Passive debt moved in the opposite direction.
That produces a broader lesson.
A Nifty index fund gives equity-market exposure.
A Gold ETF tracks gold.
A Silver ETF carries commodity exposure.
A debt index fund owns fixed-income securities.
An international index fund introduces overseas-market and currency exposure.
All five can be passive funds, yet they can behave completely differently at exactly the same time.
That is what August demonstrated.
For investors, the useful question is therefore not:
It is:
Monthly flow data can show where investor demand is moving.
It should not determine asset allocation by itself.
Passive-fund categories recorded approximately ₹10,876 crore of net inflows in August 2026.
Equity ETFs led with approximately ₹7,237 crore, followed by Gold ETFs at ₹2,597 crore and equity index funds at ₹2,393 crore.
Equity ETFs and equity index funds together received approximately ₹9,630 crore of net inflows during August.
Gold ETFs received ₹2,596.70 crore in August, nearly 67% higher than July's ₹1,558.75 crore. Gold prices also rose during the month, although price appreciation affects AUM rather than being counted as a net inflow.
Yes. Debt ETFs recorded around ₹945 crore of outflows, while debt index funds saw approximately ₹1,610 crore of outflows, taking combined passive-debt withdrawals to roughly ₹2,555 crore.
Flow Conversion compares net flows with gross mobilisation and indicates how much gross purchasing translated into net accumulation after redemptions. Flow Intensity compares the month's net flow with the category's AUM to show how large the flow was relative to the existing asset base.
No. Fund-flow data describes investor behaviour, not future returns. Asset allocation should depend on the investor's goals, time horizon, risk capacity and existing portfolio rather than which category received the highest recent inflows.
Disclaimer: This article is for educational and informational purposes only. Mutual-fund flows, AUM and recent investor behaviour should not be treated as investment recommendations or indicators of future performance. Investors should consider their financial goals, risk capacity and asset allocation before making investment decisions.
No spam. Only new posts, simple explainers, and practical money checklists for busy professionals.
Finnovate is a SEBI-registered financial planning firm that helps professionals bring structure and purpose to their money. Over 3,500+ families have trusted our disciplined process to plan their goals - safely, surely, and swiftly.
Our team constantly tracks market trends, policy changes, and investment opportunities like the ones featured in this Weekly Capsule - to help you make informed, confident financial decisions.
Learn more about our approach and how we work with you:
No comments yet. Start the conversation. What would you add?
No spam. Only new posts, simple explainers, and practical money checklists.
You may also like
India’s semiconductor push is expanding beyond fabs. See how Applied Materials, Tata, Ne...
The US Fed raised rates by 25 bps to 3.75%-4.00% in September 2026. See why it hiked, what...
India’s 10-year bond yield is near 7.1%. Understand why yields are rising and what it me...
India’s BRICS trade reached $417.5 billion in FY2026, but the deficit widened to $226.1 ...
Popular now
Learn how to easily download your NSDL CAS Statement in PDF format with our step-by-step g...
Looking for the best financial freedom books? Here’s a handpicked 2026 reading list with...
Learn what SIF investment means in India, SEBI rules, Rs 10 lakh minimum investment, avail...
Clear guide to mutual fund taxation in India for FY 2025–26 after July 2024 changes: equ...