India’s BRICS Trade Deficit Hits $226 Billion: What’s Driving It?
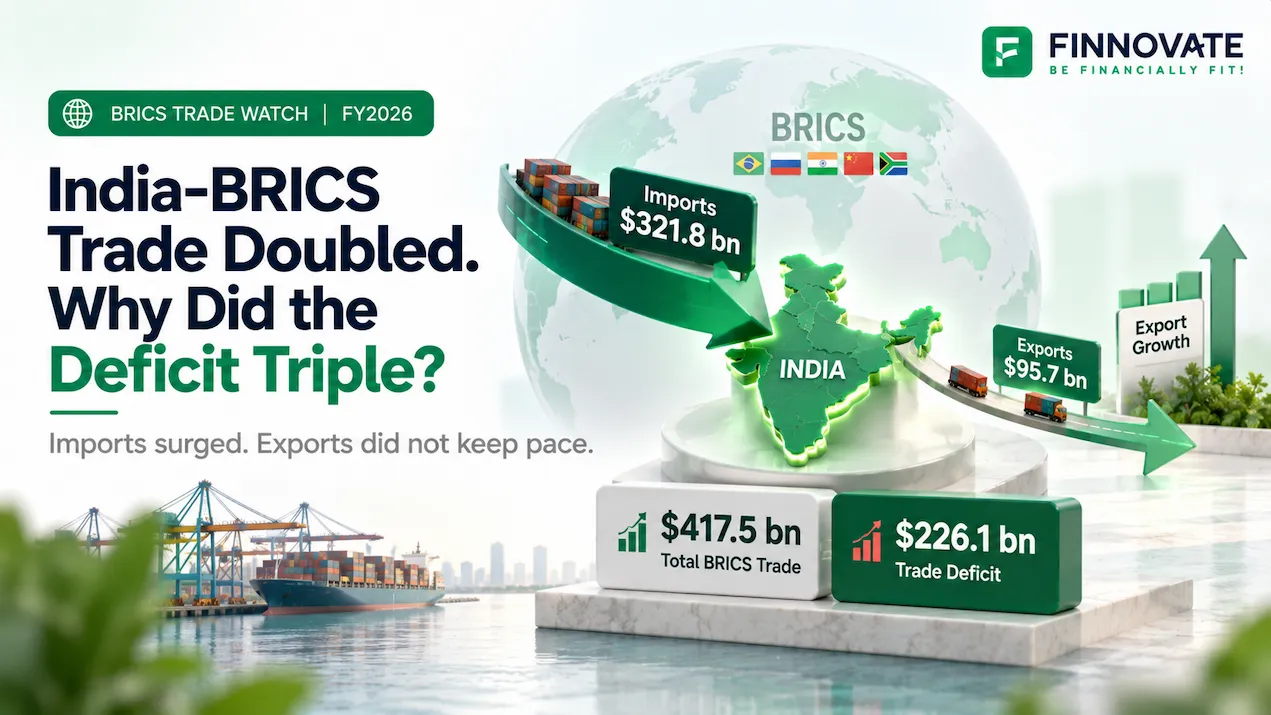
India’s BRICS trade reached $417.5 billion in FY2026, but the deficit widened to $226.1 ...
15 September 2026
Finnovate’s editorial team researches and creates financial content using trusted sources, regulatory references and inputs from subject experts.
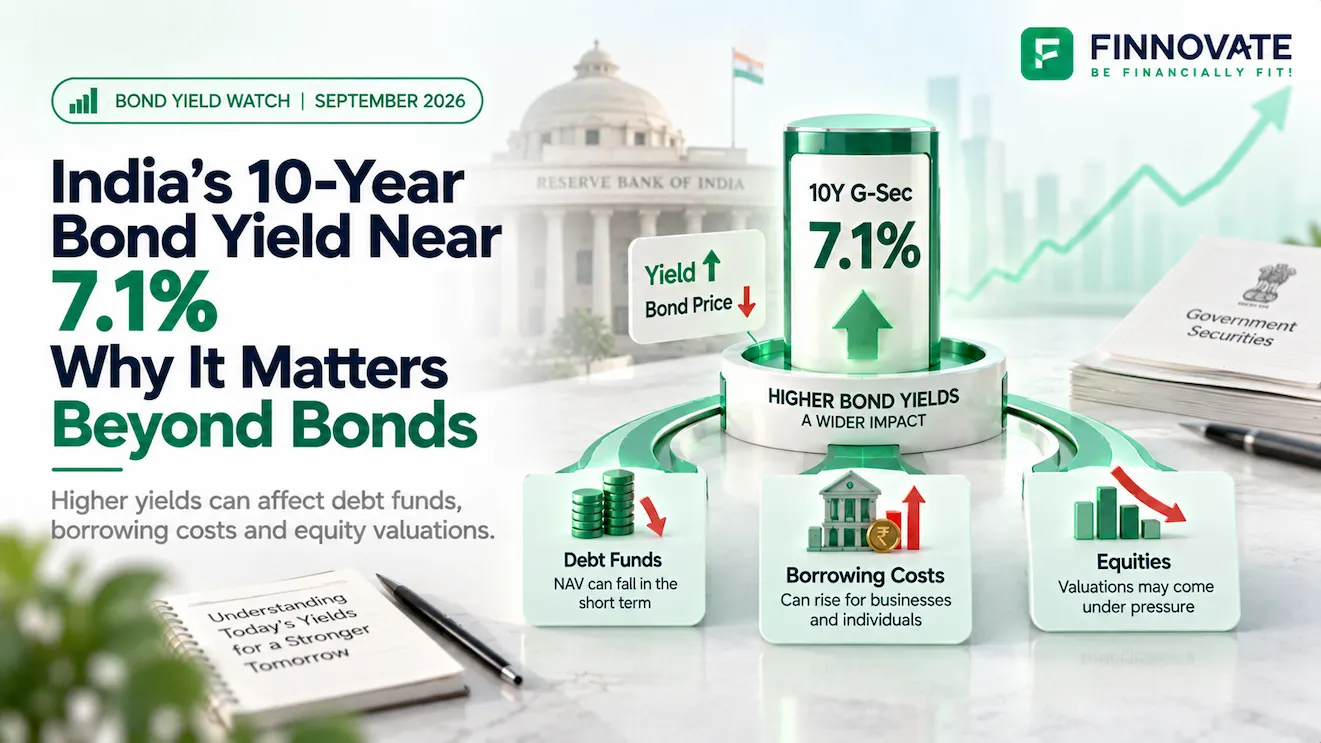
India's benchmark 10-year government bond yield has climbed back to around 7.1%, reaching 7.09% on September 15, its highest level since May. That is happening even though the RBI's repo rate remains at 5.25%.
The move is important because the 10-year government bond yield is more than a number followed by bond traders. It acts as an important reference rate for borrowing costs and asset valuations across the economy.
A sustained rise can affect government borrowing, corporate bonds, debt mutual fund NAVs and even equity valuations. At the same time, higher yields can eventually benefit investors putting fresh money into fixed-income products.
So the real question is not simply whether rising bond yields are good or bad.
Table of Contents
Suppose the government issues a bond that pays ₹7 every year on a face value of ₹100.
At ₹100, its yield is roughly 7%.
Now imagine new bonds start offering higher returns. Investors will be less willing to pay ₹100 for an older bond paying only ₹7.
Its market price therefore falls until the return available to a new buyer becomes competitive with current market yields.
This inverse relationship is especially important for longer-duration bonds because their prices are generally more sensitive to changes in interest rates.
That is why a move in the 10-year government yield matters even to investors who have never directly purchased a government bond.
There is no single reason.
The current move reflects a combination of domestic inflation, oil prices, global bond yields, expectations about RBI policy and the RBI's own liquidity-management operations.
India's CPI inflation rose to 4.82% in August 2026, up from 4.45% in July. Food inflation rose further to 5.95%. August was the third consecutive month in which headline inflation remained above the RBI's 4% medium-term target.
Bond investors care deeply about inflation because the return they receive is fixed in nominal terms.
If a bond yields 7% while inflation is 3%, the investor earns a much healthier real return than when inflation itself moves towards 5% or 6%.
Higher expected inflation therefore usually leads investors to demand a higher yield.
Brent crude was trading around $108 per barrel on September 15, after supply disruptions and geopolitical tensions pushed prices sharply higher.
For India, which imports most of its crude-oil requirement, expensive oil matters through several channels.
It can raise the import bill, put pressure on the rupee and eventually feed into transport, production and broader inflation.
So higher oil prices can increase expectations that monetary policy may need to remain tighter.
India is not facing this move in isolation.
The US 10-year Treasury yield crossed 5% on September 15, reaching levels last seen around the global financial crisis era before easing below that mark on September 16. Rising inflation concerns, large government borrowing requirements and expectations of tighter monetary policy have pushed yields higher across several major economies.
That matters for India because global investors compare returns across countries.
If US government bonds themselves offer close to 5%, Indian bonds need to offer enough additional return to compensate investors for currency and emerging-market risks.
There is also a domestic liquidity factor.
India's banking system became highly liquid after banks raised around $127 billion through the RBI's special foreign-currency mobilisation scheme. The additional dollars entered the RBI's reserves, while rupee liquidity was released into the banking system.
That created another problem: too much liquidity can push short-term market rates below the RBI's desired policy range and potentially add to inflationary pressure.
To absorb some of this money, the RBI announced that it would sell ₹1 lakh crore of government securities through open-market operations in September.
But those bond sales also increase the amount of government securities available to the market.
More supply can put downward pressure on bond prices.
And when bond prices fall:
So today's movement in Indian yields is not being driven by inflation alone. It is also connected to how the RBI is reversing some of the excess liquidity generated earlier in the year.
The repo rate is still 5.25%.
But after the August CPI number and the sharp rise in oil prices, expectations have changed.
Reuters reported that Citi and Deutsche Bank moved their forecasts for the next RBI rate increase forward from December to October. The market has also started assigning greater probability to an earlier hike.
That does not mean an October hike is certain.
The RBI will still be watching food prices, oil, the rupee, economic growth and subsequent inflation readings.
But government bond markets generally move ahead of central-bank decisions.
If investors believe future rates will be higher, long-term bond yields can rise before the RBI actually changes the repo rate.
For debt-fund investors, this is one of the most important effects.
A debt mutual fund owns a portfolio of bonds.
When market yields rise, the prices of existing bonds fall. That decline is reflected in the market value of the fund's portfolio and therefore its NAV.
The impact is not equal across all debt funds.
A bond paying a fixed coupon for another ten or fifteen years becomes more sensitive when prevailing interest rates change.
Long-duration and gilt funds can therefore experience larger NAV movements when yields rise sharply.
Bonds approaching maturity are less affected because investors receive their principal back sooner and the money can be reinvested at current market rates.
This generally makes shorter-duration portfolios less sensitive to changes in yields.
This is the other side of the story.
A rise in yields hurts the price of bonds already sitting inside a portfolio.
But it also means that new bonds are available at higher yields.
As existing securities mature, fund managers can reinvest money at more attractive rates.
That distinction is important because rising yields are not universally negative for debt investors.
Not immediately.
A floating-rate home loan does not mechanically become more expensive just because India's 10-year government bond yield rises.
Many retail floating-rate loans are linked to the RBI repo rate, an external benchmark or a bank's own lending benchmark.
If those rates do not change, the borrower's EMI may not change immediately.
Government bond yields matter more directly for market-based borrowing.
Companies issuing bonds may need to offer investors higher yields. The government may also have to borrow at higher rates when issuing new securities.
If elevated market rates persist, higher funding costs can gradually pass through the financial system and eventually influence lending rates.
India's government regularly borrows through bonds to finance spending and refinance existing debt.
If investors demand a higher yield, new borrowing becomes more expensive.
The same principle applies to companies raising money through corporate bonds.
A business that could earlier issue debt at 7.5% may have to offer a higher rate when the risk-free government benchmark itself has moved upwards.
That higher financing cost can affect:
The effect becomes particularly important for highly leveraged businesses or companies that need to borrow frequently.
Banks and insurance companies are major investors in government securities and other fixed-income instruments.
When yields rise, the market price of their existing long-duration bonds falls.
This can create mark-to-market pressure.
However, the actual accounting impact is more complicated than simply saying every fall in bond prices becomes a loss in quarterly profits.
The effect depends on how securities are classified and accounted for, and some holdings are treated differently from portfolios that are continuously marked to market.
Government bonds and equities may appear unrelated, but bond yields influence how investors value businesses.
There are three important channels.
Businesses refinancing loans or issuing new bonds may have to pay higher interest rates.
That can increase interest expense and reduce profits.
Equity valuation is ultimately based on the value today of profits and cash flows expected in the future.
If the risk-free rate rises, the discount rate used to value those future cash flows generally rises too.
And when the discount rate rises:
This can put pressure on valuation multiples even if the company's operating business has not changed.
Companies whose expected earnings are concentrated far into the future can be particularly sensitive.
A government bond offering around 7% can look more attractive than one offering 6%.
That does not mean investors automatically sell equities whenever bond yields rise above a company's earnings yield.
Equities offer earnings growth and potential capital appreciation but also carry considerably more risk.
Still, higher risk-free yields raise the return investors may demand before taking additional equity risk.
That is one reason sustained increases in bond yields can create pressure on expensive equity valuations.
Potentially, but foreign investors look at more than the headline Indian yield.
India's 10-year bond yields around 7.1%.
The US 10-year Treasury has recently traded around 5%.
That gives India an additional nominal yield of only around two percentage points.
A foreign investor then has to consider the rupee.
The currency weakened to around ₹95.96 per US dollar on September 15, with high crude prices and global interest rates adding pressure.
Suppose an overseas investor earns 2 percentage points more by buying an Indian bond instead of a US Treasury.
If the rupee subsequently depreciates significantly against the dollar, part or all of that yield advantage can disappear when the investment is converted back into dollars.
Currency hedging can reduce that risk, but hedging itself has a cost.
That is why higher Indian yields do not automatically translate into stronger foreign inflows.
At the same time, it would also be incorrect to say foreign investors have avoided Indian bonds.
Foreign demand has been meaningful in 2026, supported by attractive yields and India's growing presence in global bond indices.
The relationship is therefore more nuanced: a higher yield improves the entry point, but total returns still depend heavily on the rupee and global rates.
A rising yield environment creates winners as well as losers.
| Area | Impact of Higher Bond Yields |
|---|---|
| Existing long-duration bonds | Prices can fall |
| Long-duration debt funds | NAVs can face more pressure |
| Fresh fixed-income investors | Higher entry yields become available |
| Government borrowing | New borrowing can become costlier |
| Corporate bonds | Companies may have to pay higher rates |
| Floating retail loans | No automatic immediate increase |
| Equity valuations | Higher discount rates can reduce valuations |
| Foreign bond investors | Better yields, but currency risk still matters |
For someone already holding a long-duration bond, rising yields can be uncomfortable.
For someone waiting to deploy fresh money into fixed income, the same move can create a more attractive starting yield.
Context matters.
The next few weeks could determine whether India's 10-year yield settles around current levels or moves higher again.
The main variables are:
A decline in oil prices or inflation expectations could reduce pressure on yields.
Persistent inflation, further global bond selling or expectations of additional RBI tightening could have the opposite effect.
India's 10-year bond yield is effectively one of the economy's important prices for long-term money.
When it moves sharply, the impact does not remain confined to government bonds.
It can affect the NAV of a debt fund, the rate at which a company borrows, the government's interest bill and the discount rate investors use to value equities.
The current move towards 7.1% is particularly noteworthy because several forces are operating simultaneously: inflation is above target, oil is above $100, global yields have surged and the RBI itself is draining liquidity through bond sales.
For existing bond investors, that creates mark-to-market pressure.
For borrowers, it can mean a higher future cost of capital.
For equity investors, it increases the rate against which future returns are judged.
But for fresh fixed-income investors, higher yields can also create better opportunities than were available when bond prices were higher.
India's benchmark 10-year government bond yield rose to around 7.09% on September 15, 2026, its highest level since May.
The rise reflects several factors, including higher CPI and food inflation, crude oil above $100 per barrel, rising global bond yields, expectations of possible RBI tightening and RBI bond sales aimed at removing excess banking-system liquidity.
Existing bonds offer fixed coupon payments. When new bonds become available at higher market yields, older bonds become less attractive unless their market prices fall enough to offer a competitive effective return.
They can create short-term NAV pressure, especially for long-duration funds. However, higher yields also allow fresh investments and future reinvestments to earn potentially better yields.
Not automatically. Floating home-loan rates are usually linked to the repo rate or other lending benchmarks rather than directly to the 10-year government bond yield. Persistent increases in market funding costs can, however, influence lending rates over time.
Government bond yields form part of the risk-free rate used in valuation models. When that rate rises, the discount rate applied to future corporate cash flows generally rises, reducing their present value.
Higher yields can improve India's relative appeal, but foreign investors also consider US yields, rupee depreciation, hedging costs and global risk conditions. The headline yield alone does not determine foreign flows.
Disclaimer: This article is for educational and informational purposes only. It should not be treated as investment advice or a recommendation to invest in bonds, debt mutual funds, equities or any other financial product. Bond prices, interest rates, inflation and market conditions can change rapidly. Investors should consider their financial goals, risk profile and investment horizon before making decisions.
No spam. Only new posts, simple explainers, and practical money checklists for busy professionals.
Finnovate is a SEBI-registered financial planning firm that helps professionals bring structure and purpose to their money. Over 3,500+ families have trusted our disciplined process to plan their goals - safely, surely, and swiftly.
Our team constantly tracks market trends, policy changes, and investment opportunities like the ones featured in this Weekly Capsule - to help you make informed, confident financial decisions.
Learn more about our approach and how we work with you:
No comments yet. Start the conversation. What would you add?
No spam. Only new posts, simple explainers, and practical money checklists.
You may also like
India’s BRICS trade reached $417.5 billion in FY2026, but the deficit widened to $226.1 ...

India’s electric two-wheeler share stayed above 10% in August 2026. See what is driving ...
India is the world’s largest sponge-iron producer, yet prices hit a 2-year high in Augus...
India cleared ₹1.10 lakh crore of defence acquisition proposals in September 2026. Learn...
Popular now
Learn how to easily download your NSDL CAS Statement in PDF format with our step-by-step g...
Looking for the best financial freedom books? Here’s a handpicked 2026 reading list with...
Learn what SIF investment means in India, SEBI rules, Rs 10 lakh minimum investment, avail...
Clear guide to mutual fund taxation in India for FY 2025–26 after July 2024 changes: equ...