
NRI Capital Gains Tax in India: Shares, Property & MF
Understand NRI capital gains tax in India for 2026–27, including LTCG, STCG, shares, mut...
11 September 2026
Finnovate’s editorial team researches and creates financial content using trusted sources, regulatory references and inputs from subject experts.
Updated for Tax Year 2026-27
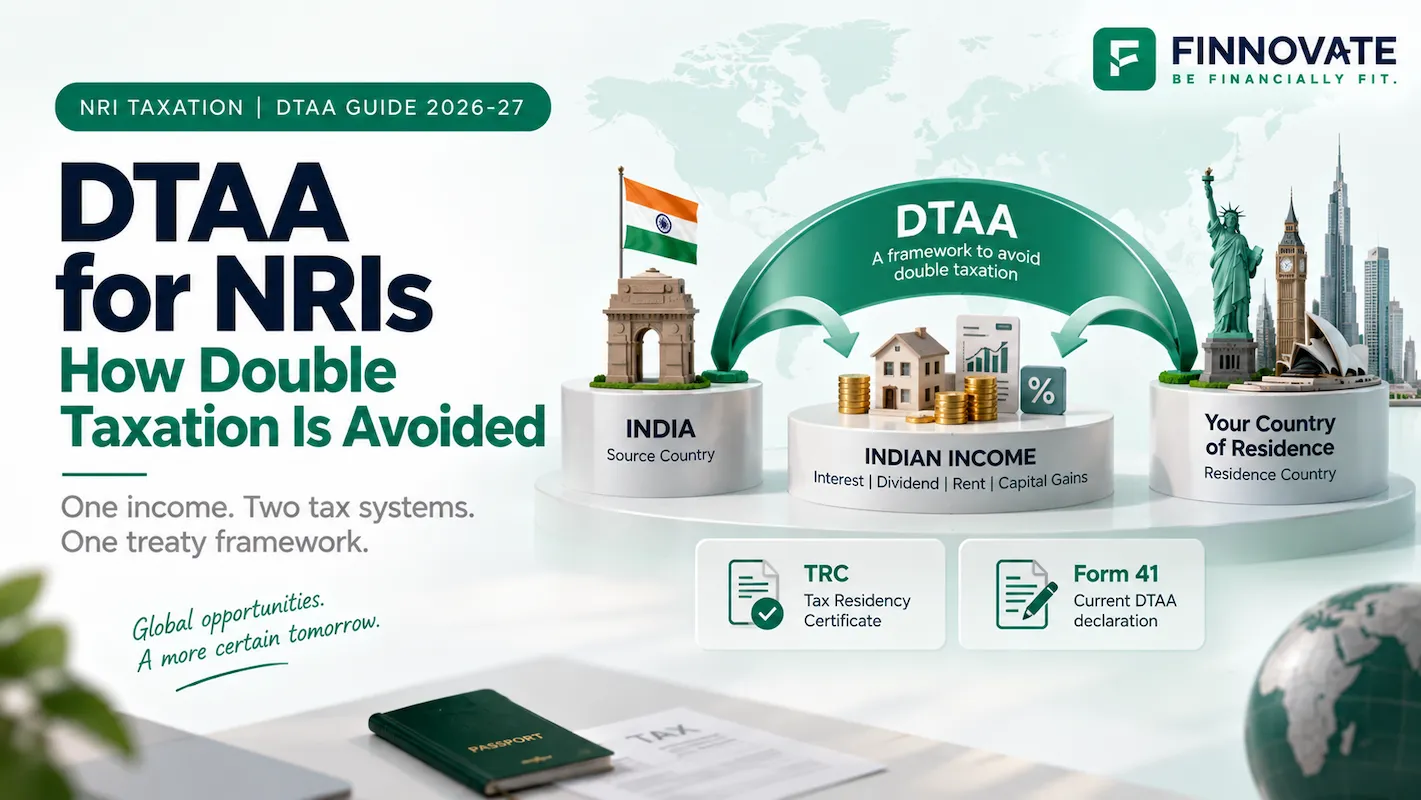
You may be taxed in India because your income arises here, while the country where you live may also consider the same income because you are tax resident there.
That is the basic problem a Double Taxation Avoidance Agreement, or DTAA, is designed to address.
For NRIs, this commonly comes up with:
But having a DTAA between India and your country of residence does not automatically make your Indian income tax-free.
Depending on the treaty and income involved, a DTAA may limit the tax India can charge, provide relief for tax already paid, allocate taxing rights between countries or change the treatment of a particular type of income.
Quick Answer: How DTAA Works for an NRI
| Question | Quick answer |
|---|---|
| What is DTAA? | A tax treaty between India and another country that allocates taxing rights and provides relief from double taxation |
| Does DTAA mean no tax in India? | No |
| What if Indian law and DTAA differ? | The more beneficial applicable provision can generally be used |
| What proves foreign tax residence? | A Tax Residency Certificate, or TRC |
| What happened to Form 10F? | It has been replaced by Form 41 under the Income Tax Rules, 2026 |
| Can DTAA reduce TDS? | Yes, where the treaty provides more favourable treatment and the applicable conditions are met |
| Does every income have the same DTAA rate? | No |
| Can excess Indian TDS be refunded? | Potentially, where it exceeds the final Indian tax liability |
DTAA stands for Double Taxation Avoidance Agreement.
India has tax treaties with many countries to deal with situations where the same income has a connection with both India and another country.
The source country is where the income arises.
For example, India may be the source country for:
The residence country is where you qualify as a tax resident under its domestic law and the applicable treaty.
The conflict arises because the source country may tax the income because it arises there, while the residence country may also tax it because you are tax resident there.
The treaty determines how those two taxing rights interact and how double taxation is relieved.
Under the Income Tax Act, 2025, India's DTAA framework is contained in Section 159.
Where an applicable treaty and Indian domestic law differ, the domestic law generally applies only to the extent it is more beneficial to the taxpayer.
That does not mean the lower percentage always wins. For interest, a treaty may provide a maximum Indian tax rate. For capital gains or business income, the treaty may instead determine which country has taxing rights.
DTAA does not always mean that income is taxed in only one country.
Relief can work in different ways.
Both countries may include the income in their tax systems.
The country of residence can then give credit, subject to its own law and the treaty, for eligible tax already paid in India.
Indian tax on the income: ₹15
Residence-country tax on the same income: ₹22
If the residence country allows full credit for the eligible ₹15 paid in India, the remaining tax there could be ₹7 rather than another ₹22.
In some treaty situations, income taxable in one country may be exempt from tax in the other country.
The exact result depends on the treaty and the domestic law of the residence country.
For certain income, especially interest and dividends, both countries may retain taxing rights while the treaty limits the maximum tax the source country can charge.
A practical DTAA review can be broken into seven steps.
Start with Indian domestic tax law.
Is the income taxable in India? What tax or withholding treatment would normally apply?
Simply living overseas is not enough.
You need to establish tax residence in the country whose treaty with India you want to use.
Interest, dividends, property income, capital gains, business profits and employment income do not necessarily follow the same treaty rule.
Check whether the treaty provides a more beneficial applicable outcome.
Depending on the income, treaty benefits may depend on factors such as:
Some Indian treaties contain anti-abuse rules such as the Principal Purpose Test, or PPT. Where it applies, treaty benefits can be denied if obtaining the benefit was one of the principal purposes of an arrangement or transaction, unless granting the benefit is consistent with the object and purpose of the treaty provision.
For current DTAA claims, this generally starts with:
Where the required documentation is in place before payment, the payer may be able to consider the treaty while deducting tax.
This can reduce the need to recover excess TDS later.
| Income | India's general position | What DTAA can change |
|---|---|---|
| NRO / Indian interest | India can tax | Treaty may cap India's rate |
| Indian dividends | India can tax | Treaty may cap India's rate |
| Rent from Indian property | India generally taxes | Residence country may provide double-tax relief |
| Gain from Indian property | India generally retains taxing rights | Residence-country relief may still matter |
| Shares and securities | Treaty-specific | Capital-gains provisions can change the result |
| Mutual fund gains | Treaty-specific | Asset classification and residual clauses can matter |
| Business profits | PE and treaty-specific | Treaty may limit India's taxing rights |
| Salary | Depends on facts and treaty | Employment provisions determine treatment |
Interest is one of the clearest examples of how a treaty can reduce Indian tax.
NRO account interest is generally taxable in India.
If the NRI is tax resident in a treaty country, the applicable interest provision may restrict how much India can tax, provided the treaty conditions are satisfied.
Under the India-Germany DTAA, interest arising in India may still be taxed in India.
However, where the recipient is the beneficial owner and the treaty conditions are satisfied, India's tax cannot exceed 10% of the gross interest.
Assume Rahul is tax resident in Germany and receives ₹2 lakh of eligible Indian interest.
Treaty maximum Indian tax at 10% = ₹20,000
Germany may separately consider the income under German tax law, with relief for eligible Indian tax according to the treaty and German rules.
The 10% is a treaty maximum, not an automatic rate merely because Rahul lives in Germany.
The India-UAE treaty shows why simple country-wise DTAA tables can be misleading.
For eligible interest where the recipient is the beneficial owner:
The 5% rate is therefore not the normal rate for every UAE-based NRI receiving interest from India.
NRE interest adds another useful distinction.
Eligible interest on an NRE account can already be exempt from Indian income tax where the relevant FEMA and RBI conditions are satisfied.
An NRI should not automatically look for a DTAA rate on income that is already exempt in India.
But the country where the NRI is tax resident may still tax the same NRE interest under its domestic law.
The overseas treatment therefore depends on:
Dividend income from an Indian company can be taxable in India even when the shareholder lives abroad.
An applicable DTAA may limit India's tax.
For example, under the India-UAE treaty, Indian tax on an eligible dividend is generally capped at 10%, subject to the applicable treaty conditions.
Other treaties can use different rates and may distinguish between shareholder types or shareholding levels. The actual treaty should therefore be checked.
Owning property in India while living abroad does not generally move the income outside India's taxing rights.
Income from immovable property situated in India can generally be taxed in India.
If the country where the NRI is tax resident also considers that rental income, double-tax relief may be available there under the treaty and local law.
Treaties generally preserve India's right to tax gains from immovable property located in India.
DTAA should therefore not be treated as a way to automatically remove Indian capital-gains tax from the sale of Indian property.
The treaty can still matter where the residence country also taxes the same gain and needs to recognise eligible Indian tax.
Capital gains need more treaty-specific analysis than interest.
The outcome can depend on:
The India-Singapore treaty is a useful example.
For shares in an Indian company acquired before 1 April 2017, grandfathering provisions can preserve residence-country taxation, subject to the treaty conditions.
For shares acquired on or after 1 April 2017, India may tax gains from shares of an Indian-resident company.
There was also a separate transitional regime for qualifying gains arising between 1 April 2017 and 31 March 2019.
Two investors selling shares in the same Indian company can have different treaty treatment depending on when those shares were acquired and which treaty provisions apply.
Mutual fund units require separate analysis.
They should not automatically be treated as identical to shares of an Indian company for treaty purposes.
Depending on the treaty:
The result depends on the wording of the particular treaty and the legal character of the asset. It should not be generalised across countries.
Tax residence, treaty wording, asset classification and individual facts all matter.
DTAA also covers income outside investments.
Business profits are generally considered together with the concept of a Permanent Establishment, or PE.
Broadly, whether a foreign resident has a PE in India can affect India's right to tax business profits attributable to Indian operations.
Treatment depends on the relevant treaty.
Different treaties can deal with professional and service income differently, so one common rule should not be applied across countries.
Employment income has separate treaty rules.
Factors such as:
can affect the outcome.
For most NRI investors, however, interest, dividends, property and capital gains are the more common DTAA issues.
Treaty benefits are not available merely because India has a DTAA with the country where you live.
You need to establish eligibility.
A Tax Residency Certificate, or TRC, is issued by the tax authority of the country where you are tax resident.
It establishes treaty residence for the relevant period.
A visa, residence permit, foreign address or overseas bank account does not by itself establish treaty tax residence.
The TRC should cover the relevant period for which treaty benefits are being claimed.
This is an important change from the earlier tax framework.
Under the previous Income Tax Rules, NRIs commonly used Form 10F when claiming treaty benefits.
Form 41 is the current self-declaration under Section 159(8) of the Income Tax Act, 2025.
The current filing framework requires prescribed information including:
The TRC is uploaded as part of the filing process.
Form 41 is filed for the relevant tax year when DTAA benefits are claimed.
There is no single universal calendar deadline for every treaty claim.
Practically, where treaty treatment is expected to affect TDS, completing the documentation before the relevant payment is processed can help avoid unnecessary higher withholding.
The current framework provides a registration route for eligible non-residents who do not have PAN but need to furnish Form 41.
Additional documents or declarations may still be required depending on the treaty, income and payer.
The process can be reduced to seven steps.
A bank, company, AMC or other payer may require treaty documentation before applying the treaty treatment.
Where an Indian return is required, the final liability, TDS credits and treaty position can then be reconciled through the applicable return.
Suppose Indian tax was deducted without applying an available treaty benefit.
That does not necessarily mean the higher amount becomes your final tax cost.
If the tax deducted exceeds the final Indian tax liability after applying an eligible treaty position, the eligible excess can generally be claimed through the applicable Indian return and refund process.
You still need to establish treaty eligibility, the applicable treaty treatment, required documentation and the final Indian tax liability.
For a significant payment where normal withholding may materially exceed the expected final Indian tax liability, the recipient can also explore a lower or nil deduction certificate under Section 395(1) of the Income Tax Act, 2025.
Under the Income Tax Rules, 2026, the current application for this certificate is Form 128.
If the certificate is issued, the payer deducts tax at the rate specified in the certificate, or does not deduct tax where the certificate permits it.
This is why tax and DTAA planning is usually easier before the payment or transaction, rather than after excess TDS has already been deducted.
Assume:
Indian tax on an income: ₹15
Residence-country tax calculated on the same income: ₹22
If the residence country's law and the DTAA allow full credit for the eligible ₹15 paid in India, the remaining residence-country tax could be ₹7.
This is only an illustration.
The actual foreign tax credit:
Form 67 belongs to India's mechanism for relevant taxpayers claiming credit in India for foreign taxes paid outside India.
It is different from Form 41.
The process is determined by the residence country's rules.
| Country | Income / situation | Illustrative treaty position |
|---|---|---|
| Germany | Eligible Indian interest | Indian tax capped at 10% where Article 11 conditions are met |
| UAE | Eligible interest | 12.5% generally; 5% for specified qualifying bank or financial-institution loans |
| UAE | Eligible Indian dividend | Indian tax generally capped at 10%, subject to treaty conditions |
| Singapore | Shares in Indian company | Capital-gains treatment can depend on acquisition date and treaty provisions |
These examples are not a universal treaty-rate table.
The applicable treaty provision and conditions should be checked for the actual income before using any rate.
If India does not have an applicable tax treaty with your country of residence, Indian-source income is generally taxed under Indian domestic law.
Whether the country where you live gives credit or another form of relief for Indian tax then depends on that country's domestic tax rules.
India has a unilateral-relief provision under Section 160 of the Income Tax Act, 2025 for situations involving countries with which no applicable agreement exists.
However, its general relief mechanism is primarily relevant to a person resident in India earning foreign income that is also taxed outside India.
It should therefore not be treated as a general Indian relief mechanism for an NRI living in a non-treaty country.
For a non-resident earning Indian-source income, the more relevant question is usually whether the country of residence provides foreign tax credit or another form of unilateral relief for Indian tax.
It does not. India may retain full or partial taxing rights.
Immigration residence and treaty tax residence are not the same thing.
The residency certificate should support the period for which treaty benefits are being claimed.
Form 10F belongs to the earlier framework.
For the current 2026-27 framework, the relevant form is Form 41.
Interest, dividends, property, capital gains and business income can all be treated differently.
Where treaty relief or lower withholding can be addressed before payment, having the tax position and documentation ready can reduce unnecessary higher withholding.
Before receiving significant Indian income, check:
Cross-border financial planning often involves more than tax.
Your investments, bank accounts, asset allocation, repatriation, retirement planning and estate planning need to work together across countries.
Explore NRI Financial AdvisoryFor tax filing, treaty interpretation, foreign tax credit claims and country-specific tax opinions, consult a qualified tax professional.
DTAA planning is not about finding the lowest percentage in a treaty-rate table.
The correct outcome depends on:
For interest and dividends, a treaty may cap India's tax.
For Indian property, India generally retains taxing rights.
For shares and mutual funds, capital-gains treatment can be much more country- and asset-specific.
And if both India and the country where you live tax the same income, relief may need to be claimed through the residence country's tax system.
A DTAA is a tax treaty between India and another country that determines how income connected with both countries is taxed and how double taxation is relieved.
Depending on the treaty, DTAA can limit India's tax, allocate taxing rights between the two countries, exempt qualifying income in one country or allow credit for eligible tax already paid.
No. India may still tax the income. The treaty determines whether India's taxing rights are retained, limited or altered for that particular income.
The NRI needs to establish treaty residence, obtain a valid TRC, file Form 41 under the current framework and satisfy the conditions of the applicable treaty. Additional payer-specific documentation may also be required.
A Tax Residency Certificate, or TRC, is issued by the tax authority of the country where the taxpayer is resident and is used to establish residence for treaty purposes.
Under the Income Tax Rules, 2026, the earlier Form 10F has been replaced by Form 41.
Current Income Tax Department guidance requires Form 41 for a non-resident seeking applicable DTAA benefits under the current framework.
Potentially. If the relevant treaty provides more beneficial interest treatment and the NRI satisfies the treaty and documentation requirements, Indian withholding can reflect that treaty treatment.
Yes, but capital-gains treatment differs substantially between treaties and assets. There is no universal DTAA capital-gains rate.
It can. The result depends on treaty wording and how the mutual fund units are treated under the applicable capital-gains provisions.
If the tax deducted exceeds the final Indian tax liability after an eligible treaty position is applied, the eligible excess may generally be claimed through the applicable Indian return and refund process.
Where the estimated final Indian tax liability justifies it, the payee can apply for a lower or nil deduction certificate under Section 395(1) of the Income Tax Act, 2025. The current application is Form 128.
No. Form 41 relates to claiming DTAA benefits in India as a non-resident. Foreign tax credit in the country where the NRI lives is governed by that country's rules.
Indian-source income is generally taxed under Indian domestic law. Whether you receive relief for Indian tax in your country of residence depends on that country's foreign-tax-credit or unilateral-relief rules. India's general unilateral-relief mechanism is primarily relevant to Indian residents earning income in countries with which India has no applicable agreement.
Disclaimer: This article is for general information and educational purposes only. It does not constitute investment advice, tax advice, legal advice, a treaty opinion, a recommendation or an offer to buy or sell any security or financial product. DTAA treatment depends on tax residence, income type, treaty wording, beneficial ownership where relevant, Permanent Establishment considerations, anti-abuse provisions, acquisition dates, documentation and individual circumstances. The article reflects publicly available provisions of the Income Tax Act, 2025, Income Tax Rules, 2026 and official treaty documents applicable at the time of publication. Tax laws, treaties, protocols, notifications and judicial interpretations may change. Please consult a qualified tax professional for treaty interpretation, tax filing and foreign tax credit claims, and a SEBI-registered investment adviser for investment advice.
No spam. Only new posts, simple explainers, and practical money checklists for busy professionals.
Finnovate is a SEBI-registered financial planning firm that helps professionals bring structure and purpose to their money. Over 3,500+ families have trusted our disciplined process to plan their goals - safely, surely, and swiftly.
Our team constantly tracks market trends, policy changes, and investment opportunities like the ones featured in this Weekly Capsule - to help you make informed, confident financial decisions.
Learn more about our approach and how we work with you:
No comments yet. Start the conversation. What would you add?
No spam. Only new posts, simple explainers, and practical money checklists.
You may also like
Understand NRI capital gains tax in India for 2026–27, including LTCG, STCG, shares, mut...
Returning to India with a 401(k)? Learn whether to keep it, roll it into an IRA or withdra...
Planning to retire in India as an NRI? Learn how to plan your retirement corpus, overseas ...
RBI will close the special FCNR(B) swap window on August 31, 2026 after $52.3 billion in d...
Popular now
Learn how to easily download your NSDL CAS Statement in PDF format with our step-by-step g...
Looking for the best financial freedom books? Here’s a handpicked 2026 reading list with...
Learn what SIF investment means in India, SEBI rules, Rs 10 lakh minimum investment, avail...
Clear guide to mutual fund taxation in India for FY 2025–26 after July 2024 changes: equ...