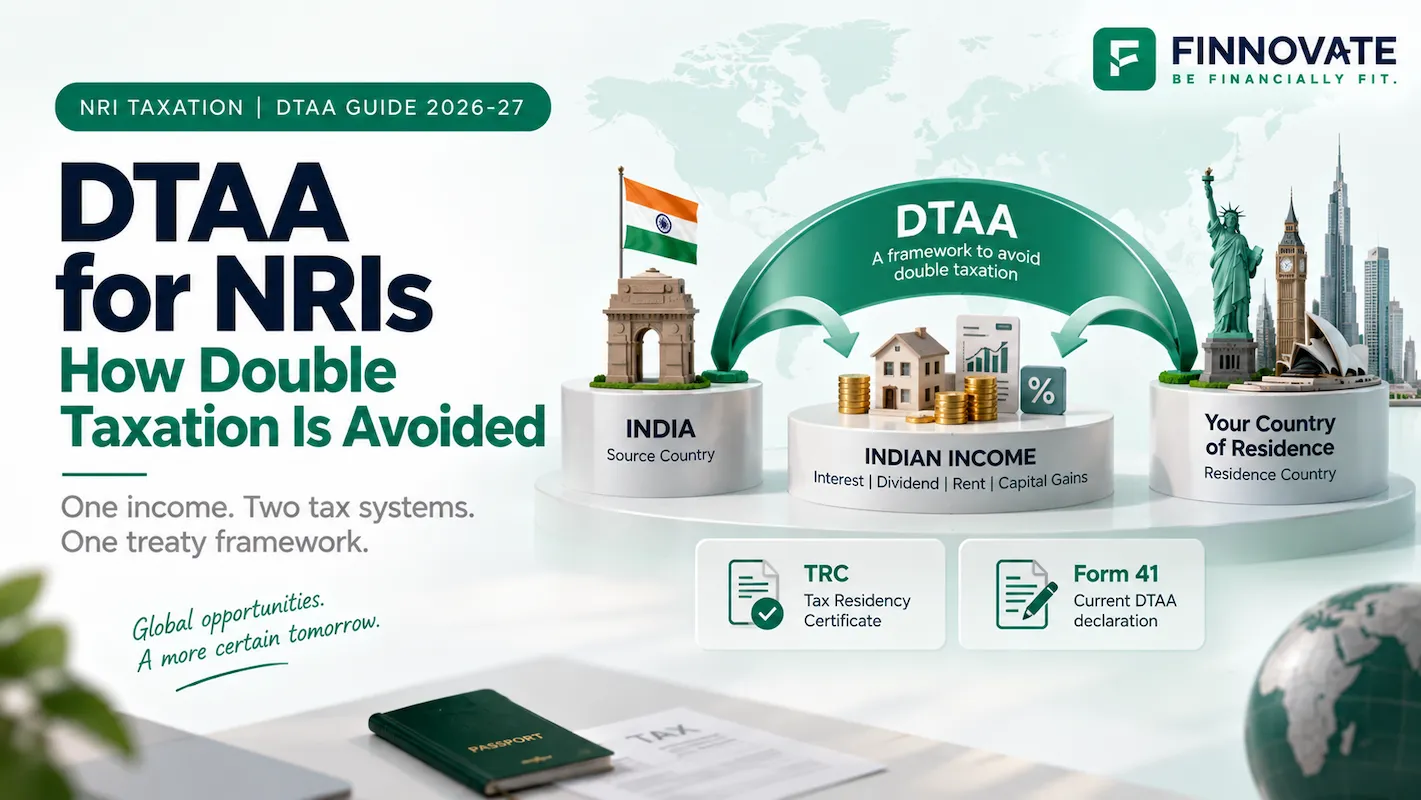
DTAA for NRIs in India: TRC, Form 41, TDS & Tax Relief
Understand DTAA for NRIs in India for 2026–27, including TRC, Form 41, TDS, NRO interest...
23 September 2026
Finnovate’s editorial team researches and creates financial content using trusted sources, regulatory references and inputs from subject experts.
Updated for Tax Year 2026–27
Living outside India does not automatically take you outside the Indian tax system.
If you still have bank deposits, mutual funds, shares, property, rental income or other financial interests in India, some of that income may continue to be taxable here.
The part that causes confusion is that there is no single “NRI tax rate”. Your tax position depends on four things:
TDS adds another layer. Tax may be deducted before money reaches you, but that deduction is not always your final tax liability. You may be entitled to a lower treaty rate or a refund when you file your return.
This guide brings the complete framework together. It explains how India taxes NRIs, how NRE, NRO and FCNR accounts are treated, where TDS applies, how capital gains and mutual funds are taxed, how DTAA works, when ITR filing may be required, and what changes when you return to India.
In this article, “NRI” is used broadly for an individual who is non-resident for Indian income-tax purposes. Some special provisions specifically use the term Non-Resident Indian for an Indian citizen or person of Indian origin, so the exact provision applicable to you may differ.
India's tax framework changed from 1 April 2026.
Income earned up to 31 March 2026 continues to be governed by the Income Tax Act, 1961. Income earned from 1 April 2026 falls under the Income Tax Act, 2025.
The new Act also replaces the old “Previous Year” and “Assessment Year” terminology with a single Tax Year concept.
| Period of income | Law applicable |
|---|---|
| Up to 31 March 2026 | Income Tax Act, 1961 |
| 1 April 2026 to 31 March 2027 | Income Tax Act, 2025 |
| Current reference | Tax Year 2026–27 |
Most underlying NRI taxation principles continue, but section numbers and some compliance terminology have changed.
You may therefore continue to see older section references in tax documents, court rulings and online articles. This guide focuses on the rules applicable now while mentioning older references where they remain useful.
The Union Budget 2026–27, presented on 1 February 2026, made no change to slab rates, capital-gains rates or the basic exemption limit. The changes that matter for NRIs are around compliance:
Quick Verdict: How Does NRI Taxation in India Work?
An NRI pays Indian tax only on income that is received in India or arises in India, such as NRO interest, Indian rent, dividends and capital gains on Indian assets. Salary earned and received abroad generally stays outside Indian tax. Tax is usually deducted at source at high rates, but TDS is not the final tax. A DTAA, a lower-deduction certificate or a tax return can reduce the final liability and unlock a refund.
| Question | Quick answer |
|---|---|
| Does an NRI pay tax in India? | Yes, on income that falls within India's taxing scope. |
| Is salary earned abroad taxable in India? | Generally not for a non-resident when services are performed abroad and the income is received outside India, subject to the facts. |
| Is NRO interest taxable? | Yes. |
| Is NRE interest taxable? | It can be exempt when the applicable FEMA and RBI conditions are met. |
| Is FCNR interest taxable? | It is generally exempt for eligible non-residents and can also qualify for exemption in certain RNOR cases. |
| Are Indian shares and mutual funds taxable? | Capital gains can be taxable depending on asset type, holding period and treaty position. |
| Is Indian rental income taxable? | Yes. |
| Does DTAA mean India cannot tax the income? | Not necessarily. The answer depends on the income type and the treaty with your country of residence. |
| Is TDS the final tax? | No. TDS is a withholding mechanism. Actual tax liability may be higher or lower. |
| Can excess TDS be refunded? | Yes, where tax deducted exceeds the final liability and the required return is filed. |
| Does every NRI need to file ITR? | No. Filing depends on income, transactions and statutory filing conditions. It may also be required to claim a refund. |
Your passport, visa or NRI bank account does not decide your residential status for income-tax purposes.
Residential status is calculated separately for every tax year, mainly using the number of days you spend in India.
As a general rule, an individual becomes resident in India if either of these conditions is met:
If neither condition is met, the individual is generally treated as non-resident.
But there are important exceptions.
For an Indian citizen leaving India for employment outside India, or leaving as a crew member of an Indian ship, the 60-day condition is generally replaced with 182 days.
A separate rule applies when an Indian citizen or Person of Indian Origin living abroad visits India.
If Indian income, excluding income from foreign sources for this purpose, does not exceed ₹15 lakh, the 60-day condition is generally replaced with 182 days.
If such income exceeds ₹15 lakh, the individual can become resident where the stay in India is:
A person falling within the 120-day to 181-day rule is generally treated as Resident but Not Ordinarily Resident rather than a full ordinary resident.
There is another special rule for Indian citizens.
An Indian citizen with income above ₹15 lakh, excluding income from foreign sources for this test, who is not liable to tax in any other country or territory because of residence, domicile or a similar criterion can be treated as a deemed resident of India.
This rule needs careful review because “not liable to tax” is different from simply living in a country with a low or zero personal income-tax rate.
Becoming resident does not automatically mean your worldwide income becomes fully taxable in India.
A resident individual may be:
RNOR status can apply, among other cases, when the individual:
Special RNOR rules also apply to certain visiting Indian citizens/PIOs and deemed residents.
Why does this matter?
| Residential status | Broad Indian tax scope |
|---|---|
| Non-Resident | Income received or deemed received in India and income accruing or deemed to accrue in India |
| RNOR | Wider than NRI taxation, but certain foreign income can still remain outside Indian tax |
| ROR | Worldwide income can generally enter the Indian tax scope |
Residential status should therefore be the first calculation an NRI makes every tax year.
For a non-resident, India generally taxes income that is:
This means an NRI can live entirely outside India and still have Indian taxable income.
At the same time, salary for services performed abroad and received abroad, foreign bank interest, overseas investment income and other genuinely foreign-source income will generally remain outside India's tax scope for a non-resident, subject to the facts and specific deeming provisions.
| Income | Usually taxable in India for an NRI? | Key point |
|---|---|---|
| Salary for services performed abroad and received abroad | Generally no | Facts around place of service and receipt matter |
| Salary for services performed in India | Yes | Indian-source salary can be taxable |
| NRO account interest | Yes | TDS usually applies |
| NRE account interest | Can be exempt | FEMA/RBI eligibility is important |
| Eligible FCNR deposit interest | Can be exempt | Special exemption conditions apply |
| Rent from Indian property | Yes | House property rules apply |
| Dividend from Indian companies | Yes | TDS may apply; DTAA can matter |
| Sale of Indian shares | Capital gains may be taxable | Holding period and security type matter |
| Indian mutual fund redemption | Capital gains may be taxable | Fund category matters |
| Sale of Indian property | Capital gains may be taxable | TDS and reinvestment rules can matter |
| AIF income | Depends on category and income character | Category I/II and III work differently |
| Foreign bank interest | Generally outside Indian scope for a non-resident | Subject to source and receipt rules |
A common mistake is to look only at where the money sits.
The better question is:
Where did the income arise, where was it received, what type of income is it, and what does the applicable tax law or treaty say?
NRE, NRO and FCNR accounts serve different purposes. Their tax treatment is also different.
Interest on an NRO savings account or fixed deposit is generally taxable in India.
Banks normally deduct tax at source on taxable NRO interest. For an NRI individual, domestic withholding on income that does not fall under another special category can be substantial, and applicable surcharge and cess may also affect the deduction.
A DTAA may provide a lower rate on interest for an eligible treaty resident, subject to treaty conditions and documentation.
Interest on an eligible NRE account can be exempt from Indian income tax.
But there is an important distinction.
The exemption is linked to the person being resident outside India under FEMA, or otherwise being permitted by the RBI to maintain the account. It should not be assumed that income-tax residential status and FEMA residential status are always identical.
So the statement “NRE interest becomes taxable the moment you return to India” is too simplistic.
Your FEMA status, account redesignation requirements and tax status should all be reviewed when you move back.
Interest on eligible foreign-currency deposits with approved scheduled banks can be exempt for non-residents.
The exemption can also continue for an individual who becomes Resident but Not Ordinarily Resident, subject to the prescribed conditions.
This makes FCNR deposits particularly relevant to returning NRIs, but account status and tax treatment should be checked before assuming the exemption continues.
TDS stands for Tax Deducted at Source.
Instead of waiting for you to calculate your final tax at the end of the year, Indian tax law requires the payer to withhold tax from several types of payments made to a non-resident.
TDS can arise on:
The rates below are the domestic rates in force. Surcharge and 4% cess apply on top. A DTAA rate or a lower-deduction certificate can reduce them where you qualify.
| Payment to an NRI | Domestic TDS rate (before surcharge and cess) |
|---|---|
| NRO interest | 30% |
| Rent from Indian property | 30% |
| Dividend from Indian companies | 20% |
| Short-term capital gain on listed equity shares / equity MF | 20% |
| Long-term capital gain on listed equity shares / equity MF | 12.5% |
| Long-term capital gain on property and other assets | 12.5% |
| Short-term capital gain on property | 30% |
This is one of the most important things for an NRI to understand.
Suppose ₹60,000 is deducted as TDS during the year, but your final Indian tax liability after applying deductions, capital-gain rules or an eligible treaty position is ₹35,000.
The extra ₹25,000 is not an additional tax simply because it was deducted.
It can generally be claimed as a refund through the income-tax return, subject to applicable conditions.
The reverse is also possible. If the TDS deducted is lower than the final liability, additional tax may be payable.
In appropriate cases, yes.
Depending on the income and circumstances, an NRI may be able to use:
The important part is timing.
If supporting documentation is required, it should normally be arranged before the payment or transaction rather than after excess tax has already been withheld.
Priya lives outside India and receives:
Tax may be deducted separately by the bank and other payers during the year.
Her final tax return then brings all taxable Indian income together, applies the relevant tax rules and credits the tax already deducted.
If the total TDS exceeds the final liability, Priya can claim the difference as a refund.
Say Priya earns ₹3,00,000 of NRO fixed-deposit interest and ₹4,80,000 of gross rent in the year, and has no other Indian income.
TDS deducted: the bank deducts 30% on interest, which is ₹90,000. The tenant deducts 30% on rent, which is ₹1,44,000. Total TDS is ₹2,34,000.
Final liability: rent gets the 30% standard deduction under house-property rules, so taxable rent is ₹3,36,000. Total taxable income is ₹6,36,000. Under the new-regime slabs, the first ₹4 lakh is nil and the next ₹2,36,000 is taxed at 5%, which is ₹11,800. As an NRI, Priya cannot use the resident-only rebate, so ₹11,800 is her tax.
Refund: ₹2,34,000 deducted minus ₹11,800 payable is roughly ₹2,22,000 refundable, but only if she files her return.
Tax is only one part of NRI financial planning. Bank accounts, investments, asset allocation, insurance, repatriation, estate planning and tax coordination often need to work together.
Explore Finnovate's NRI financial advisory services to understand how your India portfolio fits into your wider financial plan.
Explore NRI Financial AdvisoryFor tax return filing, treaty interpretation and legal tax positions, consult a qualified tax professional.
Capital gains are one of the biggest areas of NRI tax confusion because the treatment changes by asset.
Shares, equity mutual funds, debt-oriented investments, property and gold do not necessarily follow the same rules.
For Tax Year 2026–27, the broad capital-gain framework continues to include special rates for eligible equity assets and a 12.5% long-term capital-gains rate for many other capital assets.
| Asset | Broad tax treatment |
|---|---|
| Listed equity shares / equity-oriented MF, short term | 20% where the special equity capital-gain provisions apply |
| Listed equity shares / equity-oriented MF, long term | 12.5% on eligible LTCG exceeding the applicable ₹1.25 lakh threshold |
| Property held long term | Broadly 12.5% without indexation, subject to applicable provisions |
| Property held short term | Generally taxed at applicable rates |
| Specified debt-oriented mutual funds | Special rules can treat gains as short term irrespective of holding period |
| Other long-term capital assets | Broadly 12.5%, subject to asset-specific provisions |
Surcharge and cess can apply in addition to the headline rate.
The change made in 2024 removed indexation for long-term capital assets transferred on or after 23 July 2024.
A later protection was provided for certain resident individuals and HUFs selling land or buildings acquired before 23 July 2024. It effectively prevents them from paying more tax merely because of the switch from the earlier indexed method to the 12.5% method.
That protection is specifically limited to resident individuals and HUFs.
An NRI does not receive the same resident-only protection.
This issue became widely discussed under the second proviso to Section 112(1)(a) of the Income Tax Act, 1961 and remains important for NRIs holding older Indian property.
NRIs can access several capital-gain reinvestment provisions when the prescribed conditions are satisfied.
These can include relief for eligible reinvestment in:
The eligibility, reinvestment amount, timelines and caps differ by provision, so the transaction should be planned before the sale proceeds are redeployed.
An NRI investing in Indian mutual funds is taxed based on the tax classification of the fund and the nature of the gain.
There is no single “NRI mutual fund tax rate”.
The answer can depend on:
Where the relevant equity capital-gain provisions apply:
This area needs more care.
Certain specified mutual funds can fall under rules that treat the gains as short-term regardless of the actual holding period.
This rule applies to units acquired on or after 1 April 2023 in funds that invest more than 65% in debt and money-market instruments. Units bought before that date follow the normal holding-period rules.
Other non-equity investments may follow different holding-period and capital-gain rules.
This is one reason an NRI should not assume that every mutual fund held for several years automatically receives long-term tax treatment.
For NRIs, tax may be withheld when units are redeemed.
That does not always mean the amount deducted equals the final tax.
The final position depends on the actual taxable gain, applicable exemption or threshold, treaty treatment where relevant, and the return filed.
Potentially, but not for every country.
Capital-gain articles differ across India's tax treaties, and the treatment of mutual fund units has also been examined in judicial rulings.
In 2025, the Mumbai bench of the Income Tax Appellate Tribunal (Anushka Sanjay Shah) held that Indian mutual fund units are not “shares” under the India–Singapore treaty, so the gains were taxable only in Singapore. Similar wording exists in the treaties with the UAE and some other countries. The ruling is fact-specific and can be appealed, so it should be applied with professional advice rather than assumed.
The correct answer therefore depends on the NRI's country of tax residence, treaty wording, asset type and facts.
India has tax treaties with many countries.
These Double Taxation Avoidance Agreements are designed to allocate taxing rights between India and the other country and provide relief where the same income could otherwise face tax in both places.
But DTAA does not mean that every Indian income becomes tax-free.
The result depends on the treaty article covering that particular income.
For example:
The income can be taxed in India and also considered in the country of residence.
The residence country then gives credit, subject to its own law and treaty rules, for tax already paid in India.
Example:
If India validly taxes an income at 15% and the country of residence taxes that same income at 22%, the taxpayer does not normally pay 22% again without recognising the Indian tax.
The residence-country computation may give credit for eligible Indian tax already paid.
For some treaty situations, one country may exempt income that is taxable in the other country.
The exact method depends on the treaty and the domestic law of the country where the NRI lives.
Depending on the income and payer, an NRI may need documents such as:
Treaty benefits should not be treated as automatic simply because the individual lives in a treaty country.
Eligibility and documentation matter.
A tax treaty is generally intended to provide relief where its provisions are more beneficial to the eligible non-resident.
If Indian domestic law gives a better result for a particular income, the taxpayer does not normally need to choose a worse treaty outcome.
Indian property can create tax at three different stages:
Rent from property situated in India is generally taxable in India even if the owner lives abroad.
The normal house-property computation rules, including eligible deductions, need to be applied before arriving at the final taxable amount.
TDS may also be relevant when rent is paid to an NRI.
Selling property can create capital gains.
Broadly:
The buyer can also have withholding obligations when the seller is a non-resident.
Until 30 September 2026, a resident buyer must obtain a TAN before deducting and depositing this TDS, which often delays deals. From 1 October 2026, a resident individual or HUF buyer can deduct and deposit the TDS using their own PAN through a challan-cum-statement, with no TAN needed. The TDS rate itself does not change.
This is one area where relying only on the amount deducted by the buyer can produce the wrong conclusion. The capital gain, TDS position and final tax computation should be reviewed together.
Depending on the asset sold and what the NRI does with the proceeds, capital-gain exemptions may be available for eligible reinvestment in a residential property or specified bonds.
The conditions and deadlines differ, so this is best planned before the transaction rather than after the return is due.
Having TDS deducted does not automatically settle your filing obligation.
An NRI may need to file an Indian income-tax return depending on:
A separate set of provisions (Sections 115C to 115I of the Income Tax Act, 1961, carried into the Income Tax Act, 2025) applies only to Non-Resident Indians who invest through foreign currency. Under it, investment income from specified foreign-exchange assets such as shares of Indian companies bought in foreign currency is taxed at a flat 20%, and long-term capital gains on those assets at 10%, with no deductions.
The part most NRIs miss is Section 115G. If your only Indian income is this kind of investment income or long-term capital gain, and the correct TDS has already been deducted, you are not required to file an Indian return at all. Whether this regime helps or hurts depends on your income mix, so it should be compared with the normal rules before opting in.
Under the default tax regime for Tax Year 2026–27, the normal individual slab rates are:
| Total income | Tax rate |
|---|---|
| Up to ₹4 lakh | Nil |
| ₹4 lakh to ₹8 lakh | 5% |
| ₹8 lakh to ₹12 lakh | 10% |
| ₹12 lakh to ₹16 lakh | 15% |
| ₹16 lakh to ₹20 lakh | 20% |
| ₹20 lakh to ₹24 lakh | 25% |
| Above ₹24 lakh | 30% |
Special-rate income such as certain capital gains is taxed separately and should not simply be run through these slab rates.
An NRI can also opt for the old tax regime. The basic exemption there is ₹2.5 lakh with no senior-citizen enhancement, but deductions such as Section 80C, 80D and home-loan interest under Section 24(b) become available. Where Indian income is mostly rent with a home loan, or where large 80C investments exist, the old regime can sometimes give a lower tax, so both should be compared before filing.
There is another important difference between residents and NRIs.
The tax rebate that can make tax payable nil for eligible resident individuals with income up to the prescribed ₹12 lakh level under the default regime is specifically a resident-only benefit.
An NRI cannot use that resident rebate merely because total income is below ₹12 lakh.
There is a transition point to understand here.
For income earned up to 31 March 2026, returns for AY 2026–27 are filed under the Income Tax Act, 1961. The original due date of 31 July 2026 has passed; a belated return can still be filed up to 31 December 2026 with a late fee, and a revised return can be filed up to 31 March 2027, or before completion of assessment, whichever is earlier.
For Tax Year 2026–27 under the Income Tax Act, 2025, the return is filed after the tax year ends. The applicable return forms and detailed instructions are to be notified for that filing cycle.
Budget 2026 introduced staggered due dates. For individuals filing the ITR-1 or ITR-2 type of return, which covers most NRIs, the return for Tax Year 2026–27 is due 31 July 2027. Non-audit cases with business or professional income get until 31 August 2027.
Depending on the income involved:
Do not wait until the return deadline to collect these documents if a major property sale, redemption or cross-border transaction is planned.
Alternative Investment Funds require a separate tax analysis because the treatment depends heavily on the AIF category and the nature of the income distributed.
These generally operate under a pass-through tax framework for specified income.
The income retains its character in the investor's hands, which means the tax result can depend on whether the underlying income is:
Tax can be withheld before distributions are made to an NRI investor.
Category III structures can have a different tax framework, and the outcome depends on the legal structure of the fund and the income involved.
This should be reviewed from the fund's tax documentation rather than assuming the tax treatment is the same as a Category I or II AIF.
Treaty benefits may be relevant for certain income distributed to an eligible NRI, but the result depends on:
Returning to India can change more than your income-tax status.
It can affect:
The change is not always immediate or identical across laws.
For example, income-tax residential status and FEMA residential status are determined under different frameworks.
A returning NRI may also qualify as Resident but Not Ordinarily Resident (RNOR) for a period depending on prior years spent outside India.
RNOR status can be useful because the scope of Indian taxation during this transition period can be narrower than for a Resident and Ordinarily Resident.
However, RNOR should not be assumed from the fact that someone has recently returned. It needs to be calculated using the statutory tests.
FCNR deposit interest can also remain exempt for eligible RNOR individuals, subject to the prescribed conditions.
If you are planning a permanent return, review your residential status, overseas assets, bank accounts and investments before the move rather than after the first Indian tax return becomes due.
Most NRI tax problems come from a handful of repeat errors. Check yourself against these:
NRI tax planning becomes easier when it is treated as an annual process rather than a return-filing exercise.
Before the end of each tax year, check:
NRI taxation is rarely about finding one tax rate.
A bank deposit, property sale, mutual fund redemption and dividend can all be treated differently even when they belong to the same person.
Residential status decides the starting point. The source and type of income determine how India taxes it. TDS determines how much is collected upfront. DTAA can change the outcome where treaty conditions are satisfied. Your final return then brings these pieces together.
The more countries, income sources and assets involved, the more important it becomes to look at the complete financial picture rather than treating every tax event separately.
For large property sales, investment redemptions, returning-to-India decisions or cross-border portfolios, review the tax and investment impact before taking action.
Finnovate provides fee-based financial advisory for NRIs covering investment planning, portfolio structuring, retirement, insurance, estate planning and India-linked financial decisions.
Explore NRI Financial AdvisoryTax return filing, legal interpretation of a DTAA and individual tax opinions should be taken from a qualified tax professional.
Yes, where income falls within India's tax scope. A non-resident is generally taxed on income received or deemed received in India and income that accrues, arises or is deemed to accrue or arise in India. Genuine foreign income earned and received outside India is generally outside Indian taxation for a non-resident, subject to specific provisions.
Common taxable income includes NRO interest, rent from Indian property, dividends from Indian companies, capital gains from Indian assets and income from business or professional activities linked to India. NRE and eligible FCNR interest can qualify for exemption when the prescribed conditions are met.
Salary for services performed outside India and received outside India is generally not taxable in India for a non-resident. The position can change where services are performed in India, income is received in India or another deeming provision applies.
Interest on an eligible NRE account can be exempt. The exemption depends on the individual being resident outside India under FEMA or otherwise being permitted by the RBI to maintain the account. Income-tax residency and FEMA residency should not be treated as the same test.
Yes. NRO interest is generally taxable in India and tax is normally deducted at source. If the final liability is lower than the tax deducted, the excess may be refundable after filing the applicable tax return.
Generally yes when taxable capital gains arise from Indian assets. The rate depends on the asset, holding period and applicable tax provision. Treaty provisions can also matter for some assets and countries.
An eligible NRI may claim treaty relief where the applicable DTAA provides it. Depending on the income type and treaty, this can involve a lower Indian tax rate, allocation of taxing rights or a foreign tax credit in the country of residence. A DTAA does not automatically make Indian income tax-free.
Yes. If tax deducted in India exceeds the final Indian tax liability, the excess can generally be claimed as a refund by filing the applicable income-tax return and satisfying the required conditions.
No. Filing depends on taxable income, type of income, transactions and other statutory conditions. An NRI may still choose or need to file where excess TDS must be refunded, losses need to be carried forward or other filing requirements apply.
No. The rebate under the current default tax regime is available to eligible resident individuals. A non-resident individual cannot claim the resident-only rebate merely because total income is ₹12 lakh or below.
It depends on the payment. NRO interest and rent are generally deducted at 30%, dividends at 20%, equity short-term gains at 20% and long-term gains at 12.5%, all plus surcharge and cess. A DTAA rate or a lower-deduction certificate from the tax department can bring these down if arranged before payment.
Slab rates and capital-gains rates did not change. The main changes are that buyback proceeds are now taxed as capital gains, resident individual and HUF buyers no longer need a TAN to deduct TDS on property bought from an NRI from 1 October 2026, ITR due dates are staggered between 31 July and 31 August, and Form 41 has replaced Form 10F for treaty claims.
Disclaimer: This article is for general information and educational purposes only. It does not constitute investment advice, tax advice, legal advice, a recommendation or an offer to buy or sell any security or financial product. Tax treatment depends on residential status, source and character of income, transaction dates, applicable treaty, documentation and individual circumstances. The article reflects publicly available provisions of the Income Tax Act, 2025, Finance Act, 2026, Income Tax Act, 1961 where relevant for earlier periods, and related official guidance available at the time of publication. Tax laws, rules, treaty interpretations and filing requirements may change. Judicial decisions can also be fact-specific and subject to appeal. Please consult a qualified tax professional for tax filing, treaty interpretation and individual tax positions, and a SEBI-registered investment adviser for investment advice. Mutual fund, AIF and securities investments are subject to market risks. Please read all related documents carefully before investing.
No spam. Only new posts, simple explainers, and practical money checklists for busy professionals.
Finnovate is a SEBI-registered financial planning firm that helps professionals bring structure and purpose to their money. Over 3,500+ families have trusted our disciplined process to plan their goals - safely, surely, and swiftly.
Our team constantly tracks market trends, policy changes, and investment opportunities like the ones featured in this Weekly Capsule - to help you make informed, confident financial decisions.
Learn more about our approach and how we work with you:
No comments yet. Start the conversation. What would you add?
No spam. Only new posts, simple explainers, and practical money checklists.
You may also like
Understand DTAA for NRIs in India for 2026–27, including TRC, Form 41, TDS, NRO interest...

Understand NRI capital gains tax in India for 2026–27, including LTCG, STCG, shares, mut...
Returning to India with a 401(k)? Learn whether to keep it, roll it into an IRA or withdra...
Planning to retire in India as an NRI? Learn how to plan your retirement corpus, overseas ...
Popular now
Learn how to easily download your NSDL CAS Statement in PDF format with our step-by-step g...
Looking for the best financial freedom books? Here’s a handpicked 2026 reading list with...
Learn what SIF investment means in India, SEBI rules, Rs 10 lakh minimum investment, avail...
Clear guide to mutual fund taxation in India for FY 2025–26 after July 2024 changes: equ...