India Has 40 GW of Clean-Power Projects Looking for Buyers
Finnovate’s editorial team researches and creates financial content using trusted sources, regulatory references and inputs from subject experts.
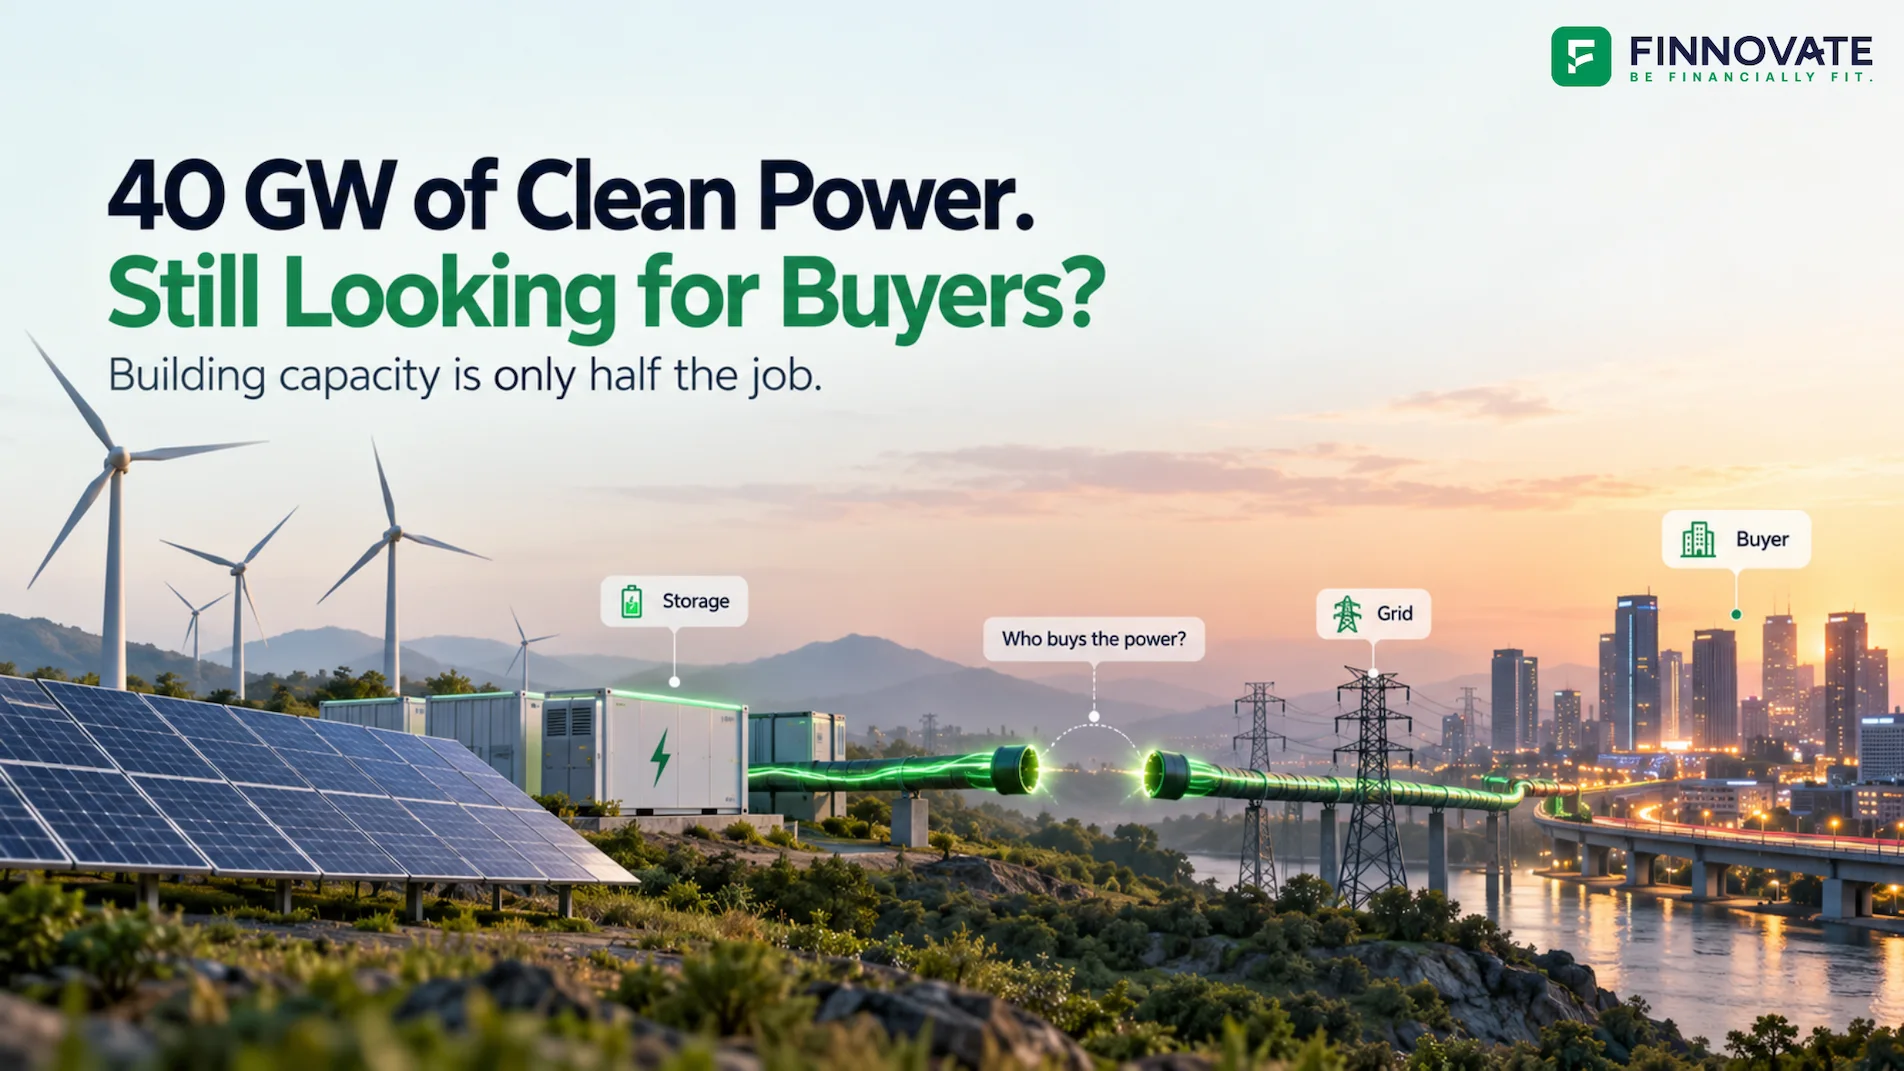
India wants more clean electricity. Developers want to build the projects. Investors are being asked to finance the expansion.
Yet, around 40 gigawatts of awarded clean-energy projects are still looking for customers, according to an estimate shared by the country’s renewable-energy secretary on October 28.
At the same time, India estimates that it needs US$220 billion of investment over the next three years across renewable power, batteries, green hydrogen and transmission.
Why raise money for more projects when so many are still waiting for buyers?
The answer starts with what an electricity buyer actually needs. A distribution company needs power at particular hours, delivered to particular locations, at a price it can afford. A developer’s offer has to fit those requirements.
Building generating capacity is one part of the business. Turning it into electricity that someone will pay for takes several more.
What is waiting for a buyer?
The 40 GW figure refers to a pipeline of awarded projects. These are not necessarily completed plants generating electricity with nowhere to send it.
An award gives a developer an opportunity to build and supply power under the tender’s terms. Further steps can include signing contracts, securing financing, obtaining approvals, arranging grid access and completing construction.
A project can therefore feature in a company’s announced pipeline well before it starts earning revenue.
Government disclosures show how large the contracting gap has been. As of December 31, 2025, four central renewable-energy implementing agencies had issued awards covering around 69 GW, with power purchase agreements signed for approximately 24.3 GW against those awards.
That was an earlier snapshot of a specific pool of projects. The latest 40 GW estimate describes the continuing difficulty of finding buyers, rather than a count of idle, completed power stations.
For a developer, the difference is substantial. Winning a bid creates an opportunity. A signed contract helps establish how that opportunity can become a business.
The customer is part of the financing
A solar project requires spending long before it produces its first unit of electricity. There is land to arrange, equipment to procure and construction to fund.
A lender assessing the project will want to understand how that money comes back.
Who will buy the electricity? At what price? For how long? What happens if either side fails to meet its obligations?
A power purchase agreement, or PPA, sets out the terms between the generator and its buyer. A credible long-term contract gives lenders a basis for assessing future cash flows, although construction, operating and payment risks remain.
In centrally organised procurement, there can also be an intermediary.
The Solar Energy Corporation of India, or SECI, signs PPAs with developers and corresponding power sale agreements with distribution companies or other final buyers.
The developer has an agreement to supply power to SECI. SECI has an agreement to sell that power onwards.
This is why finding the final buyer matters even after a developer wins an auction. The chain needs demand at the other end.
| Project milestone | What it establishes | What still needs checking |
|---|---|---|
| Tender awarded | A developer has won a project opportunity | Contracts, approvals and execution requirements |
| Purchase and sale contracts signed | Buyers and delivery terms are agreed | Financing, payment security and project readiness |
| Construction completed | The generating assets have been built | Grid availability and commissioning requirements |
| Commercial operation begins | The project can supply power commercially | Actual output, delivery obligations and costs |
| Payments collected | Electricity sales have produced cash receipts | Ongoing payment performance and debt servicing |
↔ Scroll horizontally to view the full table.
The sequence and requirements vary by project, but each milestone tells investors something different.
More electricity, but at which hour?
Imagine a distribution company that already receives considerable solar power during the afternoon.
Its next procurement decision may be driven by demand after sunset, when households switch on lights and appliances while solar generation fades.
Another plain solar project may offer an attractive price per unit. But it may deliver more electricity during hours when the buyer already has adequate supply.
The distribution company still needs to arrange the evening supply separately.
This helps explain why growing national electricity demand can coexist with weak demand for certain projects.
MNRE has acknowledged the shift. Its February 2026 disclosure said distribution companies and other buyers increasingly prefer solar or wind combined with storage, peak-hour supply and firm, dispatchable renewable power. Demand for plain solar and wind has weakened in comparison.
The commercial value lies in the delivery pattern as well as the volume.
Buyers also have existing contracts, demand forecasts and payment obligations to consider. Committing to another long-term agreement is a decision about the future mix of their supply.
For developers and lenders, the buyer’s ability to pay is another consideration. A contract provides a route to revenue; timely collections turn that revenue into money available for operating expenses and loan repayments.
Even a signed contract needs a route to the customer
Suppose a project has secured a buyer and completed construction.
Its electricity still needs to travel through substations and transmission lines before reaching the distribution network.
Generation projects and transmission infrastructure do not always become ready together. Building a new network can involve land access, rights of way, equipment procurement and coordination across several agencies.
If the available network cannot safely carry all the electricity being produced, generators may be instructed to reduce output. This is called curtailment.
An unsigned purchase contract and a transmission bottleneck are different problems. One concerns the commercial arrangement. The other concerns physical delivery. A project may face either, or both.
The financial impact of curtailment also depends on the reason and the applicable contract provisions. Reduced output does not translate into the same revenue loss for every project.
India’s power ministry has identified transmission expansion, stronger grid operations and storage deployment as essential parts of integrating more renewable capacity. More generation requires a network capable of handling it.
What batteries change
Batteries allow some electricity generated at one time to be supplied later.
A solar project paired with storage can reserve part of its daytime output for an evening delivery commitment. This can make its offer more useful to a buyer seeking power after sunset.
But storage adds another set of costs and operating decisions. Batteries require investment, lose some energy during charging and discharging, and have limits on how much power they can deliver and for how long.
Those last two measures are different:
- MW measures power: how quickly the battery can deliver electricity.
- MWh measures energy: how much electricity it can store and supply.
For example, a system rated at 100 MW and 400 MWh corresponds to four hours at full rated output before allowing for operating limits and losses.
That duration matters when comparing storage projects. A large power rating alone says little about how long the battery can support supply.
Storage can improve the timing of delivery. It still needs a viable commercial arrangement and suitable grid access.
What a project with a buyer looks like
ENGIE’s October 29 announcement offers a useful example.
The company confirmed that two Indian solar projects, 250 MW at Khaba in Rajasthan and 200 MW at Khavda in Gujarat, were fully operational.
The Khavda project has a 25-year PPA with Gujarat Urja Vikas Nigam Limited. It has both operating capacity and an identified long-term buyer.
ENGIE also disclosed battery and hybrid project awards, including a project combining solar generation with storage. Its stated ambition is to grow its Indian renewable and storage portfolio to 7 GW by 2030.
These projects illustrate how developers are combining generation, customer contracts and flexibility. They are separate from the 40 GW pipeline awaiting buyers.
For investors, a company’s capacity announcement becomes more useful when it explains which projects are awarded, contracted, under construction or operating.
Where the next investment needs to go
India had approximately 308 GW of non-fossil installed electricity capacity as of September 30, 2026, against a 500 GW target for 2030. Non-fossil capacity includes nuclear power alongside renewable sources.
These figures measure generating capacity, rather than the electricity actually produced over a year.
The estimated US$220 billion investment requirement covers several parts of the energy system. It is an estimate of capital needed, not an announced government spending package.
The contracting backlog shows why that capital has to be matched with procurement and infrastructure planning.
Buyers need supply offers that fit their demand. Developers need contracts that support financing. Transmission networks need to be ready for delivery. Storage needs to earn enough from its services to justify its cost.
For someone evaluating an energy company, the useful questions extend beyond its total project pipeline:
- How much capacity has signed purchase contracts?
- How much is operating and collecting payments?
- Are transmission arrangements aligned with commissioning dates?
- How much funding is still required?
- What delivery commitments and risks come with storage-backed projects?
A growing pipeline can signal opportunity. Its progress towards reliable cash flows determines how much that opportunity is worth.
India’s clean-power expansion will depend on more projects reaching that point: a working plant, a route to the customer and a buyer willing and able to pay.
Sources
- Reuters: India seeks US$220 billion clean-energy investment, October 28, 2026
- MNRE parliamentary reply, February 3, 2026
- SECI: What We Do
- Ministry of Power: Strengthening transmission infrastructure for renewable-energy integration
- ENGIE: Commissioning of 450 MW of solar capacity in India, October 29, 2026
- ENGIE: Activities in India
- Government of India: September 2026 installed-capacity figures
- MNRE: Non-fossil capacity milestone and the 2030 target
Disclaimer: This article is for general information and education and does not constitute investment advice or a recommendation to buy or sell any security. Company examples illustrate industry developments and are not investment recommendations.