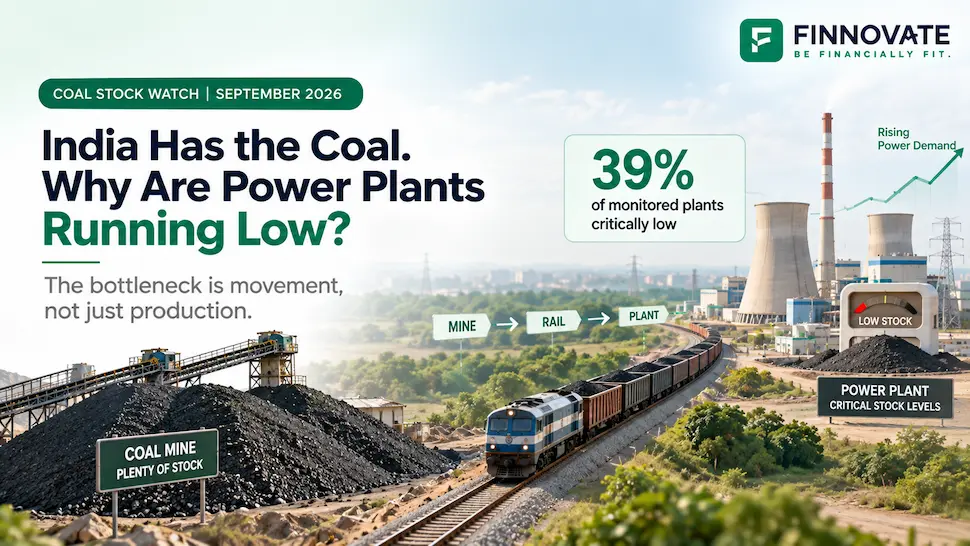
India Coal Stocks 2026: Why 39% of Power Plants Are Critically Low
Nearly 39% of India’s monitored coal power plants were critically low on fuel in Septemb...
22 September 2026
Finnovate’s editorial team researches and creates financial content using trusted sources, regulatory references and inputs from subject experts.
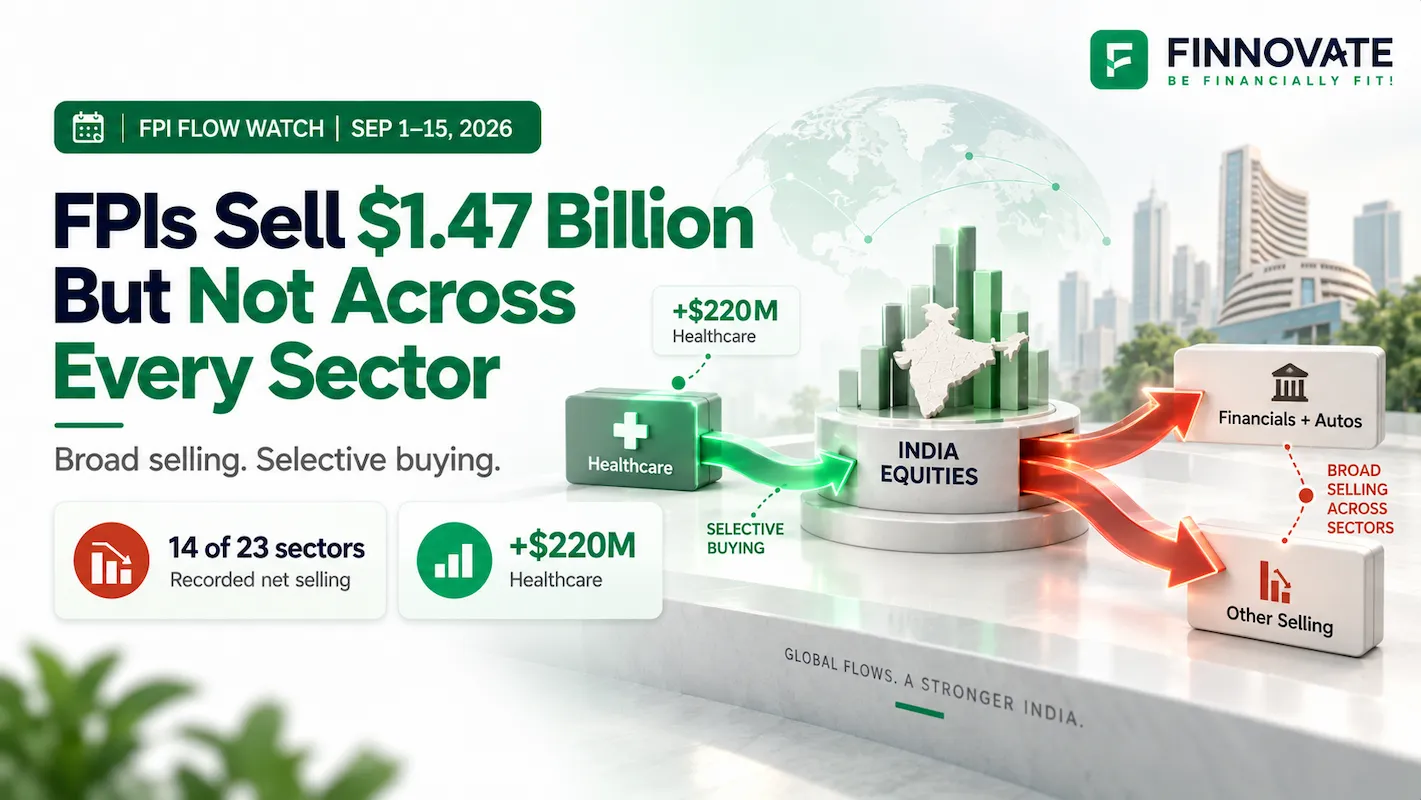
Foreign portfolio investors sold more Indian shares than they bought in the first fortnight of September 2026. Net equity selling reached approximately $1.47 billion during September 1–15, with outflows across 14 of the 23 reported sectors.
Financial services and automobiles recorded combined net selling of $925 million. Healthcare moved in the other direction, attracting $220 million in net buying. The sector split shows where foreign investors reduced exposure and where they continued to invest.
The shift came as oil prices rose and markets assessed inflation, currency risk and the outlook for interest rates. These pressures affect both company earnings and the returns foreign investors earn when they convert Indian investments back into dollars.
Foreign portfolio investors, or FPIs, invest in financial assets such as shares and bonds outside their home country. Net equity selling means the value of their share sales exceeded their purchases during the reporting period.
Net FPI equity selling during September 1–15, 2026.
Recorded net selling during the first fortnight.
The comparable first fortnights of July and August had together recorded approximately $3.36 billion in net buying. September’s opening fortnight marked a reversal against those periods.
Note: All flow figures in this article cover September 1–15, 2026. Dollar values are rounded. The full-month September total will include subsequent transactions.
Financial services and automobiles were prominent areas of selling. Oil and gas, FMCG, power and telecom also recorded withdrawals.
| Sector or sector group | Net selling, September 1–15 |
|---|---|
| Financial services and automobiles combined | $925 million |
| Power and telecom combined | $275 million |
| Oil and gas | $249 million |
| FMCG | $211 million |
Scroll horizontally to view the table on mobile.
Borrowing supports spending in both sectors, which makes the interest-rate outlook relevant. Higher loan costs can affect vehicle demand, while lenders must manage funding costs, lending rates and borrowers’ ability to repay.
The effect differs across companies. A bank’s exposure depends on its deposits and loan book; an automaker’s exposure depends partly on customer financing and its product mix. These are the business channels investors assess alongside valuations when deciding how much to invest.
Higher crude prices affect oil producers, refiners and fuel retailers differently. For an oil marketing company, a rise in crude costs can squeeze marketing margins if retail fuel prices do not rise enough to offset it. The sector’s earnings therefore depend on the type of business as well as the price of oil.
FMCG companies can face higher packaging, transport and raw-material costs. Their ability to protect profits depends on pricing, product mix and how readily customers accept price increases.
Power and telecom recorded combined net selling of $275 million. Both sectors include businesses with large investment needs, so financing costs and future cash generation matter to their valuations.
Company spending plans, project progress and operating results will help put these withdrawals in context. Sector flows record investment decisions, while those business indicators show how the underlying companies are performing.
Healthcare attracted $220 million in net buying. Consumer services and construction also recorded buying during the fortnight.
Healthcare includes hospitals, diagnostics and pharmaceutical businesses serving domestic and overseas markets. Essential medical demand can be less sensitive to the economic cycle, although earnings still depend on costs, competition, regulation and valuation.
These factors influence foreign investment through company profits, currency returns and the appeal of investments available in other countries.
Brent crude settled at $94.65 a barrel on September 1 and was trading above $107 by September 14. The rise increased concerns about energy costs and supply disruption as the fortnight progressed.
India’s dependence on imported crude makes this relevant to the wider economy. Higher oil prices can raise the import bill and dollar demand, while businesses face potential increases in transport and production costs. The effect on consumer prices depends on taxes, retail pricing and how much of the increase companies absorb.
The duration of the rise matters. Sustained high prices give businesses less room to absorb additional costs and can have a larger effect on profits and household spending.
Foreign investors often measure performance in dollars or another home currency. Their return depends on both the Indian investment and the exchange rate.
Consider an investor who brings in $1,000 at an assumed exchange rate of ₹95 per dollar and invests ₹95,000 in shares. If the shareholding stays at ₹95,000 but the exchange rate moves to ₹100 per dollar, its dollar value falls to $950.
The shareholding’s rupee value is unchanged.
The dollar value falls 5% because of the exchange-rate movement.
Illustration only. The exchange rates are assumptions, not a forecast. Dividends, taxes, transaction costs and currency hedging are excluded.
This is why currency expectations can influence investment decisions even when a company’s operating performance has not changed.
India’s provisional retail inflation reached 4.82% in August 2026, according to the government release published on September 14. That update arrived near the end of the fortnight and added to the information available ahead of the RBI’s next policy decision.
Higher expected interest rates can raise business borrowing costs and reduce the present value investors place on future profits. Overseas rates matter too, because global funds compare potential returns and risks across countries.
Markets were anticipating the Fed’s September decision during the fortnight. On September 16, after this article’s flow period ended, the Fed raised its target range by 25 basis points to 3.75%–4.00%.
The RBI’s response depends on India’s inflation and growth outlook, together with broader financial conditions. Finnovate’s review of the RBI’s August 2026 policy explains the backdrop to that decision.
FCNR(B) deposits bring foreign-currency funding into Indian banks. The RBI’s special swap facility encouraged such inflows, and its deposit mobilisation window closed on August 31 following strong participation.
These bank deposits and FPI share purchases serve different purposes. A foreign fund buying equities assesses earnings, valuations, currency risk and opportunities elsewhere. Strong foreign-currency deposit inflows can therefore coexist with selling in Indian shares.
Our guide to FCNR(B) deposits and the 2026 scheme explains the deposit and swap arrangement.
FPI equity assets under custody stood at approximately $703 billion at mid-September. This measures the dollar value of equity holdings at that point.
That value changes when investors buy or sell shares, when share prices move and when the rupee changes against the dollar. A fall in holdings value therefore needs to be assessed alongside market performance and exchange rates.
Purchases minus sales over a stated period.
The value of holdings at a particular date, affected by flows, prices and currency movements.
The next fortnight will show whether early-September selling persists or changes direction. Three developments will help explain the next set of numbers.
The first fortnight’s clearest finding is the combination of broad selling and selective buying. Financial services and automobiles saw sizeable withdrawals, while healthcare attracted investment. Following these patterns alongside business results will provide a more useful picture as September progresses.
FPIs recorded approximately $1.47 billion in net equity selling during September 1–15, 2026. This covers the first fortnight, rather than the full month.
Financial services and automobiles recorded combined net selling of $925 million. Oil and gas, FMCG, power and telecom also saw outflows. Healthcare recorded net buying of $220 million.
An unhedged foreign investor must account for exchange-rate movements when converting an Indian investment into their home currency. A weaker rupee reduces the dollar value of a holding, assuming its rupee value stays unchanged.
Flows measure purchases minus sales during a period. Assets under custody measure the value of holdings at a particular date and also reflect share-price and exchange-rate movements.
Disclaimer: This article is for educational and informational purposes only. FPI flows describe past transactions and are not investment recommendations or indicators of future performance. Investment decisions should reflect your goals, time horizon, risk capacity and overall asset allocation.
No spam. Only new posts, simple explainers, and practical money checklists for busy professionals.
Finnovate is a SEBI-registered financial planning firm that helps professionals bring structure and purpose to their money. Over 3,500+ families have trusted our disciplined process to plan their goals - safely, surely, and swiftly.
Our team constantly tracks market trends, policy changes, and investment opportunities like the ones featured in this Weekly Capsule - to help you make informed, confident financial decisions.
Learn more about our approach and how we work with you:
No comments yet. Start the conversation. What would you add?
No spam. Only new posts, simple explainers, and practical money checklists.
You may also like
Nearly 39% of India’s monitored coal power plants were critically low on fuel in Septemb...
Tata Sons faces a major governance dispute over N Chandrasekaran’s reappointment, RBI li...
India’s CPI inflation rose to 4.82% in August 2026 as food inflation neared 6% and rural...
India’s trade deficit narrowed to $26.86 billion in August 2026. See what drove the impr...
Popular now
Learn how to easily download your NSDL CAS Statement in PDF format with our step-by-step g...
Looking for the best financial freedom books? Here’s a handpicked 2026 reading list with...
Learn what SIF investment means in India, SEBI rules, Rs 10 lakh minimum investment, avail...
Clear guide to mutual fund taxation in India for FY 2025–26 after July 2024 changes: equ...