Volkswagen’s India Tax Dispute: When Do Car Parts Become a Car?
Finnovate’s editorial team researches and creates financial content using trusted sources, regulatory references and inputs from subject experts.
A car arrives at an Indian port. It has an engine, a gearbox, seats and everything else needed to get it on the road.
Except none of these things is connected yet.
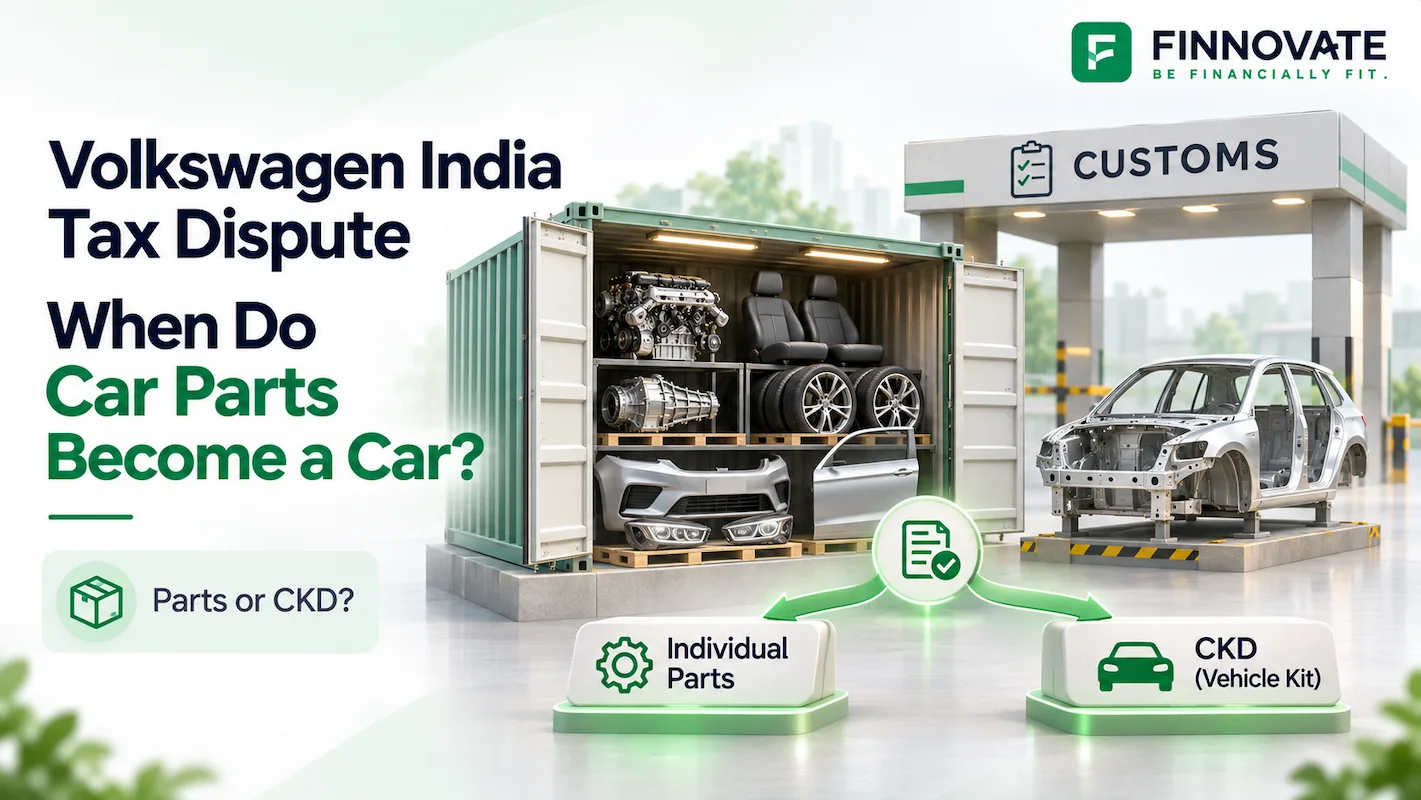
Should customs treat the shipment as a car waiting to be assembled, or as a collection of individual parts?
That distinction can change the import duty substantially. And for Volkswagen, it sits at the centre of a customs dispute involving approximately ₹11,526 crore.
Indian authorities argue that the company’s imports should have attracted higher duties. Volkswagen disputes the allegations.
The disagreement now reaches beyond what arrived in the containers. It also concerns how long authorities can take to question the duty paid, and who bears the cost when a dispute emerges after the cars have already been sold.
First, how do you import a car?
A manufacturer can ship a finished vehicle into a country. Or it can bring in components and assemble the vehicle locally.
Within the second route lies an important category: completely knocked-down, or CKD, kits. These contain a vehicle’s components for assembly.
Buying individual components for a factory and importing a vehicle in kit form can look similar from a distance. Both involve parts crossing a border. But customs classification determines which duty treatment applies.
In Volkswagen’s case, authorities allege that the company imported nearly complete vehicles in unassembled form while declaring them as individual components. The reported duty rates were 5%–15% on the component imports, against 30%–35% under the CKD treatment sought by authorities. These figures relate to the disputed imports, rather than a single tariff applicable to every vehicle or component today.
A simple illustration shows why the distinction matters.
Assume imported goods have an assessable value of ₹10 lakh. At a hypothetical basic customs duty rate of 10%, the duty is ₹1 lakh. At 30%, it becomes ₹3 lakh.
That is a ₹2 lakh difference on the same import value, before other applicable levies.
Repeat that difference across years of imports, and a classification disagreement can become a major financial liability.
The dispute follows the parts back to the factory
The disputed imports concern components brought into the group’s Aurangabad facility between March 2012 and July 2024, involving Audi, Škoda and Volkswagen vehicles.
Authorities reportedly allege that software helped divide vehicle-component orders among overseas suppliers, allowing imports to be presented separately rather than as kits.
Volkswagen has challenged that interpretation. Its position is that the software served production planning and demand tracking.
This is where the apparently simple question becomes harder.
A factory needs systems to coordinate purchases, production schedules and deliveries. The existence of such software alone cannot establish whether an import declaration was correct. What matters is how the arrangements worked and how the applicable customs rules treat them.
The dispute turns on what was imported and how it should have been classified.
Volkswagen’s official statement says its Indian subsidiary is pursuing legal remedies and maintains that it complies with applicable laws. Its 2025 annual report records the show-cause notice issued in 2024 and the company’s subsequent High Court challenge.
Then there is the question of timing
At the October 29, 2026 hearing, Volkswagen’s lawyer argued that authorities could not scrutinise imports stretching back 12 years when the applicable legal period was five years.
The government countered that Volkswagen had failed to supply requested information on time, prolonging the investigation.
Why does this matter so much?
Because a tax dispute involves both the amount allegedly owed and the legal process for recovering it.
Section 28(4) of the Customs Act provides a five-year notice period from the relevant date in specified cases involving collusion, wilful misstatement or suppression of facts. The law also sets out rules affecting how the period is calculated, including certain exclusions.
Applying those rules requires examining the facts, assessments and procedural history.
Volkswagen’s argument challenges whether the authorities acted within the permitted period. The government’s response seeks to explain the delay. Neither submission settles the issue by itself.
A company can dispute both the tax treatment and the timing of a demand. Raising the second argument is not an admission that the first was wrong.
Why the case returned to court
The dispute had already gone through arguments before a Bombay High Court bench.
In August 2026, the court released the matter for a fresh hearing because the earlier bench had not delivered its judgment within the stipulated time. The rehearing extended uncertainty around a substantial potential liability.
For a business, that uncertainty has a practical cost even before money changes hands.
Management must plan investment, funding and operations while allowing for an outcome that could materially change its finances.
A favourable outcome could remove some or all of that exposure. An adverse outcome could require additional resources, subject to the decision and any further remedies available.
The reported demand is therefore important, but so is its status. An amount being contested is different from a final payment obligation.
The cars have been sold. Who absorbs the extra cost?
Consider how a manufacturer sets a selling price.
It estimates component costs, import duties, assembly expenses, distribution costs and its expected margin. Those assumptions help determine whether a model is commercially viable.
Now imagine an additional duty demand arriving years after the sale.
The company cannot assume it can recover that cost from the original buyer. A customer who bought a car years ago is unlikely to accept a revised invoice because the manufacturer’s customs treatment has been challenged.
That creates a difficult mismatch: the revenue belongs to a completed sale, while the additional cost may arrive much later.
The commercial implication is that a historical tax dispute can affect future decisions. A company may need to reassess how much cash it can commit to a factory, a new model or an expansion.
A prospective business partner would also want to know who bears any liability arising from earlier imports. That allocation can matter as much as the price paid for a stake.
These are the reasons investors follow large tax disputes even when the disagreement appears to concern paperwork at a port.
What this says about manufacturing in India
Import duties are part of the economics of manufacturing.
A business deciding what to source locally and what to import needs to understand the applicable treatment. Authorities, meanwhile, need to ensure that import arrangements receive the classification required by law.
Both objectives depend on rules that can be applied consistently and disputes that can be resolved within the legal framework.
For investors, this adds another question to the usual review of sales, margins and market share:
How much of the business depends on a tax interpretation that is still being challenged?
The answer requires reading the company’s disclosures and following the proceedings, rather than treating either side’s argument as the eventual judgment.
Volkswagen’s case begins with car parts arriving at a port. Its financial consequences reach much further, into the cost of cars already sold and the money available to build the next ones.
Sources
- Volkswagen Group: Indian customs investigation statement
- Volkswagen Group Annual Report 2025: Litigation
- India Code: Customs Act, 1962, Section 28
- Reuters via Moneycontrol: October 29, 2026 court hearing
- Moneycontrol: Disputed imports and fresh hearing, August 25, 2026
- NDTV Profit: ₹11,526 crore customs duty demand
- Reuters via ETAuto: Bombay High Court rehearing, August 2026
Disclaimer: This article is for general information and does not constitute legal, tax or investment advice.