FPI Flows Since October 2024: Heavy Equity Selling, but Buying Elsewhere
Finnovate’s editorial team researches and creates financial content using trusted sources, regulatory references and inputs from subject experts.
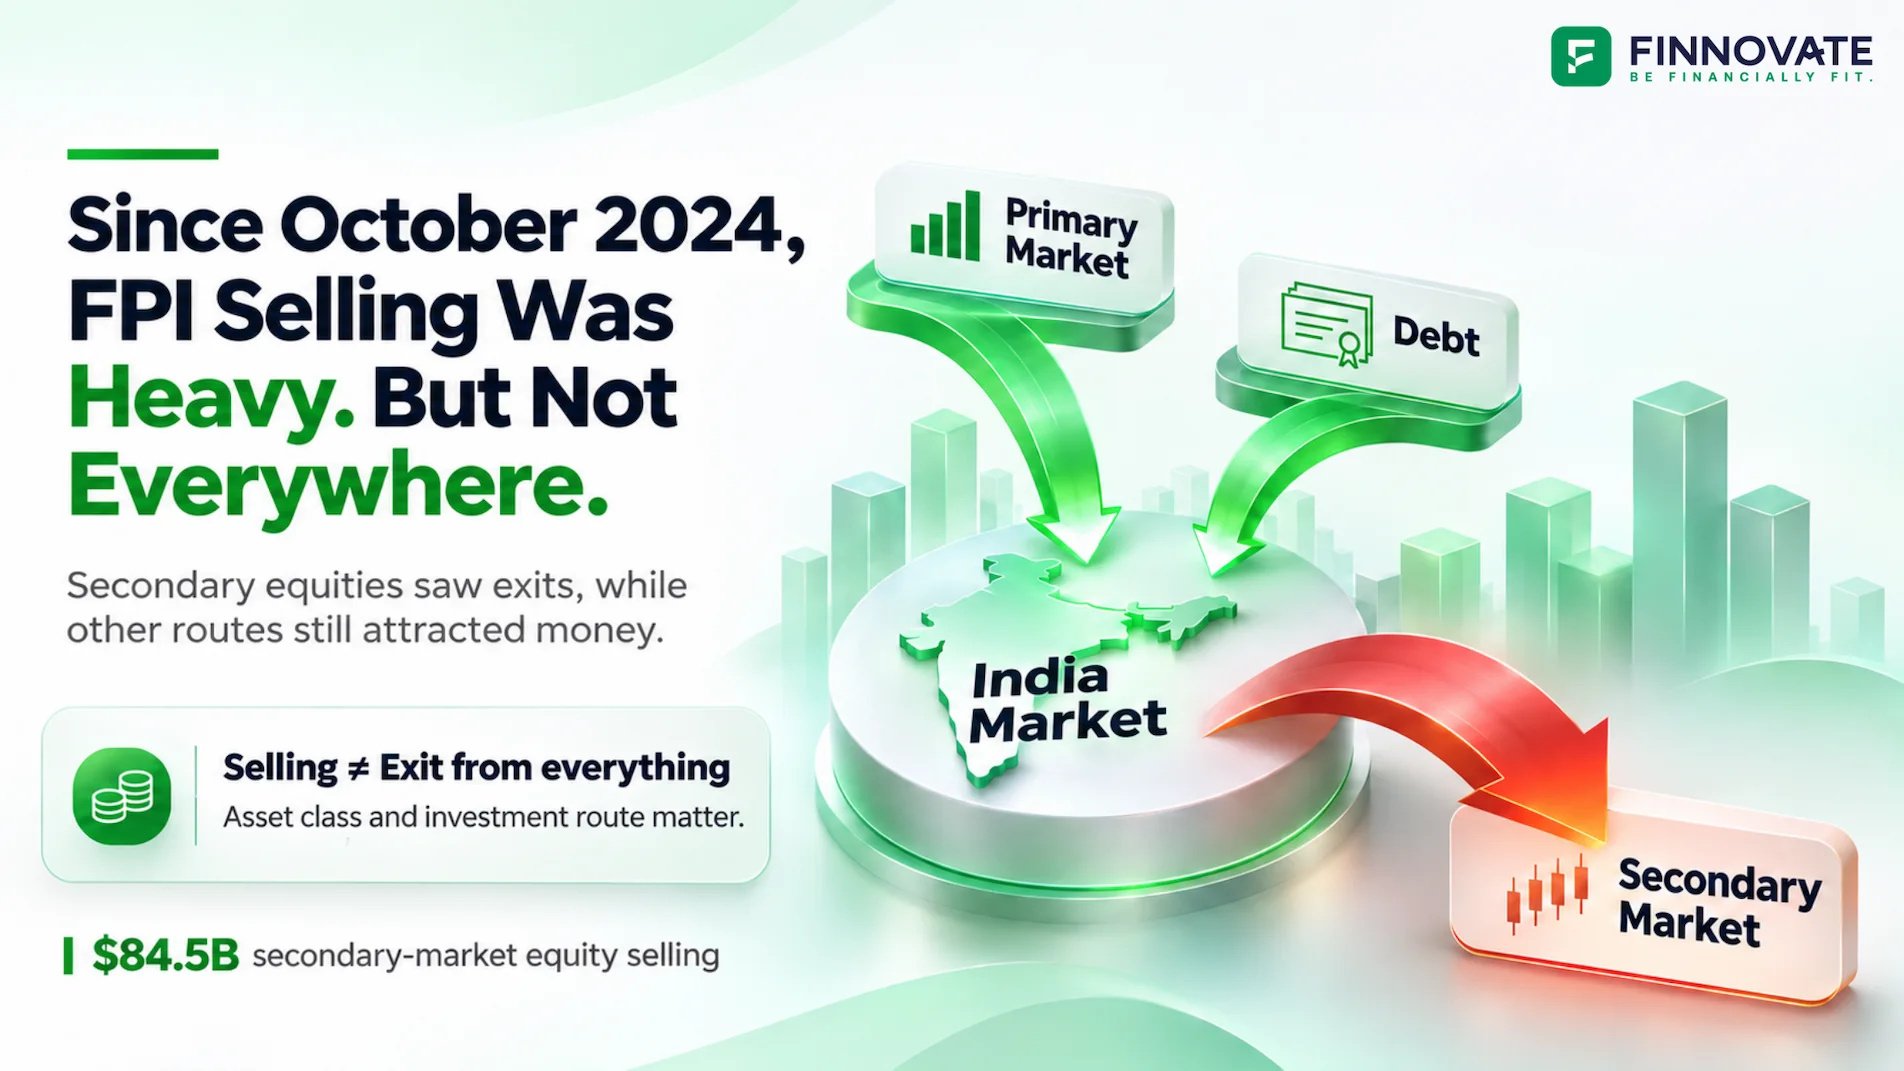
Foreign portfolio investors sold a net $84.53 billion in Indian secondary-market equities between October 2024 and October 2026.
But that figure captures only one part of their investment activity.
Over the same 25 months, net investment through the primary-market-and-other route reached $22.29 billion, while debt attracted $14.93 billion. These inflows partly offset the selling, bringing the combined net outflow from equities and debt to $47.31 billion.
The distinction matters. Foreign investors were substantial sellers of existing shares, while continuing to participate in other parts of India’s securities market. Looking at each route separately explains more than a single headline about foreign money leaving India.
How to read the FPI flow numbers
Foreign portfolio investors, or FPIs, invest in securities such as shares and bonds. The table separates their activity by investment route and asset class.
- Secondary-market equities: Net purchases or sales through the stock-exchange route.
- Primary market and others: Equity investment through routes including public issues, preferential allotments and rights issues. This category extends beyond IPOs.
- Net equity flows: Secondary-market equity flows plus primary-market-and-other equity flows.
- Debt flows: Net investment in the debt segment shown in the series.
- Combined equity and debt flows: The sum of net equity and debt flows. Other separately reported categories are outside this total.
A positive figure indicates net buying, while a negative figure indicates net selling. All figures in the main table are in US$ million; $1,000 million equals $1 billion.
Monthly FPI flows: October 2024 to October 2026
| Month | Secondary-market equities | Primary market & others | Net equity flows | Debt flows | Combined equity & debt |
|---|---|---|---|---|---|
| Oct 2024 | -13,556.91 | 2,361.48 | -11,195.43 | -277.31 | -11,472.74 |
| Nov 2024 | -4,661.58 | 2,098.36 | -2,563.22 | 22.43 | -2,540.79 |
| Dec 2024 | -296.29 | 2,124.66 | 1,828.37 | 1,241.58 | 3,069.95 |
| Jan 2025 | -9,491.57 | 448.70 | -9,042.87 | 80.29 | -8,962.58 |
| Feb 2025 | -4,802.34 | 824.99 | -3,977.35 | 1,180.36 | -2,796.99 |
| Mar 2025 | -637.33 | 236.11 | -401.22 | 4,246.15 | 3,844.93 |
| Apr 2025 | 395.09 | 115.00 | 510.09 | -2,844.72 | -2,334.63 |
| May 2025 | 2,134.26 | 209.68 | 2,343.94 | 1,292.52 | 3,636.46 |
| Jun 2025 | 976.42 | 713.89 | 1,690.31 | -2,594.36 | -904.05 |
| Jul 2025 | -3,707.94 | 1,655.51 | -2,052.43 | 1,418.38 | -634.05 |
| Aug 2025 | -4,458.59 | 464.71 | -3,993.88 | 1,655.47 | -2,338.41 |
| Sep 2025 | -3,072.59 | 371.04 | -2,701.55 | 1,289.94 | -1,411.61 |
| Oct 2025 | 448.08 | 1,208.13 | 1,656.21 | 2,374.44 | 4,030.65 |
| Nov 2025 | -1,765.73 | 1,341.11 | -424.62 | 744.64 | 320.02 |
| Dec 2025 | -3,370.80 | 855.36 | -2,515.44 | -1,771.98 | -4,287.42 |
| Jan 2026 | -4,279.80 | 304.00 | -3,975.80 | 741.05 | -3,234.75 |
| Feb 2026 | 2,184.27 | 312.43 | 2,496.70 | 1,670.00 | 4,166.70 |
| Mar 2026 | -13,200.00 | 476.20 | -12,723.80 | -876.66 | -13,600.46 |
| Apr 2026 | -6,721.90 | 247.56 | -6,474.34 | -1,084.86 | -7,559.20 |
| May 2026 | -3,780.86 | 330.47 | -3,450.39 | 366.95 | -3,083.44 |
| Jun 2026 | -5,646.01 | 488.53 | -5,157.48 | 5,688.84 | 531.36 |
| Jul 2026 | 712.18 | 1,410.98 | 2,123.16 | 2,070.50 | 4,193.66 |
| Aug 2026 | 1,819.77 | 1,284.71 | 3,104.48 | -433.13 | 2,671.35 |
| Sep 2026 | -4,761.37 | 1,011.10 | -3,750.27 | -2,358.89 | -6,109.16 |
| Oct 2026 | -4,989.41 | 1,390.66 | -3,598.75 | 1,089.19 | -2,509.56 |
| Total | -84,530.95 | 22,285.37 | -62,245.58 | 14,930.82 | -47,314.76 |
Scroll horizontally to view the full table →
Figures in US$ million. The period covers 25 months. The combined column includes the equity and debt figures shown above.
What stands out across the 25 months?
Secondary-market selling was persistent, but buying returned in some months
FPIs were net sellers through the secondary-market equity route in 18 of the 25 months.
The largest monthly outflows in this column were $13.56 billion in October 2024 and $13.20 billion in March 2026. Together, those two months accounted for $26.76 billion of selling.
There were also periods of net buying, including April–June 2025 and July–August 2026. The overall outflow therefore reflects repeated selling interrupted by recoveries in foreign demand.
Primary-market investment softened the equity outflow
The primary-market-and-other column remained positive in every month of the series.
Its cumulative $22.29 billion inflow reduced the secondary-market outflow of $84.53 billion to a net equity outflow of $62.25 billion.
December 2024 illustrates the difference. FPIs sold $296.29 million through the secondary market, but invested $2,124.66 million through primary-market and other transactions. Overall equity flows for the month were consequently positive at $1,828.37 million.
An investor can be selective about buying newly offered securities while reducing exposure to existing listed holdings. At the aggregate level, these transactions can also involve entirely different foreign institutions.
Debt sometimes changed the direction of the combined figure
Debt attracted a cumulative $14.93 billion, although individual months included both buying and selling.
In June 2026, equity outflows reached $5.16 billion, while debt inflows were $5.69 billion. The combined result was a small net inflow of $531.36 million.
April 2025 showed the reverse. Equity attracted $510.09 million, but debt recorded outflows of $2,844.72 million, leaving the combined figure negative.
The asset-class split is therefore essential when assessing the direction of foreign investment.
How the flows compare across financial years
The 25-month period spans parts of three financial years.
| Period | Secondary-market equities | Primary market & others | Net equities | Debt | Combined equity & debt |
|---|---|---|---|---|---|
| Oct 2024–Mar 2025: six months of FY25 | -33.45 | 8.09 | -25.35 | 6.49 | -18.86 |
| Apr 2025–Mar 2026: full FY26 | -27.72 | 8.03 | -19.69 | 3.10 | -16.59 |
| Apr 2026–Oct 2026: seven months of FY27 | -23.37 | 6.16 | -17.20 | 5.34 | -11.86 |
Scroll horizontally to view the full table →
Figures in US$ billion, rounded to two decimal places. Period lengths differ.
The final six months of FY25 recorded more secondary-market selling than the whole of FY26.
During April–October FY27, secondary-market outflows reached $23.37 billion. Primary-market-and-other investment of $6.16 billion reduced the net equity outflow to $17.20 billion, while debt buying reduced the combined outflow further to $11.86 billion.
These periods are useful for locating the selling across financial years. Their different lengths matter when comparing the pace of withdrawals.
October 2026: Selling continued, with offsets elsewhere
October’s figures followed the broader pattern:
- Secondary-market equity outflow: $4.99 billion.
- Primary-market-and-other equity inflow: $1.39 billion.
- Net equity outflow: $3.60 billion.
- Debt inflow: $1.09 billion.
- Combined equity and debt outflow: $2.51 billion.
Compared with September, secondary-market selling increased slightly. However, stronger primary-market investment reduced the net equity outflow, and debt moved from net selling to net buying.
Consequently, the combined outflow narrowed from $6.11 billion in September to $2.51 billion in October.
The improvement came from the mix of flows, even as selling through the secondary-market equity route continued.
What should investors take from these figures?
The strongest finding is the difference between persistent secondary-market equity selling and continued investment through other routes.
The data records transactions, rather than the reasons behind every investment decision. Valuations, earnings expectations, currency movements, interest rates and portfolio mandates can influence different investors in different ways.
For Indian investors, FPI activity is useful market context. A sustained selling trend can affect demand for shares, but an individual investment still needs to be assessed against its earnings outlook, valuation and place in the portfolio.
The next monthly release should be read on the same basis: where buying and selling occurred, how much each category contributed, and whether the change persisted beyond a few sessions.
FAQs
1. How much did FPIs sell in secondary-market equities from October 2024 to October 2026?
The 25-month series shows net secondary-market equity selling of $84.53 billion. After including primary-market-and-other equity inflows, the net equity outflow was $62.25 billion.
2. Does “primary market and others” mean only IPO investment?
The category includes IPO participation and other transactions, such as preferential allotments and rights issues. Its total should therefore be described using the broader category name.
3. Why can FPI equity outflows differ from the combined equity and debt figure?
Equities and debt can attract different flows in the same month. Debt buying can partly offset equity selling, while debt selling can increase the combined outflow.
4. Did foreign investors buy Indian equities in any months during this period?
Yes. FPIs were net buyers through the secondary-market equity route in seven of the 25 months, including April–June 2025 and July–August 2026. Across all equity routes shown in the table, eight months recorded net inflows.
Disclaimer: This article is for information and education only and is not investment advice or a recommendation to buy or sell any security. Investment decisions should reflect your financial goals, risk tolerance and investment horizon.