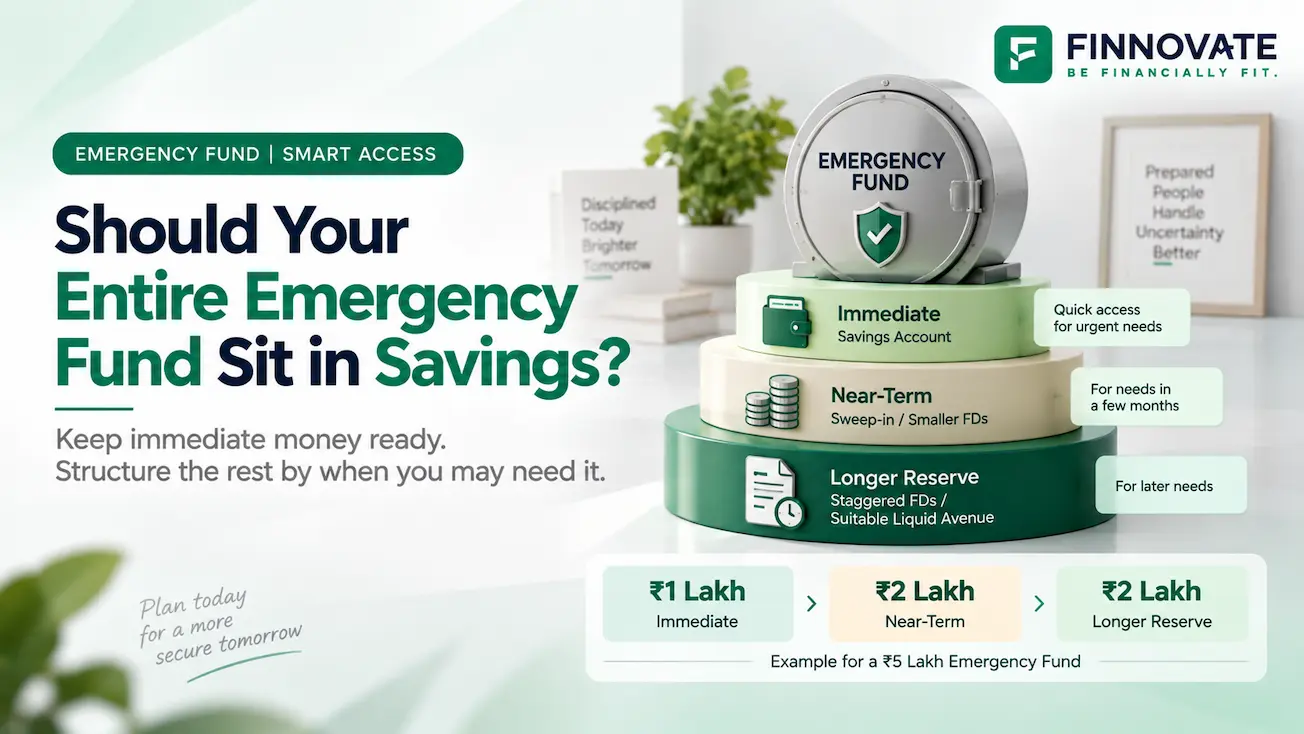
Should I Keep My Emergency Fund in a Savings Account?
Should your emergency fund stay in a savings account? Learn how to split it across savings...
22 September 2026
Finnovate’s editorial team researches and creates financial content using trusted sources, regulatory references and inputs from subject experts.
When you are expecting a baby, some expenses are easy to picture: hospital bills, baby clothes and a cot. Others take more thought. Can the household manage if one parent takes unpaid leave? What will insurance actually pay? And how much can you save for your child while paying EMIs and investing for retirement?
You do not need to solve the next twenty years before your baby arrives. Start with the costs and income changes closest to you, then build a plan for the years ahead.
Financial planning for new parents in India covers six priorities: a baby budget, an emergency reserve, insurance, education savings, retirement and family documents. Here is how to work through them.
The first question is simple: how much money will you need, and when? Split the answer into initial costs and regular expenses so a hospital bill does not get mixed up with the monthly budget.
| Initial costs to estimate | Regular costs to budget for |
|---|---|
| Delivery and hospital charges you must pay | Baby care essentials |
| Consultations and tests before birth | Medical visits and vaccinations |
| Essential baby purchases | Childcare or household help |
| Home arrangements, if needed | Any increase in household bills |
Ask the hospital for an estimate and check what sits outside the package. Then confirm what your insurance will cover. Leave room for expenses that differ from the estimate.
Confirm paid-leave terms and benefits with your employer. If you are self-employed or expect unpaid leave, calculate the household shortfall for that period.
For example, assume essential spending after birth is ₹90,000 a month, including EMIs and insurance provisions. If income falls to ₹65,000 for six months, the gap is ₹25,000 a month. The planned leave fund would be ₹1.5 lakh.
This example excludes delivery costs, emergency savings and any investments you want to continue. Add those separately. If the gap feels difficult to fund, review optional spending and the leave budget before taking on new commitments.
Having money in the bank can feel reassuring. But if most of it is needed for delivery and unpaid leave, how much is left for an unexpected bill or a longer income break?
Money committed to planned expenses should not also be counted as your emergency reserve.
Track three amounts separately: birth-related expenses, the planned income gap and emergency savings. You can do this within your existing accounts; the important part is knowing what each amount is for.
As a planning guide, start by assessing six months of essential expenses. Consider whether nine to twelve months would be more suitable if you depend on one income, have variable earnings or have limited financial support. These are starting points, not rules for every family.
Include essential baby costs, EMIs and insurance premiums. Keep the reserve accessible and avoid relying on equity investments for expenses that may arise at short notice. Use Finnovate’s emergency fund calculator to compare amounts.
An existing insurance policy is a starting point. The next step is to understand whether it fits the family’s changed needs.
Use your policy documents to work through these questions and seek written confirmation where the terms are unclear.
| What to check | Question to ask |
|---|---|
| Maternity benefit | Is delivery covered, and have I met the waiting-period conditions? |
| Limits and exclusions | How much may I need to pay myself? |
| Newborn benefits | When does cover begin, and which expenses are included? |
| Enrolment | What deadline, documents and payment apply to adding the baby? |
| Employer cover | What happens during leave or after leaving the job? |
Do not assume that buying a policy during pregnancy will cover the upcoming delivery. Budget using confirmed benefits, and check newborn cover separately from maternity cover.
Assess the support your family would need for household expenses, loans, education and other dependants. Then account for existing cover and assets genuinely available for those needs.
A salary multiple alone misses these details. Avoid counting your home as readily available money if the family would need to keep living in it.
Consider both parents’ contributions, including unpaid childcare that might need paid replacement. The appropriate cover and eligibility need an individual assessment.
“Saving for my child” is a useful intention, but it does not tell you when the money must be ready. School admission and college fees have different timelines.
| Education expense | Main planning priority |
|---|---|
| School admission due in the next few years | Keep the required money available by the payment date. |
| Recurring school fees | Make provision through the household budget and planned savings. |
| Higher education many years away | Estimate the future cost and build a suitable long-term portfolio. |
For near-term payments, prioritise access and capital preservation. If considering debt mutual funds, assess the scheme’s risks; they are not guaranteed bank deposits. SEBI’s Riskometer considers factors including credit risk and interest-rate sensitivity. Read SEBI’s Riskometer guidance.
Longer-term goals may allow equity exposure, depending on your ability to bear losses and your overall finances. Review the mix as fees approach and plan a gradual reduction in market risk.
At an assumed 7% annual increase, a course costing ₹20 lakh today would cost about ₹67.6 lakh in 18 years.
This is an illustration, not an education-cost forecast. Actual costs depend on the course, institution and location. Use Finnovate’s child education planning calculator to test assumptions, then review the target over time.
You do not need a product labelled “child plan” to save for education. If evaluating one, compare costs, cover, guarantees, lock-ins, exit terms and payout dates against your needs.
Once education becomes a goal, it can feel natural to direct every spare rupee towards it. Before doing so, check what that leaves for your own retirement and existing commitments.
Work out the amount available after essential spending, EMIs, insurance and required reserves. Then decide how education and retirement contributions can share that amount. If the goals do not fit, review the budget, contribution levels or goal assumptions rather than relying on higher investment returns to close the gap.
A temporary reduction in investments may be necessary during leave. Set a date to review it so a short pause does not become an open-ended one. Finnovate’s retirement calculator can help you explore the effect of revised contributions.
If expensive debt is putting pressure on the budget, assess repayment alongside saving and investing. Preserve enough accessible money for essential family needs.
Could your spouse or another trusted adult locate the family’s policies, investments and loan details if needed? Organising this information is a practical part of preparing for parenthood.
Keep a secure record of the child’s birth certificate, insurance documents, accounts, liabilities and key contacts. Review nominations and ask each institution about the requirements if you name a minor.
Discuss your will, guardianship wishes and arrangements for managing the child’s money with a qualified lawyer. Updating a nomination alone should not be treated as completing the family’s estate plan.
Before birth
Soon after birth
Once spending settles
Your baby's needs, education goals and retirement all draw on the same household income. Finnovate's financial planning service can help you assess them together and set priorities suited to your circumstances.
Book a financial planning discussion with Finnovate.Add expected out-of-pocket birth costs, initial purchases and the income gap during planned leave. Keep emergency savings separately. There is no single amount suited to every household.
Prioritise essential expenses, required repayments, protection needs and accessible reserves. Start long-term contributions at a sustainable level and review them as income allows.
Assess its limits, maternity and newborn terms, and what happens if employment ends. Whether additional cover is needed depends on those terms and your family’s circumstances.
It can help track gifts and savings, but it is not a prerequisite for planning. Check the bank’s minor-account requirements and consider how the money will eventually be used.
No. A SIP is a way to invest regularly in a mutual fund. You can use other contribution patterns and suitable investments. Regularly review whether the amount saved is enough for the goal.
Disclaimer: This article provides general financial education, not personalised investment, insurance, tax or legal advice. Examples and assumptions are illustrative. Insurance benefits depend on policy terms. Consult an appropriate professional for advice suited to your circumstances. Investment in securities market are subject to market risks. Read all the related documents carefully before investing. SEBI registration does not guarantee the intermediary’s performance or assure investment returns.
No spam. Only new posts, simple explainers, and practical money checklists for busy professionals.
Finnovate is a SEBI-registered financial planning firm that helps professionals bring structure and purpose to their money. Over 3,500+ families have trusted our disciplined process to plan their goals - safely, surely, and swiftly.
Our team constantly tracks market trends, policy changes, and investment opportunities like the ones featured in this Weekly Capsule - to help you make informed, confident financial decisions.
Learn more about our approach and how we work with you:
No comments yet. Start the conversation. What would you add?
No spam. Only new posts, simple explainers, and practical money checklists.
You may also like
Should your emergency fund stay in a savings account? Learn how to split it across savings...
FD vs corporate bonds: compare returns, YTM, safety, liquidity, tax and credit risk to und...
Financial planning for DINK couples in India covering cash flow, emergency funds, investme...
Already investing in mutual funds, stocks, EPF or NPS? Understand financial planning vs in...
Popular now
Learn how to easily download your NSDL CAS Statement in PDF format with our step-by-step g...
Looking for the best financial freedom books? Here’s a handpicked 2026 reading list with...
Learn what SIF investment means in India, SEBI rules, Rs 10 lakh minimum investment, avail...
Clear guide to mutual fund taxation in India for FY 2025–26 after July 2024 changes: equ...