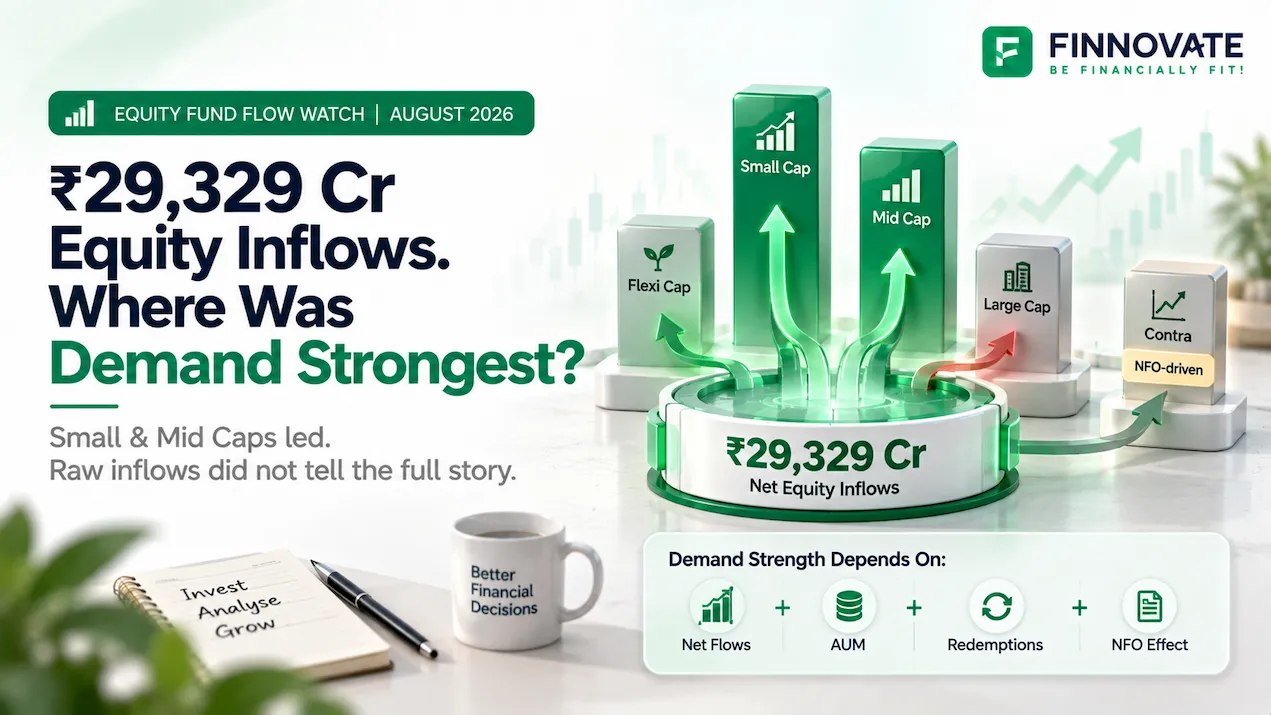
Equity Mutual Fund Inflows August 2026: Which Categories Led?
Equity mutual funds received ₹29,329 crore in August 2026. See which categories saw the ...
15 September 2026
CA with 35+ years of experience in taxation, specialising in income tax, capital gains, strategic tax planning and NRI taxation.
India’s SIP culture is booming because it makes investing disciplined and stress-free. The next decision after starting a SIP is when and how much to increase your monthly contribution. That choice - Regular SIP vs Step-Up (Top-Up) SIP - can decide whether you simply “do okay” or actually hit your long-term number.
A Step-Up (Top-Up) SIP automatically increases your SIP every year by a fixed percentage (e.g., +5%/+10%) or a fixed amount (e.g., +₹1,000), so contributions keep pace with income and inflation.
We know equity SIPs over long periods are a powerful way to build wealth. But affordability today can be a real constraint. If you can invest only ₹5,000/month now, you may still reach a bigger goal by stepping up that SIP each year instead of taking more risk or giving up on the goal. This section shows how Step-Up SIP India works in practice.
Assume a young professional invests ₹5,000/month for 25 years.
If we model an illustrative annualised return of ~12%, the total contribution is ₹15 lakh and the end corpus is ~₹85.11 lakh. That’s about 5.5× the money you put in but still short if your target is ₹2 crore.
You could raise the SIP to ~₹12,000/month from Day 1 to aim for ₹2 crore, but that may not be affordable today. The practical middle path: start with ₹5,000 and step it up each year.
In a Step-Up SIP India plan, you begin at ₹5,000/month and increase the SIP amount annually, keeping the new amount unchanged for the next 12 months. Here’s an illustration with different step-up rates.
| Details | Regular SIP | Step-Up 5% | Step-Up 10% | Step-Up 15% |
|---|---|---|---|---|
| Start SIP | ₹5,000/m | ₹5,000/m | ₹5,000/m | ₹5,000/m |
| Annual Step-Up | 0% | 5% | 10% | 15% |
| Illustrative Return | ~12% p.a. | ~12% p.a. | ~12% p.a. | ~12% p.a. |
| Tenure | 25 yrs | 25 yrs | 25 yrs | 25 yrs |
| Total Contribution | ₹15.00 lakh | ₹28.64 lakh | ₹59 lakh | ₹1.27 crore |
| Final Corpus | ₹85.11 lakh | ₹1.24 crore | ₹1.96 crore | ₹3.38 crore |
| Wealth Ratio (Corpus ÷ Contribution) | 5.67× | 4.33× | 3.32× | 2.66× |
Assumptions: monthly compounding; contributions at month-end; annual step-up applied once every 12 months; figures are illustrative only, not forecasts or guarantees.
What this tells you: Even a 5–10% annual step-up can meaningfully improve outcomes versus a flat SIP. As step-up rates rise, more money is invested later, so the wealth ratio falls (less time to compound). That’s normal - choose the lowest step-up that still meets your goal.
Try our Step-Up SIP Calculator for your assumptions -->
Use these three guardrails.
Your future monthly SIP balloons with higher step-ups. Sense-check these:
| Step-Up Rate | Starting SIP (Month 1) | Monthly SIP in Year 25 |
|---|---|---|
| 5% | ₹5,000 | ₹16,125 |
| 10% | ₹5,000 | ₹49,249 |
| 15% | ₹5,000 | ₹1,43,126 |
If those numbers look unrealistic, reduce the step-up or raise the base SIP gradually.
For a ₹2 crore target over 25 years at ~12% (illustrative), a ~10% annual step-up from ₹5,000/month gets you into the zone in this model. If still short, either increase today’s base SIP, extend tenure, or moderate the target.
To test a different target, use Finnovate's goal-based SIP calculator. It works backwards from your goal amount and deadline to estimate the starting SIP, while also allowing for inflation, existing savings and an annual step-up.
Very high step-ups create pressure later and raise the risk of pausing or stopping SIPs. For most salaried professionals, 5–10% per year aligns well with typical increments and inflation.
Rule of thumb: If your salary typically grows 6–10% annually, pick a 5–10% percentage step-up. If increments are uneven or you want predictability, use a fixed ₹ step-up and review yearly.
Run the numbers: Use a Step-Up SIP calculator to check whether ₹5,000 start + 10% step-up meets your corpus - or how much base SIP you need if you cap step-up at 5%.
Yes. In India, platforms often use both terms for the same feature - automatically increasing your SIP by a chosen % or ₹ amount at a fixed frequency (usually annual).
Annual step-ups are simpler, align with salary cycles, and are supported by most tools. If cash flows are lumpy, a half-yearly fixed-amount top-up can work, but review liquidity.
It can build a larger corpus but the wealth ratio falls because more money arrives late. Pick the lowest step-up that still achieves your goal to reduce behaviour risk.
Most platforms let you modify or skip a top-up. If finances are tight, freeze the step-up (keep the SIP running) instead of stopping entirely.
If income typically grows 6–10% annually, a 5–10% step-up mirrors that well. If income is volatile, a fixed ₹ top-up offers predictability; re-check the plan each year.
If affordability is limited today, a Step-Up SIP India plan (5–10% annually or a fixed ₹ top-up) is a practical way to reach a bigger corpus without over-risking your portfolio - and without breaking your monthly budget.
Disclaimer: All numbers are illustrative and for education only, not investment advice or guarantees. Returns are market-linked. Consider costs, taxation, and your risk profile. Ensure adequate emergency fund and insurance before increasing investment commitments.
No spam. Only new posts, simple explainers, and practical money checklists for busy professionals.
Finnovate is a SEBI-registered financial planning firm that helps professionals bring structure and purpose to their money. Over 3,500+ families have trusted our disciplined process to plan their goals - safely, surely, and swiftly.
Our team constantly tracks market trends, policy changes, and investment opportunities like the ones featured in this Weekly Capsule - to help you make informed, confident financial decisions.
Learn more about our approach and how we work with you:
No comments yet. Start the conversation. What would you add?
No spam. Only new posts, simple explainers, and practical money checklists.
You may also like
Equity mutual funds received ₹29,329 crore in August 2026. See which categories saw the ...
When should you exit a mutual fund? Learn when to hold, stop a SIP, rebalance or redeem ba...
Mutual fund AUM rose ₹3.54 lakh crore in July 2026. See how much came from fresh inflows...
Small- and mid-cap funds drew nearly 7x more inflows than large-cap funds from February to...
Popular now
Learn how to easily download your NSDL CAS Statement in PDF format with our step-by-step g...
Looking for the best financial freedom books? Here’s a handpicked 2026 reading list with...
Learn what SIF investment means in India, SEBI rules, Rs 10 lakh minimum investment, avail...
Clear guide to mutual fund taxation in India for FY 2025–26 after July 2024 changes: equ...