Can India Build the Hardware Behind the AI Boom?
Explore India’s AI hardware opportunity through the proposed Adani–Jabil venture, from...
14 October 2026
Finnovate’s editorial team researches and creates financial content using trusted sources, regulatory references and inputs from subject experts.
An overseas fund wants to invest in an Indian business. Before choosing the investment, it has another decision to make: where should the entity holding that investment be based?
For years, Mauritius was a popular choice. Its tax treaty with India helped shape the returns investors could keep when they sold their investments.
But that choice now comes with an additional question: why was Mauritius chosen?
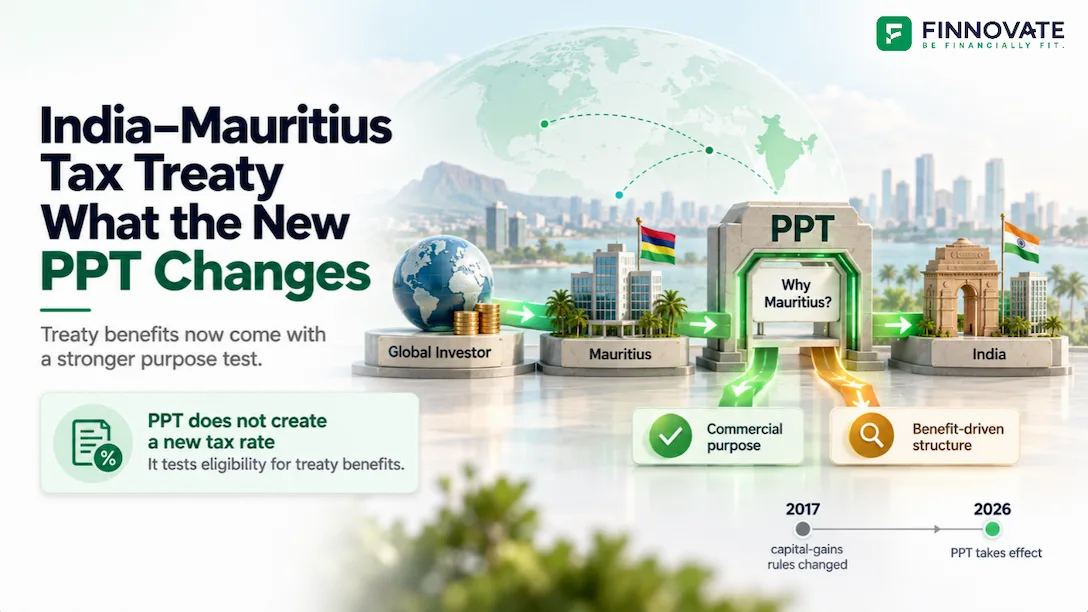
India notified an amendment to the India–Mauritius tax treaty on October 13, 2026, introducing the Principal Purpose Test, or PPT. The protocol entered into force on August 10, 2026.
The test allows treaty benefits to be denied where obtaining them was one of the principal purposes of an arrangement, subject to an important exception linked to the treaty’s purpose.
For foreign investors, the issue is how this changes the tax treatment of their investments. For India, the challenge is applying the rule consistently while preserving the benefits intended for genuine cross-border business.
A double taxation avoidance agreement, or DTAA, sets out how two countries share taxing rights over income earned across their borders. It can also provide relief from double taxation.
The India–Mauritius treaty became particularly relevant because of its treatment of capital gains.
Historically, gains from the sale of shares in Indian companies by qualifying Mauritius residents were generally taxable only in Mauritius under the treaty. This made the jurisdiction attractive for holding Indian investments.
The arrangement also raised a concern: investors based elsewhere could establish an entity in Mauritius primarily to access benefits negotiated between India and Mauritius.
This is commonly called treaty shopping.
Consider a hypothetical fund whose investors, investment team and commercial operations are based outside Mauritius. It inserts a Mauritius entity into its ownership structure to obtain favourable treaty treatment.
That raises a different question from a fund using Mauritius as an established base for managing and administering investments. Understanding the reasons behind the structure becomes central to assessing its treaty claim.
The PPT arrives after an earlier reform that significantly changed the Mauritius route.
Under the 2016 protocol, India obtained taxing rights over gains from shares in Indian companies acquired on or after April 1, 2017. A transitional concession applied to certain gains arising between April 2017 and March 2019, subject to conditions.
The acquisition date matters for older shares. Shares acquired before April 1, 2017 fall within the treaty’s capital-gains grandfathering framework.
Grandfathering preserves specified treatment for qualifying older investments. The April 2017 cutoff refers to when the shares were acquired, rather than a date when all protection expired.
| Date | Development |
|---|---|
| May 10, 2016 | India and Mauritius signed the protocol changing capital-gains taxation. |
| April 1, 2017 | The acquisition cutoff for the revised rules on shares in Indian companies. |
| March 7, 2024 | The countries signed the protocol introducing PPT. |
| August 10, 2026 | The PPT protocol entered into force. |
| October 13, 2026 | India notified the protocol. |
↔ Scroll horizontally to view the full table.
The latest amendment adds a broader examination of eligibility for treaty benefits. It does not introduce a new tax rate.
The rule has two connected parts.
First, authorities consider the relevant facts and circumstances. Could they reasonably conclude that obtaining a treaty benefit was one of the principal purposes of the arrangement or transaction?
That wording matters. Securing the benefit need not be the only reason, or even the dominant reason.
Second, the rule provides an exception. The claimant can establish that granting the benefit in those circumstances would accord with the object and purpose of the relevant treaty provisions.
The assessment therefore goes beyond identifying a tax saving. It asks why the arrangement exists and whether the benefit being claimed fits what the treaty provision was intended to achieve.
A tax residency certificate establishes where an investor is resident for tax purposes. Claiming a treaty benefit also requires meeting the conditions attached to that benefit, including the Principal Purpose Test where applicable.
The practical consequence is greater attention to the reasons behind a structure.
A fund claiming treaty relief should be able to explain its commercial choices and support that explanation with records.
Depending on the arrangement, relevant evidence could include:
These are examples of potentially relevant facts, rather than a statutory checklist.
An office address, local directors or additional paperwork cannot, by themselves, settle a question about the purpose of an arrangement. Equally, the assessment needs to account for the actual nature of the business. An investment holding entity performs different functions from a factory or a retail operation.
For investors, maintaining evidence when decisions are made is more useful than trying to reconstruct the commercial explanation years later.
This is where the dates need careful handling.
CBDT’s January 2025 guidance states that PPT is intended to apply prospectively. It also specifically keeps the grandfathering provisions in the Mauritius, Singapore and Cyprus treaties outside PPT’s scope, leaving them governed by the relevant treaty provisions.
That is an important protection for qualifying older holdings.
However, the age of an entity and the tax treatment of a particular income receipt are separate questions. A structure established years ago may continue to receive income or undertake transactions after the rule takes effect. Its founding date alone cannot settle every subsequent treaty claim.
There is another distinction. CBDT’s March 2025 clarification says its PPT guidance does not displace domestic or judicial anti-abuse rules.
Grandfathering therefore needs to be assessed against the particular investment, benefit and applicable provision. Treating every pre-2017 arrangement as protected from every possible tax challenge would go beyond the guidance.
A tax rule affects more than the amount eventually paid. It also affects how confidently an investor can estimate that amount before committing money.
If treaty eligibility is uncertain, a fund may need additional advice, more documentation and a more cautious estimate of its eventual tax liability. A dispute can also take time and resources to resolve.
These are possible business consequences, rather than evidence that the amendment has already caused investors to withdraw money.
The concern about overreach deserves attention because purpose must be inferred from facts. Different interpretations of the same commercial arrangement could produce disputes.
But the official guidance also requires an objective, case-specific assessment. A well-reasoned application should connect the facts of the arrangement to the benefit being claimed.
For Indian investors following foreign capital flows, this is the relevant connection: the predictability of tax treatment forms part of an overseas investor’s assessment of an investment. It sits alongside valuation, earnings prospects, currency exposure and other considerations.
PPT gives authorities a way to challenge arrangements designed to secure treaty benefits contrary to the purpose of the relevant provisions.
Its effectiveness will depend on the quality and consistency of those assessments.
Genuine investors need to understand what supports a valid claim. Tax authorities need to explain why a particular arrangement crosses the line. Existing protections need to be applied according to their terms.
The question behind the Mauritius route has become more demanding. An investor must be prepared to explain both the benefit being claimed and the commercial arrangement supporting it.
The protocol entered into force on August 10, 2026. India notified it on October 13, 2026, through Notification No. 135/2026.
PPT governs entitlement to treaty benefits. Where a benefit is denied, the tax consequences depend on the income involved and the applicable law.
CBDT’s January 2025 guidance keeps the treaty’s grandfathering provisions outside PPT’s scope. Eligibility depends on the specific holding and treaty provisions, while other applicable anti-abuse rules remain relevant.
Disclaimer: This article is for general information and is not investment, tax or legal advice. Treaty eligibility and tax treatment depend on the facts of each case and applicable law. Consult a qualified professional before acting.
No spam. Only new posts, simple explainers, and practical money checklists for busy professionals.
Finnovate is a SEBI-registered financial planning firm that helps professionals bring structure and purpose to their money. Over 3,500+ families have trusted our disciplined process to plan their goals - safely, surely, and swiftly.
Our team constantly tracks market trends, policy changes, and investment opportunities like the ones featured in this Weekly Capsule - to help you make informed, confident financial decisions.
Learn more about our approach and how we work with you:
No comments yet. Start the conversation. What would you add?
No spam. Only new posts, simple explainers, and practical money checklists.
You may also like
Explore India’s AI hardware opportunity through the proposed Adani–Jabil venture, from...
India’s CPI inflation rose to 5.54% in September 2026. Compare monthly trends, food pric...
The Shiller CAPE ratio is near its 1999 peak. Explore what it means for US stock valuation...
Can Starlink change internet access in India? Explore why Jio and Airtel signed deals, how...
Popular now
Learn how to easily download your NSDL CAS Statement in PDF format with our step-by-step g...
Looking for the best financial freedom books? Here’s a handpicked 2026 reading list with...
Learn what SIF investment means in India, SEBI rules, Rs 10 lakh minimum investment, avail...
Clear guide to mutual fund taxation in India for FY 2025–26 after July 2024 changes: equ...