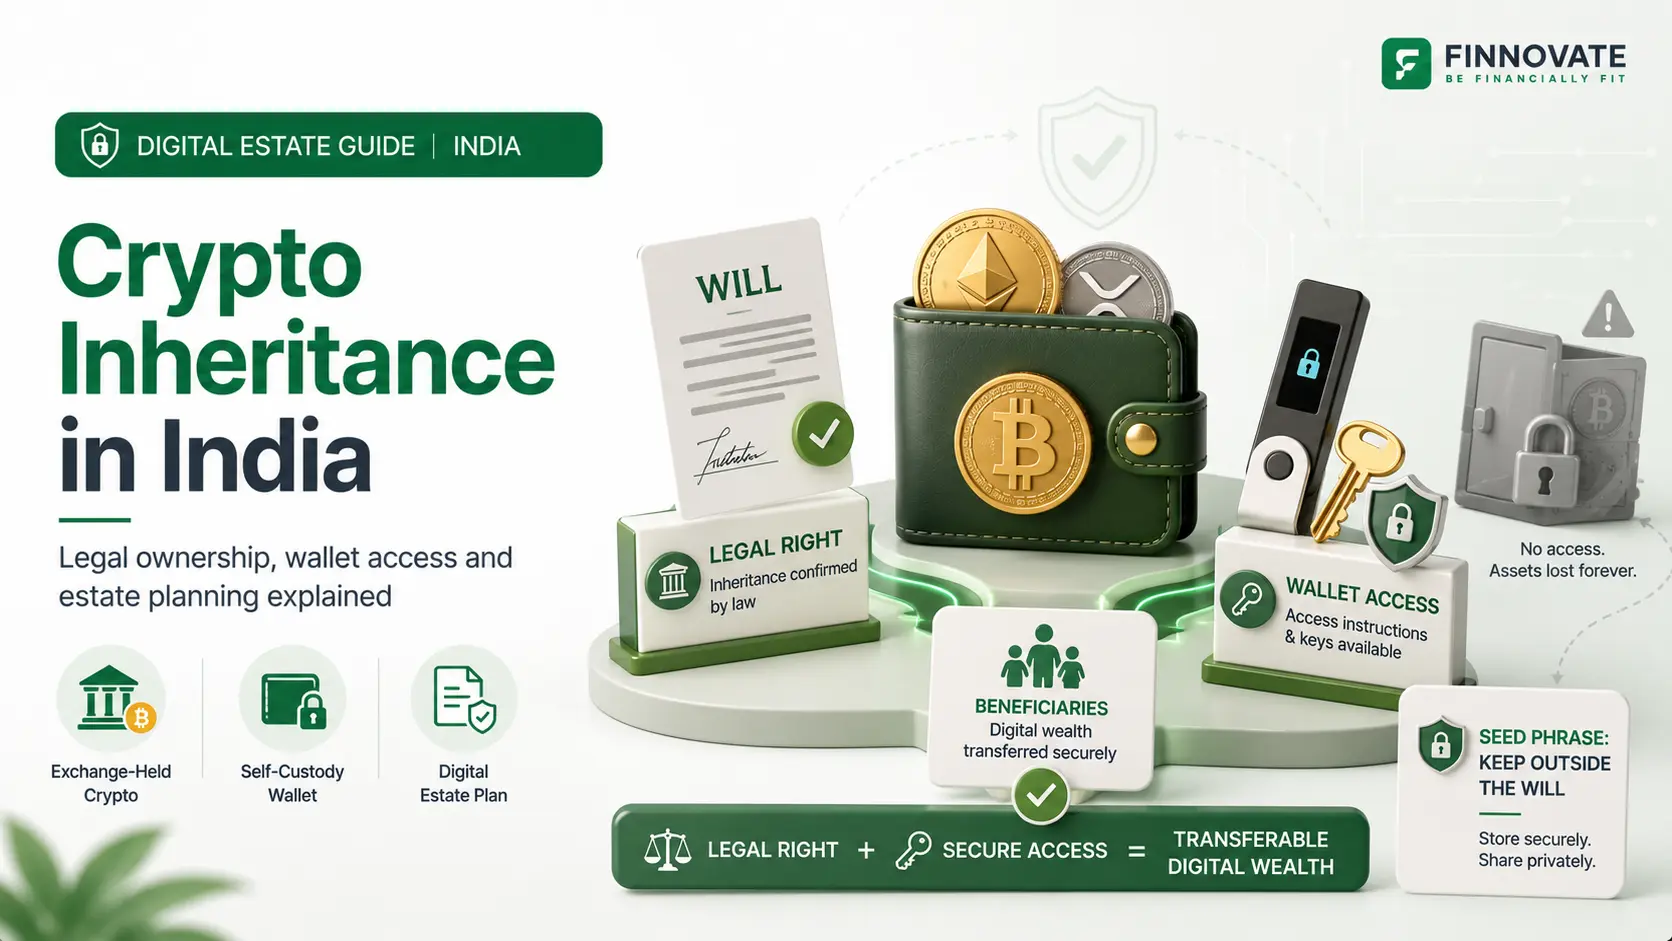
Crypto and Digital Asset Inheritance in India: Law, Planning and Tax
Lost seed phrase = lost crypto forever. This India guide explains how to plan your digital...
30 April 2026
Finnovate’s editorial team researches and creates financial content using trusted sources, regulatory references and inputs from subject experts.
Last reviewed: 16 October 2026
A private family trust lets trustees hold and manage assets for chosen family members under a written set of rules. In India, creating one means deciding its purpose, beneficiaries and trustees, preparing the trust deed, meeting any stamping and registration requirements, and legally placing the intended assets in the trust.
Consider Pradeep, who owns flats, a manufacturing business and investments. One child lives abroad, another helps run the business, and his younger daughter needs long-term support because of a disability. A Will can say who inherits his assets. A trust can also set out who manages them, how money is paid for care, and what happens if a trustee can no longer serve.
But a trust is not automatically better than a Will, a tax-saving shortcut or protection against every creditor. Its value depends on what the family wants to achieve and which assets can legally and sensibly be transferred.
Quick answer: the settlor establishes the trust and identifies the trust property. The trustee holds and manages that property under legal duties. The beneficiaries receive the benefits permitted by the deed. A living trust can operate during the settlor's lifetime; a trust created by Will generally starts after death.
The key point is the separation between holding property and benefiting from it. The trustee holds legal title in a fiduciary capacity, which means the trustee must act according to the trust and the law, not treat trust assets as personal property. A beneficiary has a beneficial interest and enforceable rights under the trust.
The trustees hold the legal title to trust property, subject to the beneficiaries' rights. A private trust is not a company and does not have the same independent legal personality as a company or LLP. For income-tax administration, trustees may be assessed as representative assessees. A trust may also need its own PAN and separate banking arrangements for operating and reporting purposes.
The settlor can sometimes be a trustee or beneficiary, but the roles must create a real trust obligation. A person cannot simply keep unrestricted personal ownership and label the property a trust. The deed, the transfer and the practical conduct must align.
A properly created and funded living trust can operate during the settlor's lifetime. Merely signing a deed does not necessarily transfer every asset into it: property registration, demat or institution-level changes and other formalities may be required. A testamentary trust is established through a Will and generally takes effect after the testator's death.
Quick answer: identify the purpose and beneficiaries, choose trustees, list assets, draft the trust deed, complete the required stamping and registration, transfer the intended property, and arrange banking, tax reporting and records. The exact steps differ according to whether the trust holds land, financial assets or business interests.
Legal basis: Sections 5 and 6 of the Indian Trusts Act, 1882 address formal creation and the certainty required around the purpose, beneficiary and property. A deed with no identifiable trust property or incomplete legal transfer may fail to achieve the intended result.
| Document or detail | Why it is needed | Important note |
|---|---|---|
| Settlor and trustee identity details | To identify the people creating and managing the trust | KYC evidence depends on the registrar, bank and institution involved |
| Beneficiary details | To identify who benefits and on what terms | Distribution rights should be clear, especially in a specific trust |
| Asset and ownership records | To identify property to be settled | Property deeds, shareholding records, loan documents or investment statements may be relevant |
| Trust deed and distribution instructions | To record powers, limits, entitlements and succession | Lawyer-drafted provisions are especially important for complex families |
| Stamping, registration and transfer papers | To satisfy the relevant legal requirements | Exact documents vary by state and asset type |
| PAN, bank and reporting information | To operate the trust and meet tax duties | Institutions may request their own trust KYC and beneficial-ownership information |
The Indian Trusts Act does not prescribe one universal minimum corpus for every private family trust. However, the trust needs identifiable property, and the practical amount should justify the legal work, transfer costs and ongoing administration. A family with modest assets and straightforward beneficiaries may be better served by a properly drafted Will.
Common mistake: registering a trust deed does not mean every asset mentioned in a family plan has moved into the trust. Maintain an asset-by-asset transfer checklist, and verify the stamp duty and tax implications before signing any transfer documents.
Quick answer: there is no fixed all-India registration or setup price. The total is the professional drafting and advisory cost, applicable stamp duty, registration and transfer charges, plus ongoing accounting and trustee expenses. A trust holding immovable property may cost much more to fund than one with simpler movable assets.
| Cost item | What determines the amount | How to budget |
|---|---|---|
| Legal drafting and structuring | Number of beneficiaries, special conditions, companies, foreign connections and complexity | Seek an itemised quote from the lawyer; there is no statutory standard fee |
| Tax and FEMA advice | Trust type, assets, source of funds, beneficiaries and cross-border elements | Request a separate review before settling assets |
| Stamp duty | State law, instrument type, disposition of property and value | Obtain an official duty calculation for the exact transaction |
| Registration and transfer charges | Property location, registrations and institution procedures | Verify with the Sub-Registrar and relevant intermediaries |
| PAN, banking and KYC | Administrative needs and provider charges | Allow for documentation and any service fees |
| Annual accounting and tax | Income, number of assets, reporting, audit and transactions | Seek an annual CA quote, not merely a setup quote |
| Professional or corporate trustee | Scope of duties, size and complexity of assets, provider terms | Compare fixed, asset-based and transaction-based fee structures |
In Maharashtra, Article 61 of the Maharashtra Stamp Act distinguishes between a trust declaration that disposes of property and one that does not. For a non-charitable trust involving a disposition of property, the duty is linked to the conveyance-duty provisions. A flat-rate estimate such as "1% to 5%" is therefore unreliable across states and deed structures. Check the Maharashtra Stamp Act and obtain a transaction-specific assessment before funding the trust.
Suppose a family estate is worth ₹5 crore and total trust setup and transfer costs are estimated at ₹20 lakh. That is 4% of the estate value upfront, not 0.4%. Ongoing expenses would be additional. This is an illustration of cost comparison, not an estimate of stamp duty for a particular property.
When comparing quotes, ask whether the fee includes tax structuring, deed revisions, property transfers, execution support, bank onboarding and a year of compliance. A cheaper drafting quote that excludes these items is not necessarily a cheaper trust.
Private family trusts are often described using two different questions: Can the settlor revoke the arrangement? And are beneficiaries' shares fixed or left to trustee discretion? These produce four common combinations, not four separate legal registration categories.
Beneficiary shares are fixed, and the settlor generally cannot take back the property merely by choice.
Tax treatment depends on representative-assessee rules, the type of income and applicable exceptions.Trustees choose distributions within the deed's limits. Flexibility may help where needs change.
Maximum marginal rate rules may apply where shares are indeterminate, subject to statutory exceptions.Shares are defined, but the settlor retains rights that may amount to revocation under tax law.
Income-attribution rules can tax income as the settlor's income.The deed may combine revocation rights with trustee discretion about distributions.
Tax and control consequences require detailed review. Flexibility does not guarantee savings.Revocability is not determined by the label on the document alone. Under Sections 97 and 98 of the Income-tax Act, 2025, a transfer can be treated as revocable if its terms allow assets or income to return to the transferor or allow the transferor to re-assume control. Exceptions and timing rules also apply. An irrevocable trust usually involves giving up rights over the property, so the decision should not be made purely for tax reasons.
In a specific (determinate) trust, the deed identifies the beneficiaries and their shares clearly. In a discretionary trust, trustees have defined discretion to decide who receives what among the permitted beneficiaries. Choosing between the two depends on the family's needs, the required flexibility and the tax result under the law.
A testamentary trust is declared through a Will and generally begins after the testator's death. It can provide long-term management for a child or dependent without transferring the relevant assets into a living trust today. Particular testamentary trusts may qualify for an exception to the maximum marginal rate under Section 307 of the Income-tax Act, 2025, but the conditions must be checked.
A trust earns its place in an estate plan when it solves a management or succession problem that simpler instruments do not solve well. Six situations deserve consideration.
The deed can provide for education, health, housing and recurring care expenses, with successor trustees continuing oversight. A family should also assess any disability-specific laws and support arrangements.
Minors can inherit and own property in India, but legal guardians manage it subject to applicable restrictions. A trust can provide a separate framework for management and staged benefits; it does not automatically eliminate every requirement for court approval.
A trust may simplify ongoing management of assets with different beneficiaries or locations. It cannot prevent a valid legal challenge, and proper transfer documents remain essential.
A trust may help define voting, benefits and succession for business interests, subject to corporate documents and transfer restrictions. It does not automatically shield family assets from every business liability or creditor claim.
Resident trustees may be able to manage Indian assets while beneficiaries live overseas. NRI involvement brings additional FEMA, tax and reporting questions that must be resolved for the particular structure.
A trust can specify how money is used over years rather than transferring everything outright at one time. Trustees must be suitable, and restrictions should be drafted carefully so beneficiaries are treated fairly.
Asset protection has limits. Transfers made to defeat or delay creditors can be challenged. So can sham arrangements or transactions where beneficial control was not genuinely changed. A trust must not be treated as a guaranteed method of hiding assets or avoiding legitimate liabilities.
Quick answer: a Will is generally simpler and less expensive for an estate passing to adult heirs. A trust deserves consideration when assets need active management, beneficiaries require ongoing support, or a family wants detailed rules for distributions. Some estates need both.
| Factor | Will | Living private family trust |
|---|---|---|
| When it operates | Generally after the testator's death | Can operate once validly created and funded during the settlor's lifetime |
| Ownership and management | Executor or other legally authorised person handles estate administration after death | Trustees hold and manage assets under the deed |
| Benefits to dependents | Can direct inheritance or declare a testamentary trust | Can provide rules for recurring payments and long-term management |
| Upfront cost | Usually simpler drafting and execution | Legal, stamp, registration and property-transfer costs can be higher |
| Continuing administration | Estate administration as required after death | Trust accounting, asset management and tax compliance as applicable |
| Probate | Section 213 of the Indian Succession Act was omitted in 2025; probate can still be sought and may matter practically in some disputes or transactions | Assets validly held by living trustees do not pass under the settlor's Will merely because of death |
| Privacy | Probate proceedings, where pursued, can expose estate details | Some trust affairs may remain private, but registered instruments and legal disclosures may be accessible |
| Disputes and creditors | May face disputes over execution or inheritance rights | Can also be challenged; no blanket immunity from creditors or court scrutiny |
The Repealing and Amending Act, 2025 omitted Section 213 of the Indian Succession Act, which previously imposed mandatory probate requirements for certain Wills and locations. Probate remains a legal process and should not be described as abolished in every situation.
Practical decision: where assets are straightforward, adult heirs agree on the broad plan and no one needs long-term managed distributions, a Will with correctly reviewed nominations may be enough. Where continuing asset management is central, evaluate a trust alongside the Will rather than replacing the Will automatically.
There is no single tax rate for all family trusts. The answer depends on revocability, beneficiaries' shares, the type of income, business activities and statutory exceptions. The Income-tax Act, 2025 applies from 1 April 2026; earlier tax years remain subject to the law applicable to those years.
Quick answer: income linked to a revocable transfer may be included in the settlor's income under Section 97. Trustees of a written trust may be assessed as representative assessees under Sections 303 and 304. Where beneficiary shares are unknown, Section 307 generally points to the maximum marginal rate, with stated exceptions and special treatment for business income.
| Trust structure | Main tax principle | What needs checking |
|---|---|---|
| Revocable transfer | Relevant income may be attributed to the transferor under Section 97 | Rights retained under the deed; Section 98 definition and statutory exceptions |
| Irrevocable specific trust | Representative assessment is generally to the same extent as the persons represented under Section 304 | Beneficiary shares, income category, business income, special rates and clubbing rules |
| Irrevocable discretionary trust | Section 307 generally applies maximum marginal rate treatment when shares are indeterminate | Statutory exceptions; business income; surcharge, cess and special-rate income |
| Testamentary discretionary trust | A qualifying sole trust declared by Will may fall under the AOP-rate exception in Section 307(2) | Whether the Will and trust meet the conditions; different rules for business profits |
Sections 97 and 98 address transfers that can be revoked or where control can return to the transferor. Certain transfers that cannot be revoked during the beneficiary's lifetime may qualify for an exception, subject to conditions. Calling a deed "irrevocable" is not enough if its operative clauses give back the relevant rights.
Where beneficial shares are known, the trustees' assessment follows the representative-assessee framework under Sections 303 and 304. Broadly, the tax is determined in the same manner and to the same extent as it would be for the represented beneficiaries, subject to other relevant provisions. This does not mean trust income is always taxed at a lower rate, or that all trust receipts must simply be added to each person's return without checking the assessment position.
A trust earns ₹30 lakh of interest for two adult beneficiaries entitled to 50% each. Their defined shares are ₹15 lakh each. The tax adviser must determine the correct representative assessment, each beneficiary's applicable position and whether any special rule affects the income. It would be incorrect to promise a fixed family tax saving from these figures alone.
Section 307 provides for maximum marginal rate treatment where income is not specifically receivable for one person or beneficiaries' individual shares are unknown. Section 307(2) lists exceptions; Section 307(3) and (4) deal with business profits. The amount actually payable can also depend on applicable surcharge, cess, income classification and judicial interpretation. The maximum marginal rate should not be presented as a flat all-inclusive 30% tax.
A discretionary trust declared by Will may receive treatment at rates applicable to an association of persons if it is the only trust so declared by that person and the relevant conditions are met. That is not the same as promising the personal slab rates of each beneficiary. Business income has additional conditions under Section 307(4).
Income tax on annual earnings is only one part of the picture. Settling property, transferring investments or distributing assets can require a separate analysis of capital gains, taxation of receipts, stamp duty, transaction charges and withholding. Transfers involving non-relatives, property subject to debt or overseas persons require particular care. Do not assume every transfer to or from a trust is automatically tax-free.
Official reference: Income-tax Act, 2025, as amended by the Finance Act, 2026, especially Sections 97–98 and 303–307. The former provisions under the 1961 Act are relevant when analysing earlier tax years.
A trust is only as dependable as the people who operate it. Trustees control important decisions and owe duties to beneficiaries. Section 10 of the Indian Trusts Act describes who may be a trustee, including the need to be competent to contract when exercising discretion.
Appointing two trustees or a suitable professional trustee may reduce reliance on one person, but there is no universal rule that every private trust must have two. The deed and applicable legal requirements determine how trustees are appointed and replaced.
Trustees must preserve property, act prudently, maintain accounts and follow lawful trust instructions. Beneficiaries may have legal remedies when trustees breach their obligations. Trustee and executor roles are different: a trustee manages trust property under the deed, while an executor carries out duties relating to a deceased person's estate under a Will.
Quick answer: NRI families may use Indian private trusts, but the answer for a particular structure depends on the residence and citizenship of the settlor, trustee and beneficiaries; the assets involved; the source of funding; and FEMA requirements. Cross-border funding and distributions should be reviewed before execution.
An NRI's participation does not by itself make every trust structure permissible. The legal team must check restrictions on property acquisition and transfer, investment rules, beneficial ownership, tax residence and bank reporting. An Indian-resident trustee may help with administration, but appointing one does not automatically resolve FEMA compliance.
There is no general rule that every trust distribution can be sent abroad under the Liberalised Remittance Scheme (LRS). The RBI's LRS directions expressly state that the scheme is for resident individuals and is not available to trusts.
Different RBI permissions may be relevant depending on whether the payment represents current income, inheritance, sale proceeds or another type of capital transaction. RBI rules allow eligible NRIs/PIOs to remit up to USD 1 million per financial year in certain remittance-of-assets situations subject to conditions, but this is not a general annual allowance for distributions by any private trust. The authorised dealer bank should confirm the route and documents for the actual payment.
From 1 April 2026, Form 145 replaces the former Form 15CA, while Form 146 replaces the former Form 15CB. Whether information reporting, an accountant's certificate or tax withholding is required depends on the payment and the applicable rules. Not every outward payment needs both forms. See the Income Tax Department's Form 145 guidance.
Before drafting an NRI family trust: obtain a written tax and FEMA review of the settlor, all trustees and beneficiaries, each asset's ownership history, intended distributions and cross-border transfers. This is preferable to adding a generic FEMA clause after the deed is signed.
Start with the purpose, beneficiaries, trustees and assets. Have a lawyer draft the deed, meet applicable stamping and registration rules, complete the legal transfer of the intended assets, and arrange tax and account records. The exact process changes if the trust holds immovable property, shares or assets involving non-residents.
For a non-testamentary trust relating to immovable property, the Indian Trusts Act requires a signed and registered written instrument. For movable property, Section 5 permits creation through the prescribed declaration or transfer of ownership to the trustee. Registration, stamping, KYC and financial-institution requirements should be assessed separately for the chosen structure.
That can be possible, but the trust must still impose real legal duties for the benefit of someone other than an identical sole holder of all rights. Retaining control or benefits can also affect tax treatment under revocable-transfer rules. The roles and powers should be reviewed together, not just their labels.
No. A private family trust does not obtain a blanket income-tax exemption merely because it is a trust. The outcome depends on the income, the deed and the representative-assessee and other applicable rules under the Income-tax Act, 2025.
Not automatically. A genuine trust may change legal ownership, but laws protecting creditors, fraudulent-transfer rules, retained settlor rights and court orders can affect the assets. A trust should not be created to defeat existing lawful claims.
A Will directs what happens to an estate after death. A living trust can manage assets and provide benefits during the settlor's lifetime and continue afterwards. Some families use a Will for overall succession and a trust for property needing managed distributions.
Trustees may hold different kinds of transferable trust property, but each asset must be settled through the legally appropriate route. Property registration, lender consent, share-transfer restrictions or intermediary rules may apply. There is no universal one-step transfer procedure.
A private trust generally needs appropriate tax identification and financial records to operate its income and investments. The trustee's return-filing and other reporting duties depend on the trust's actual tax position and applicable rules for the relevant year. A CA should verify the filing requirement rather than assume every trust follows the same return process.
Finnovate can help assess the financial planning questions: what needs managing, how a trust compares with a Will, what costs to allow for and which specialist advice is needed. Trust drafting and legal opinions should be obtained from qualified legal professionals.
Book a free callDisclaimer: This article is for general education only and is not legal, tax or investment advice or a recommendation to create a trust. Trust creation, trustee powers, taxation, stamp duty, property transfers and FEMA compliance depend on specific facts and current law. Tax treatment under the Income-tax Act, 2025 is discussed for periods to which that Act applies. Any stamp duty or setup-cost illustration is not a fee quote. Seek advice from a qualified Indian advocate for the trust deed, a qualified tax professional for tax positions, and relevant FEMA or property specialists before acting. Finnovate's financial planning discussion does not replace those specialist opinions.
No spam. Only new posts, simple explainers, and practical money checklists for busy professionals.
Finnovate is a SEBI-registered financial planning firm that helps professionals bring structure and purpose to their money. Over 3,500+ families have trusted our disciplined process to plan their goals - safely, surely, and swiftly.
Our team constantly tracks market trends, policy changes, and investment opportunities like the ones featured in this Weekly Capsule - to help you make informed, confident financial decisions.
Learn more about our approach and how we work with you:
No comments yet. Start the conversation. What would you add?
No spam. Only new posts, simple explainers, and practical money checklists.
You may also like
Lost seed phrase = lost crypto forever. This India guide explains how to plan your digital...
Writing a Will in India? This clause-by-clause guide gives exact language for each section...
Who should be executor of your Will in India? The executor holds legal authority over your...
Learn what probate means in India, when it is needed, how the probate process works, and w...
Popular now
Learn how to easily download your NSDL CAS Statement in PDF format with our step-by-step g...
Looking for the best financial freedom books? Here’s a handpicked 2026 reading list with...
Learn what SIF investment means in India, SEBI rules, Rs 10 lakh minimum investment, avail...
Clear guide to mutual fund taxation in India for FY 2025–26 after July 2024 changes: equ...